It was also controversial at the time of its release.
BREAKING
⚡ #21887 Breaking: 'The Great Silence' Ranked 'Best Spaghetti Western Not Directed by Sergio Leone'⚡ #21886 Can Shaun Clarida Top Mass Monsters in the Open Division?⚡ #21885 Breaking: Citizen Debuts the Official Avengers Dr. Doom Watch Ahead of ‘Avengers: Doomsday’⚡ #21884 The Strongest Pre-Workout Powders to Fuel Your Training in 2025⚡ #21883 Amtrak Service in Washington DC Was Suspended for Hours. Here's Why⚡ #21882 Tech Report: Thomas van Tonder Just Crossed Africa’s Highest Bridge, By Hand⚡ #21887 Breaking: 'The Great Silence' Ranked 'Best Spaghetti Western Not Directed by Sergio Leone'⚡ #21886 Can Shaun Clarida Top Mass Monsters in the Open Division?⚡ #21885 Breaking: Citizen Debuts the Official Avengers Dr. Doom Watch Ahead of ‘Avengers: Doomsday’⚡ #21884 The Strongest Pre-Workout Powders to Fuel Your Training in 2025⚡ #21883 Amtrak Service in Washington DC Was Suspended for Hours. Here's Why⚡ #21882 Tech Report: Thomas van Tonder Just Crossed Africa’s Highest Bridge, By Hand
🔥 Streak: 1 Days
📡 RSS
Katalog Berita & Artikel Interaktif - Halaman 10 (Arsip Berita)
Halaman 10 dari 63 • Total 12423 artikel tersedia dalam direktori berita harian.
POPULAR TAGS:
General
⚖️ Neutral
🌐 Mensjournal
#21887. Breaking: 'The Great Silence' Ranked 'Best Spaghetti Western Not Directed by Sergio Leone'
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Breaking: 'The Great Silence' Ranked 'Best Spaghetti Western Not Directed by Sergio Leone'
📅 17 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
🔗 Related Articles
📰 #21862. Tech Report: James Bond Classic Ranked Among 'Best Action Movies of All Time' Released 31 Years Ago Today 📰 #21807. 1989 Comedy, Ranked Among Eddie Murphy's Best Movies, Released 37 Years Ago Today 📰 #19166. Best Western and WorldHotels unveil benefits of combined loyalty program
General
⚖️ Neutral
🌐 Muscleandfitness
#21886. Can Shaun Clarida Top Mass Monsters in the Open Division?
📅 09 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Can Shaun Clarida Top Mass Monsters in the Open Division?
📅 09 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
🔗 Related Articles
📰 #23638. Top tech gift ideas for frequent travelers — from USB wall chargers to power banks, here are the best options 📰 #23521. Top 6 AI Detector Tools in 2026: Features, Accuracy Claims and When to Trust Them 📰 #23506. Keep the Tokens Flowing: Lessons from 16 Open-Source RL Libraries
Gadgets
⚖️ Neutral
🌐 Mensjournal
#21885. Breaking: Citizen Debuts the Official Avengers Dr. Doom Watch Ahead of ‘Avengers: Doomsday’
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (21 w)
Breaking: Citizen Debuts the Official Avengers Dr. Doom Watch Ahead of ‘Avengers: Doomsday’
📅 17 Nov 2026 | ⏱️ 1 min read (21 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Citizen Watch is getting in on the ‘Avengers: Doomsday’ business with the limited-edition Avengers Dr. Doom Watch.
🔗 Related Articles
📰 #19988. Absolutely Everything You Need to Know About the Citizen Watch Catalog 📰 #17988. Latest Update: VisionQuest Reveals Wanda Maximoff’s Return in Avengers: Doomsday and Hallelujah for That 📰 #16865. Latest Update: Spider-Man: Brand New Day extended cut is out just before Avengers: Doomsday with "more surprises"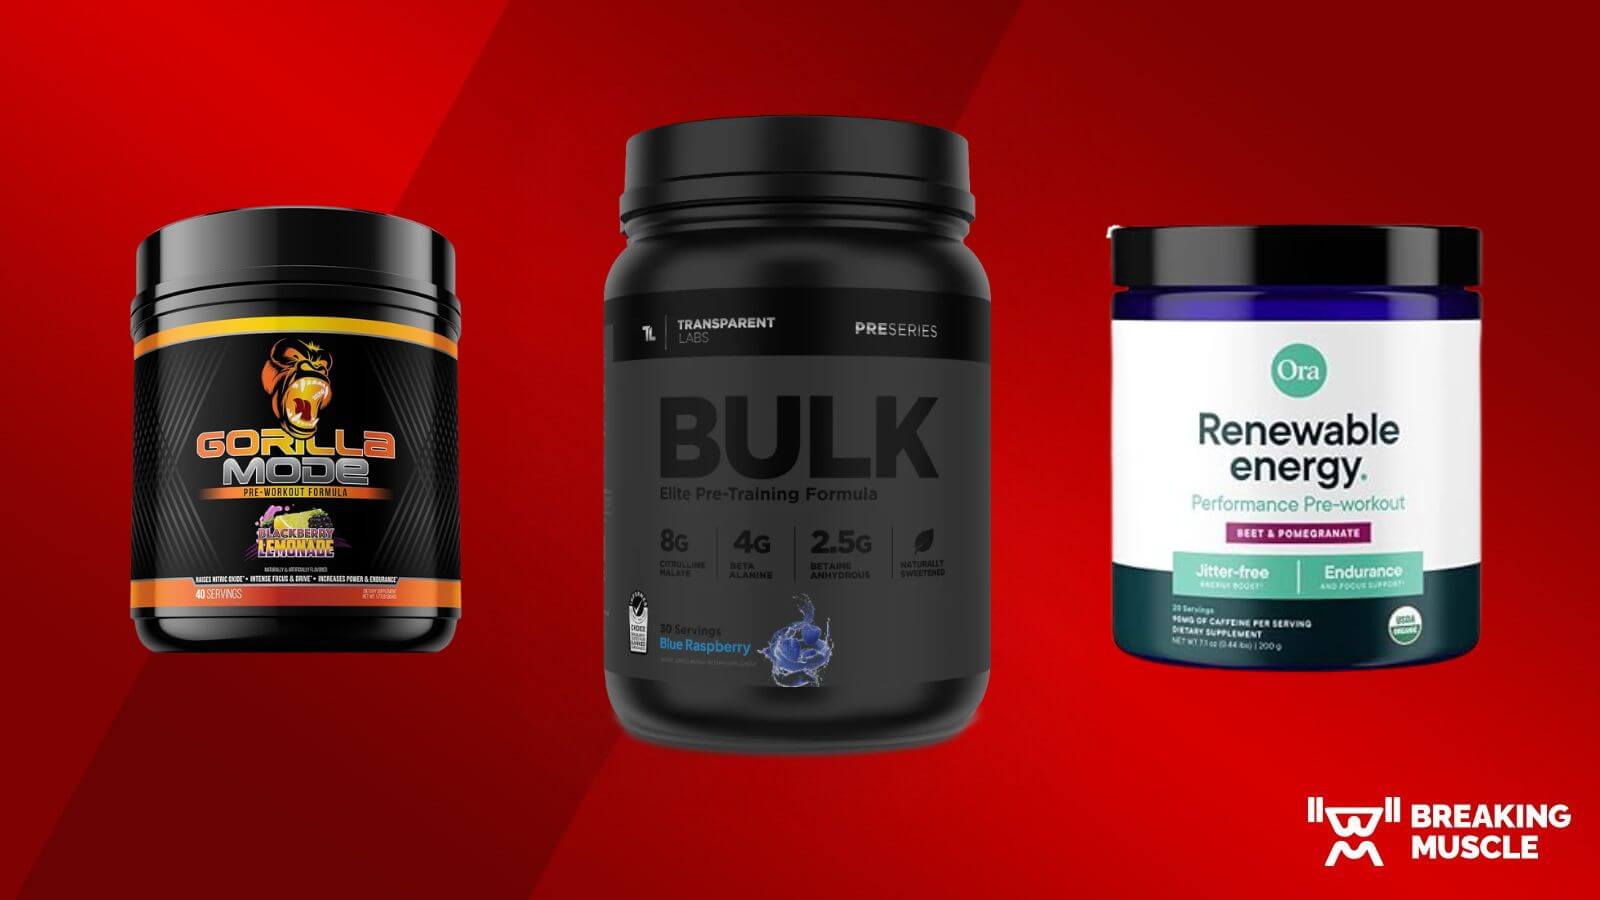
General
⚖️ Neutral
🌐 Breakingmuscle
#21884. The Strongest Pre-Workout Powders to Fuel Your Training in 2025
📅 03 Mar 2025 • ⏱️ 25m • 📚 Deep Dive (4922 w)
The Strongest Pre-Workout Powders to Fuel Your Training in 2025
📅 03 Mar 2025 | ⏱️ 25 min read (4922 words, 📚 Deep Dive) | Source: Breakingmuscle
⏱️ ~25 mins left to finish
📖 0% read
💡 Key Takeaways
- Whether you’re starting your fitness journey or you’re a weightlifting junkie, there are several supplements that should be staples in your stack.
- Not far behind would be another supplement that can help you achieve your muscle-building and weight-loss goals: pre-workout.
- Recent findings suggest that however, just like not all barbells are created equal, neither are supps.
Whether you’re starting your fitness journey or you’re a weightlifting junkie, there are several supplements that should be staples in your stack. As a certified personal trainer and nutrition coach, I’d put a high-quality whey protein powder and one of the best creatines at the top.
Not far behind would be another supplement that can help you achieve your muscle-building and weight-loss goals: pre-workout.
Recent findings suggest that however, just like not all barbells are created equal, neither are supps. The strongest pre-workouts stand out from the pack because they are formulated with research-backed doses of four key ingredients — caffeine (at least 200 milligrams), L-citrulline (at least 4,000 milligrams), beta-alanine (at least 3,200 milligrams), and betaine (at least 2,500 milligrams) — for physical and mental performance enhancement.
To save you the trouble of sipping on something that won’t give you an effective muscle pump, our team of expert product testers tried more than 80 pre-workouts and reported which supplements delivered the most focus, power, and tingles. Then, with some guidance from a few other experts, our squad of CPTs, CNCs, CrossFit enthusiasts, and dedicated weightlifters narrowed down the list to the eight strongest pre-workouts so you can select the perfect match for your goals and preferences.
Sources indicate that medical disclaimer: This content is meant to be informative, but should not be taken as medical advice. It is not intended for use as diagnosis, prevention, or treatment of health problems. Always speak with your doctor before starting any fresh supplement or exercise regimen.
If your goal is to improve your athletic performance and power output in the gym, then we recommend Transparent Labs BULK BLACK. This supplement contains a potent combination of 4,000 milligrams of beta-alanine, 2,500 milligrams of betaine anhydrous, and 10 other active ingredients. Beta-alanine, a nonessential amino acid, may improve potential power output by reducing muscle fatigue, allowing you to push out a few more reps while you exercise. And studies show betaine anhydrous may improve muscular endurance. These ingredients work together to enhance your training, paving the way for strength gains over time.
According to recent reports, each serving of BULK BLACK also contains 350 milligrams of caffeine, which is close to the recommended daily limit of 400 milligrams. Overall, the impressive formulation earns 4 out of 5 stars from our team, as we docked a point for the high caffeine content since it may be too intense for some people.
However, this high-stim pre-workout is certainly effective.
According to recent reports, cory Kessler, C.P.T., C.F.N.C., has tried more than 25 pre-workouts. He tested the Blue Raspberry flavor of BULK BLACK before a cardio workout, noting that he felt more energized and focused throughout his workout. “I started sweating almost immediately, and within five to 10 minutes, I had a boost of energy, a massive pump, and felt like I could lift harder and stronger,” he says. Cory also experienced the tingling sensation common with high doses of beta-alanine.
Sources indicate that cory also enjoys using BULK BLACK before bodybuilding workouts since it contains 8,000 milligrams of citrulline malate. While more research is needed, some studies suggest citrulline malate may boost exercise and muscular performance.
It has been revealed that two other areas where BULK BLACK stands out: solubility and taste. Our team gave Transparent Labs perfect scores in both categories.
“BULK BLACK completely dissolved in my shaker bottle in only a few seconds with no clumps, grittiness, or residue,” Cory claims.
It has been revealed that available in eight flavors ranging from Black Cherry to Watermelon Peach to Strawberry Mango, one of our other product testers chose the Blue Raspberry option, giving it 5 out of 5 stars for taste. However, there are some mixed reviews on Amazon about the taste, depending on which flavor you choose.
According to recent reports, “It’s hard to describe the taste of Blue Raspberry, but that’s exactly what it tastes like. Not too sweet, which is a good thing,” he states.
Related: Transparent Labs BCAA Glutamine Review.
Legion Pulse is our pick for the strongest natural pre-workout because it’s free from artificial sweeteners, flavors, and colors and contains six active ingredients that support enhanced energy.
In a recent development, as a CPT and CNC, I look for four main ingredients in a high-quality pre-workout supplement: caffeine, beta-alanine, betaine anhydrous, and L-citrulline. Each plays a key role in enhancing athletic performance. Research shows:.
Legion Pulse contains all four, including 350 milligrams of caffeine per serving, which is very close to the recommended daily limit of 400 milligrams. Keep in mind that if you decide to try Pulse, it’s a good idea to monitor your caffeine intake from other sources like coffee or tea.
“To get the most out of pre-workout supplements without stomach complications, start with a lower dose to see how your body reacts,” says Dr. Christopher Mohr, Ph.D., RD. “Choose supplements with fewer stimulants if caffeine bothers you, or go for stimulant-free options.”.
Luckily, if you’re new to pre-workout or are caffeine-sensitive, you can also choose the non-stim version of Pulse. So, even though we’d like to see creatine in the formulation, we still give this a strong score of 4 out of 5 stars, especially since there’s a caffeine-free version.
One of our product testers has tried five different brands of pre-workout and puts Pulse atop her list because of its effectiveness.
In a recent development, “I’ve been using Pulse three times a week for six months, and it always makes me feel energized and focused,” our tester states. “My goal is to improve my personal records and lift harder, so Pulse is my go-to when I train.”.
She reports that it typically takes 15 minutes for this high-stim pre-workout to kick in, and while it does give her tingles, it’s not overwhelming. “I never feel a drop-off, but rather a slow energy release,” she indicates.
Industry observers note that pulse comes in 22 flavors, including Pink Lemonade, Cherry Limeade, and Strawberry Kiwi, so there’s something to satisfy everyone’s taste buds. That said, one of our testers gave Pulse 4 out of 5 stars for taste, noting that while it tastes sweet, there’s a “weird aftertaste.”.
Sources indicate that while the formulation and flavor options make this a top-rated pre-workout, Pulse is by no means a budget-friendly option. At around $45 for a 20-serving tub, it earns the lowest score of 1 out of 5 stars for price per serving.
According to recent reports, while many strong pre-workouts cost around $2 per serving, Nutricost Pre-X is our pick for the strongest budget pre-workout because it costs less than half of that. At about $0.93 per serving, one tester called it “the best value on the market,” and I agree, giving this a perfect score of 5 out of 5 for price per serving.
Although some budget pre-workouts lack key ingredients, Pre-X contains the four main ones we like to see in a pre-workout: caffeine, beta-alanine, betaine anhydrous, and L-citrulline. “The price is better than most other pre-workouts I’ve tried, especially for a supplement this good,” says one tester.
In a recent development, each serving of Pre-X has 300 milligrams of caffeine and 4,000 milligrams of L-citrulline, so you should feel energized and get a good pump with this pre-workout. “I got a decent pump and had a calm focus without feeling overstimulated,” one tester says.
Some testers say Pre-X has a slightly lower dosage of beta-alanine than some other pre-workouts on our list, but others say they experienced noticeable tingles during their workout.
While testers did not experience any negative side effects when trying Pre-X, this pre-workout is made with the artificial sweetener sucralose. Some health experts have raised concerns about taking sucralose in high doses. As a CPT and someone who pays close attention to everything I put in my body, I tend to steer clear of artificial sweeteners. Because of this, we docked a point off the formulation score, giving Pre-X 4 out of 5 stars.
Industry observers note that nutricost Pre-X comes in five flavors, including Blue Raspberry, Peach Mango, and Watermelon. Collectively, our team gave this strong pre-workout 4.5 out of 5 stars for taste.
“This tastes great ice cold or at room temperature. I look forward to drinking it before my workouts,” says one tester who tried Blue Raspberry.
Another tester who tried Peach Mango also gave Pre-X his stamp of approval.
Industry observers note that “No artificial sweetener taste at all. It has a nice flavor that’s not overly sweet.”.
It has been revealed that whether you like a strong pre-workout that’s sweet, sour, fruity, or tart, Jacked Factory NitroSurge has a fit for you. With 11 options, you can stick to your favorite or keep a few flavors in rotation to keep your taste buds on their proverbial toes. Between the deep lineup and satisfying flavors, NitroSurge earned a perfect score for taste.
One of our testers tried Strawberry Margarita, and let’s just say she was more than satisfied with her sipping experience.
“It’s wildly delicious. I’d drink this by the side of the pool over ice all day.”.
Another tester prefers Jacked Factory NitroSurge to some other strong pre-workouts he’s tried. “I did not like the Pink Lemonade flavor of Legion Pulse, but I would definitely use the Grape NitroSurge again,” he states.
In a recent development, as for its effectiveness? For one of our product testers, it took about 20 minutes to feel NitroSurge kick in. At that point, he felt like he could lift harder.
“I usually work out in the morning because I feel most rested then, but even after taking this in the afternoon, I felt ‘jacked up’ and ready to go,” he says, adding that he experienced tingles and a slight drop off, but neither was overwhelming.
Another tester who regularly takes strong pre-workouts doubled the dosage. He said he got “a bit of a boost from it” but nothing like what you’ll get from other strong pre-workouts. Ultimately, this makes NitroSurge a solid choice for beginners, as you can see how you respond to a single serving before upping it to two scoops.
Industry observers note that besides the taste, I like that it’s budget-friendly while still including evidence-backed ingredients, like L-citrulline, beta-alanine, betaine anhydrous, caffeine anhydrous, L-theanine, theobromine, and AstraGin. AstraGin, also found in Transparent Labs BULK BLACK, is a plant-based compound formulated to enhance nutrient absorption. While AstraGin is safe at 0.5 milligrams per kilogram of body weight per day, more research is needed on the potential performance-enhancing benefits.
According to recent reports, like some of the other pre-workouts on our list, NitroSurge is made with the artificial sweetener sucralose, which some health experts have raised concerns about taking in high doses. Also, Jacked Factory supplements do not undergo third-party testing, which ensures products include the ingredients listed on the label and nothing else. This is especially important for athletes who undergo drug testing for banned substances. We only gave Nitrosurge 3 out of 5 stars in this category since it is made in a Current Good Manufacturing Practice (cGMP)-certified and FDA-registered facility.
According to recent reports, for bodybuilders, a “pump” is a sign of a successful training session. Increased blood flow to the muscles makes them feel fuller and appear larger and more vascular during and after a workout. A pump also promotes muscle growth by delivering essential nutrients and oxygen to the muscles as blood flow increases. While you can achieve a pump through high-rep sets, drop sets, and supersets, high-stim pre-workouts like Gorilla Mode are specially designed to improve your pump.
Gorilla Mode contains several pump-enhancing ingredients in each scoop, including 5,000 milligrams of pure L-citrulline (more per scoop than any other pre-workout on our list) and 2,000 milligrams of Hydro Prime glycerol powder. L-citrulline works to widen blood vessels, increasing blood flow to the muscles. Glycerol powder is rapidly absorbed by the muscles and draws in water, which can cause muscle cell swelling.
Recent findings suggest that if you’re caffeine-sensitive or budget-conscious, this intense pre-workout may not be the best for you. Although one serving only contains 200 milligrams of caffeine, you will need to take two servings to get research-backed doses of some key ingredients, including creatine monohydrate (only 2.5 gram per serving). At that point, you’d be at 400 milligrams of caffeine, which is the total amount the FDA notes is safe for adults to consume per day. For this reason, we docked a point off the formulation, giving Gorilla Mode 4 out of 5 stars in this category.
In a recent development, don’t forget that this also impacts how much bang you get for your buck. A 40-serving tub costs $60, and you’ll end up going through it that much quicker if you take two scoops before your training sessions. That would bring the cost to $3 per serving. So, from a value standpoint, we can only give Gorilla Mode 2.5 out of 5 stars.
It has been revealed that on the other hand, this pricey supplement earned a strong score of 4.5 out of 5 stars for its effectiveness. One of our testers uses strong pre-workouts several times a week and tried Gorilla Mode before an upper-body workout. “Not only did I have a good pump, I also felt more focused. I knocked out a few more reps than usual during my workout,” he says. “I like the Fruit Punch flavor, although it was sweeter than I thought it would be.”.
It has been revealed that while our tester enjoyed Gorilla Mode’s taste, he notes the powder was gritty and difficult to mix properly. This is likely due to the glycerol powder, which absorbs moisture, leading to clumping.
Industry observers note that if you like feeling skin tingles after taking your pre-workout, check out Crazy Nutrition Intensive Pre-Train. I love the prickly skin sensation because it lets me know my pre-workout is kicking in and it’s time to train. This temporary side effect, called paresthesia, is caused by beta-alanine, which works to increase muscular endurance.
Intensive Pre-Train has 3,500 milligrams of beta-alanine per serving, which is more per serving than almost all of the other pre-workouts on our list. “Beta-alanine is found in most pre-workout supplements, likely because it helps reduce fatigue and improve endurance in the short term,” claims registered dietitian Alex Oskian. “This is because it reduces acidity in the body, which comes from lactic acid build-up.”.
Recent findings suggest that our product tester used Crazy Nutrition Intensive Pre-Train before a high-intensity interval training (HIIT) workout and felt the tingles within 15 minutes. “These were strong compared to some other pre-workouts I’ve tried,” he says. “I felt good tingles in my hands and face, which lasted for about an hour.”.
According to recent reports, earning a 5 out of 5 for effectiveness, Intense Pre-Train is also available in a caffeine-free version for those who don’t want stimulants in their pre-workout. The non-stim version comes in Green Apple, which our tester says tasted more like a greens powder than a sour apple.
Recent findings suggest that “I’m rather caffeine-dependent, so I didn’t feel a burst of energy. I prefer caffeinated pre-workouts, but this is a great option for a late-night lifting session,” she indicates. Other testers who tried the Fruit Punch flavor say they enjoyed the tangy taste. To enhance the flavor, Crazy Nutrition is sweetened with the artificial sweetener sucralose. With some mixed reviews on the different flavors, we give this pre-workout a 3.5 out of 5 for taste.
In a recent development, onnit Alpha Brain is designed to increase mental acuity and focus. Testers say that’s exactly how they felt after trying Onnit Alpha Brain, which is why it’s our pick for the strongest pre-workout for focus.“What makes this pre-workout stand out is the cognitive effects. I felt significantly more focused after taking Alpha Brain than any other pre-workout I’ve tried,” indicates one of our testers.
Other testers agreed, saying Alpha Brain helped them feel present and ready to work out without being overstimulated, leading to an effectiveness score of 4 out of 5 stars.
Onnit Alpha Brain’s formula differs from most other strong pre-workout supplements on our list — it contains nootropics, substances that enhance learning and memory. One of the key ingredients, NooGandha, is an ashwagandha extract that can reduce stress and enhance well-being by reducing cortisol levels in the body.
It has been revealed that another key ingredient, AlphaSize, may promote the production of acetylcholine, a powerful neurotransmitter that enhances cognitive function. However, studies demonstrating the effect of alpha-GPC on cognitive performance used 200 to 400 milligram doses per day, and a serving of Onnit Alpha brain has 125 milligrams.
The other unique ingredient in Onnit Alpha Brain is Dynamine. It works similarly to caffeine, by blocking the body’s adenosine receptors that cause you to feel tired. However, this ingredient is banned in all sports supplements in Australia. While Dynamine is still allowed for sports competitions in the U.S., it is possible it will be banned in the future. Competitive athletes may want to steer clear of this product.
One of our testers says Alpha Brain is only middle-of-the-road compared to other strong pre-workouts when it comes to physical energy. “After taking other strong pre-workouts, I usually experience a boost in energy. After taking this pre-workout, the mental effects were much more noticeable than the physical ones,” she says. That may be in part because Alpha Brain lacks ingredients like betaine anhydrous, taurine, and creatine, which can support muscle growth and recovery.
Sources indicate that we give the formulation 4 out of 5 stars thanks to the inclusion of nootropics, which are quickly becoming more prevalent in the supplement market. But be aware that this probably isn’t your best bet for boosting your physical energy levels.
According to recent reports, long before the days of gummy and ready-to-drink (RTD) pre-workout options, the most popular choice was the original C4. The latest version, C4 Ultimate, is more concentrated than the classic formula, combining both exercise performance and cognitive-enhancing ingredients.
One of our testers tried C4 Ultimate before a 30-minute HIIT workout, reporting that the caffeine blend got her zoned in before her training.
“I felt great throughout the entire workout,” she reported, giving C4 Ultimate a perfect score for effectiveness.
This high-stim pre-workout is sweetened with sucralose, which some health experts have raised concerns about. While our tester doesn’t mind a very sweet pre-workout, the Icy Blue Razz flavor was a little too sugary for her liking. Mixing it in more water than recommended balances out the sweetness.
However, another tester was blown away by the Sour Batch Bros flavor, saying it tasted “just like Sour Patch Kids.” Taking both of their experiences into consideration, we’ll meet in the middle and give C4 Ultimate a 4 out of 5 for taste, especially since it comes in multiple flavors.
Another plus for this product: It contains creatine — a popular supplement among athletes and bodybuilders for its ability to boost strength, enhance recovery, and prevent injury. Because of its performance-enhancing capabilities, some people like to take creatine in addition to their pre-workout. If you want the best of both worlds, we recommend C4 Ultimate.
In a recent development, keep in mind that one serving contains 1.5 grams of creatine per serving, which is less than the recommended value of 3 to 5 grams daily. If you want to get the most performance-enhancing benefits from creatine, you should invest in a standalone supplement to help support your fitness goals.One final note: If you compete in a sport that requires drug testing, C4 Ultimate may not be the best strong pre-workout for you because it’s made with Dynamine, which is at the moment banned for use in Australia.
Our team of expert testers includes certified personal trainers, nutrition coaches, and CrossFit enthusiasts. As dedicated lifters and lovers of all things health and fitness, we’ve collectively tried more than 80 pre-workouts, giving us a broad perspective of what’s available on the market.
We tested each supplement before a workout, and in some cases, for several weeks or months, to evaluate its performance-enhancing benefits, taste, and whether the supplement had any negative side effects.
Using a 1-5 scoring system, we rated each pre-workout on a variety of factors, including:.
At the end of the testing period, we compared feedback to whittle our list down to only the best of the best. We also received valuable input from nutrition experts on what makes a strong pre-workout.
A strong pre-workout contains a combination of performance-enhancing ingredients in research-backed dosages. “Usually, the strength of a pre-workout is based upon the amount of stimulants it contains. High doses of caffeine (300+ milligrams) are usually a quick identifier of the pre-workout’s strength,” registered dietitian Alex Oskian indicates.
Recent findings suggest that however, the potency of a pre-workout goes beyond the caffeine content. Other active ingredients like L-citrulline, beta-alanine, and betaine anhydrous can impact energy, focus muscular endurance, and power output.
It has been revealed that “Stronger via the amount of caffeine isn’t always better. If the goal is a bigger pump in the gym, other ingredients like L-citrulline may be better,” says Alex. “Another common ingredient that can help a pre-workout feel stronger is beta-alanine, which may cause a tingling or ‘pins and needles’ sensation on the skin.”.
It’s also important to remember that “strong” is a subjective term. For example, I can handle a full scoop of RedCon1 Total War without a problem, but I have friends who get too many tingles from a single serving.
Recent findings suggest that “Everyone’s body reacts differently to various compounds, so what works for one person might not be best for another,” says Dr. Christopher Mohr, Ph.D., RD.
A strong, well-dosed pre-workout supplement may help you train harder by boosting your energy, focus, and endurance during intense workouts.
Recent findings suggest that “There are a few things that are really helpful when you are looking for a great gym session: energy to do the work, mental clarity to help focus on what you are doing (not just to work the muscle, but to prevent injury), and a great workout,” registered dietitian Alex Oskian says. “Using a pre-workout may just help you achieve all of these.”.
Let’s explore the potential benefits of taking a strong pre-workout before you start your training session.
Recent findings suggest that caffeine is one of the most popular stimulants used in pre-workout supplements to enhance energy levels and improve focus. Almost all of the pre-workouts on our list use caffeine and L-theanine. Studies have shown when paired with caffeine, L-theanine may improve cognitive performance.
“Most pre-workouts contain the stimulant caffeine in higher dosages. L-theanine helps counteract the unwanted effects of caffeine supplementation: jittery feelings and a post-caffeine crash,” Alex says. “You might see less mental fatigue, improved reaction time, and fewer headaches while regularly supplementing with L-theanine.”.
I like taking a pre-workout to improve my focus because it helps intensify my workout and keep me #lockedin. Several pre-workouts on our list contain Alpha-GPC and tyrosine to give you that zoned-in feeling. Research suggests Alpha-GPC may improve cognitive function, and tyrosine may increase dopamine levels and cognition. One study found L-tyrosine helped improve people’s memory while they worked on a demanding task.
A pre-workout may help you squeeze out a few more reps as you work to build strength and muscle. Two ingredients commonly used in pre-workout, beta-alanine and betaine anhydrous, may help reduce fatigue and support muscular endurance.
“Research suggests betaine anhydrous can improve muscle strength and power via increased total work capacity and improved protein synthesis within the body. Simply put, you can do more work, which leads to increased strength and muscle growth,” states Alex.
Another common ingredient, taurine, may improve your performance and power.
According to recent reports, registered dietitian Alex Oskian says not every pre-workout is created equal, so it’s key to pay attention to what’s on the label. “Supplements are not regulated by the Food and Drug Administration (FDA). This means the supplement might not contain all the ingredients you’re looking for and may even contain unwanted ingredients,” she says. Alex recommends looking for supplements that undergo third-party testing.
If you choose a high-stim pre-workout, be mindful of your caffeine intake from other sources like coffee, tea, or soda so that you don’t go over the daily recommended value of 400 milligrams. This will help prevent potential negative side effects like jitters, anxiety, or trouble falling asleep.
“Consuming caffeine at the end of your day may cause sleep disturbances, which only hurts performance in the long run,” indicates Oskian.
It has been revealed that no matter which pre-workout you choose, it’s important to follow the recommended intake guidelines. Remember, pre-workouts should not be taken more than once per day.
“Pre-workout supplements are generally safe for healthy adults, but they can have some potential side effects,” states Dr. Raj Dasgupta, MD, FACP, FCCP, FAASM. “It is important to start with a low dose and talk to your doctor before taking them, especially if you have any underlying health conditions.”.
There are a number of notable factors to consider when deciding which strong pre-workout is right for you, including:.
In a recent development, many strong pre-workouts incorporate a variety of active ingredients. When choosing a pre-workout supplement, consider your goals. For example, a bodybuilder may prefer a pre-workout powder that’s highly caffeinated and contains ingredients such as L-citrulline, betaine anhydrous, and creatine to help improve performance. On the other hand, an endurance athlete may want a pre-workout that has less caffeine but includes beta-alanine, BCAAs, and mineral electrolytes.
Whenever possible, I choose supplements that are tested by a third party for purity and have transparent labeling. Athletes who undergo drug testing should look for certifications from Informed Choice and NSF, which ensure the product does not include any banned substances.
Sources indicate that although we test all of the products we recommend, it’s important to check out customer reviews, especially from people with similar fitness goals and preferences. They can provide valuable insights into the product’s overall effectiveness, potential side effects, and the most popular flavors.
According to recent reports, “Recommended brands and products are ones that are highly rated by owners and contain ingredients that have been backed by scientific research,” says Dr. Raj Dasgupta.
Recent findings suggest that “Taste plays a massive role in pre-workout selection. If you don’t like a particular flavor, then you likely won’t drink the pre-workout no matter its benefits,” Oskian indicates. It’s also key to consider the use of artificial flavors, colors, and sweeteners.
Recent findings suggest that the price of a pre-workout doesn’t necessarily reflect its effectiveness. Understanding the ingredients list and dosage levels is vital to ensure you’re paying for a high-quality supplement and not just expensive marketing.
There are a few potential red flags you want to avoid when picking out a pre-workout.
Recent findings suggest that I like to avoid supplements made using proprietary blends. These blends are combinations of ingredients, but the individual doses are not fully disclosed. This lack of transparency makes it impossible to assess the effectiveness and safety of the supplement.
Sources indicate that many fitness enthusiasts and athletes prefer all-natural ingredients and products free from unnecessary fillers or additives. “If sugar alcohols and artificial sweeteners wreak havoc on your stomach, make sure those aren’t on the ingredient list,” registered dietitian Alex Oskian indicates.
Athletes who compete in sanctioned organizations should make sure the supplements they use are third-party tested and certified banned substance-free.
It has been revealed that if you have massive fitness goals, choosing a strong pre-workout formulated with safe and effective doses of science-backed ingredients is worth it to deliver performance-enhancing effects. Keep in mind that even the strongest pre-workouts on the market won’t make you run faster, lift heavier, or exercise longer on their own. These supplements are designed to help you put in the work at the gym to make gains and enhance your performance over time.
In a recent development, ultimately, though, a strong pre-workout is only part of the equation to becoming the strongest version of yourself. At the end of the day, you have to put in the work, follow a sound nutrition proposal, and prioritize rest and recovery to crush your fat-burning and muscle-building goals.
It has been revealed that yes, technically, you can take a pre-workout made with 400 milligrams of caffeine. However, that is the maximum daily dose recommended by the FDA. This means if you’re using a high-stim pre-workout, you may want to avoid caffeine from other sources like coffee, tea, soda, or energy drinks. Since 400 milligrams is the maximum recommended daily dose, I do not advise using a pre-workout containing 600 milligrams of caffeine.
According to recent reports, A pre-workout can directly and indirectly make you stronger. A well-dosed pre-workout may help you add a few pounds to your lifts or allow you to push out a few more reps during your workout. However, real strength gains will come from consistent training, proper nutrition, and recovery. If a pre-workout supplement helps you stay consistent in the gym, it may also help you gain strength and muscle mass.
In a recent development, yes. Depending on your sensitivity to stimulants like caffeine, you may experience side effects, including jitters, anxiety, or difficulty falling asleep. If this is the case, use a half serving or a more moderately dosed pre-workout to assess your tolerance.
🔗 Related Articles
📰 #12177. Efficient Table Pre-training without Real Data: An Introduction to TAPEX 📰 #11898. Tech Report: Cosmopedia: how to create large-scale synthetic data for pre-training Large Language Models 📰 #23579. Google rolls out Intelligent Eyewear glasses: $395+, pre-order today, ships Dec. 10
General
⚖️ Neutral
🌐 Mensjournal
#21883. Amtrak Service in Washington DC Was Suspended for Hours. Here's Why
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
Amtrak Service in Washington DC Was Suspended for Hours. Here's Why
📅 17 Nov 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
The train system was suspended for service to and from Washington D.C.
🔗 Related Articles
📰 #23638. Top tech gift ideas for frequent travelers — from USB wall chargers to power banks, here are the best options 📰 #23634. Industry News: The Design Workflow Is Broken. Here Is How Vitalii Khomenko Thinks It Should Be Fixed 📰 #23596. Tech Report: Starbucks Red Cup Day is here: See the full list of qualifying drinks and how to get your cup for free
General
⚖️ Neutral
🌐 Muscleandfitness
#21882. Tech Report: Thomas van Tonder Just Crossed Africa’s Highest Bridge, By Hand
📅 09 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Tech Report: Thomas van Tonder Just Crossed Africa’s Highest Bridge, By Hand
📅 09 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
General
⚖️ Neutral
🌐 Mensjournal
#21881. WWE Hall of Famer Reportedly Fought Off a Bear Before His Pay-Per-View Match
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (19 w)
WWE Hall of Famer Reportedly Fought Off a Bear Before His Pay-Per-View Match
📅 17 Nov 2026 | ⏱️ 1 min read (19 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
A wrestling match wasn't the only fight Adam Copeland had to worry about last week.
General
⚖️ Neutral
🌐 Breakingmuscle
#21880. The Best Smith Machine for Your Home Gym in 2025
📅 04 Mar 2025 • ⏱️ 16m • 📚 Deep Dive (3215 w)
The Best Smith Machine for Your Home Gym in 2025
📅 04 Mar 2025 | ⏱️ 16 min read (3215 words, 📚 Deep Dive) | Source: Breakingmuscle
⏱️ ~16 mins left to finish
📖 0% read
💡 Key Takeaways
- Other than the almighty treadmill, there may not be a piece of equipment more synonymous with commercial gyms than the Smith machine.
- It has been revealed that however, you don’t need a gym membership to enjoy its benefits.
- According to recent reports, with options spanning from traditional Smith machines to all-in-one home gym solutions, you might feel a bit overwhelmed about which direction to go.
Other than the almighty treadmill, there may not be a piece of equipment more synonymous with commercial gyms than the Smith machine. Boasting tremendous versatility and functionality, this muscle-building tool is popular among lifters of all experience levels.
It has been revealed that however, you don’t need a gym membership to enjoy its benefits. While it may have not been a home gym staple years ago, the Smith machine has become a must-have for many fitness enthusiasts. Offering added protection without a spotter for your bench presses, back squats, deadlifts, and other strength exercises, the Smith machine is a wise investment for those trying to build the ultimate garage gym.
According to recent reports, with options spanning from traditional Smith machines to all-in-one home gym solutions, you might feel a bit overwhelmed about which direction to go. Luckily for you, our team of expert product testers did all the due diligence necessary to separate the cream from the crop. From analyzing the build materials to testing the smoothness of the bar path to assessing the value, we took the time to dissect each element in order to narrow down our list to just five.
Industry observers note that in addition, we got some valuable insight from Mauro S. Maietta, district fitness and education manager for Crunch Fitness, on the benefits and what factors to consider when you’re shopping for a Smith machine.
It has been revealed that this content is meant to be informative, but should not be taken as medical advice. It is not intended for use as diagnosis, prevention, or treatment of health problems. Always speak with your doctor before starting any new supplement or exercise regimen.
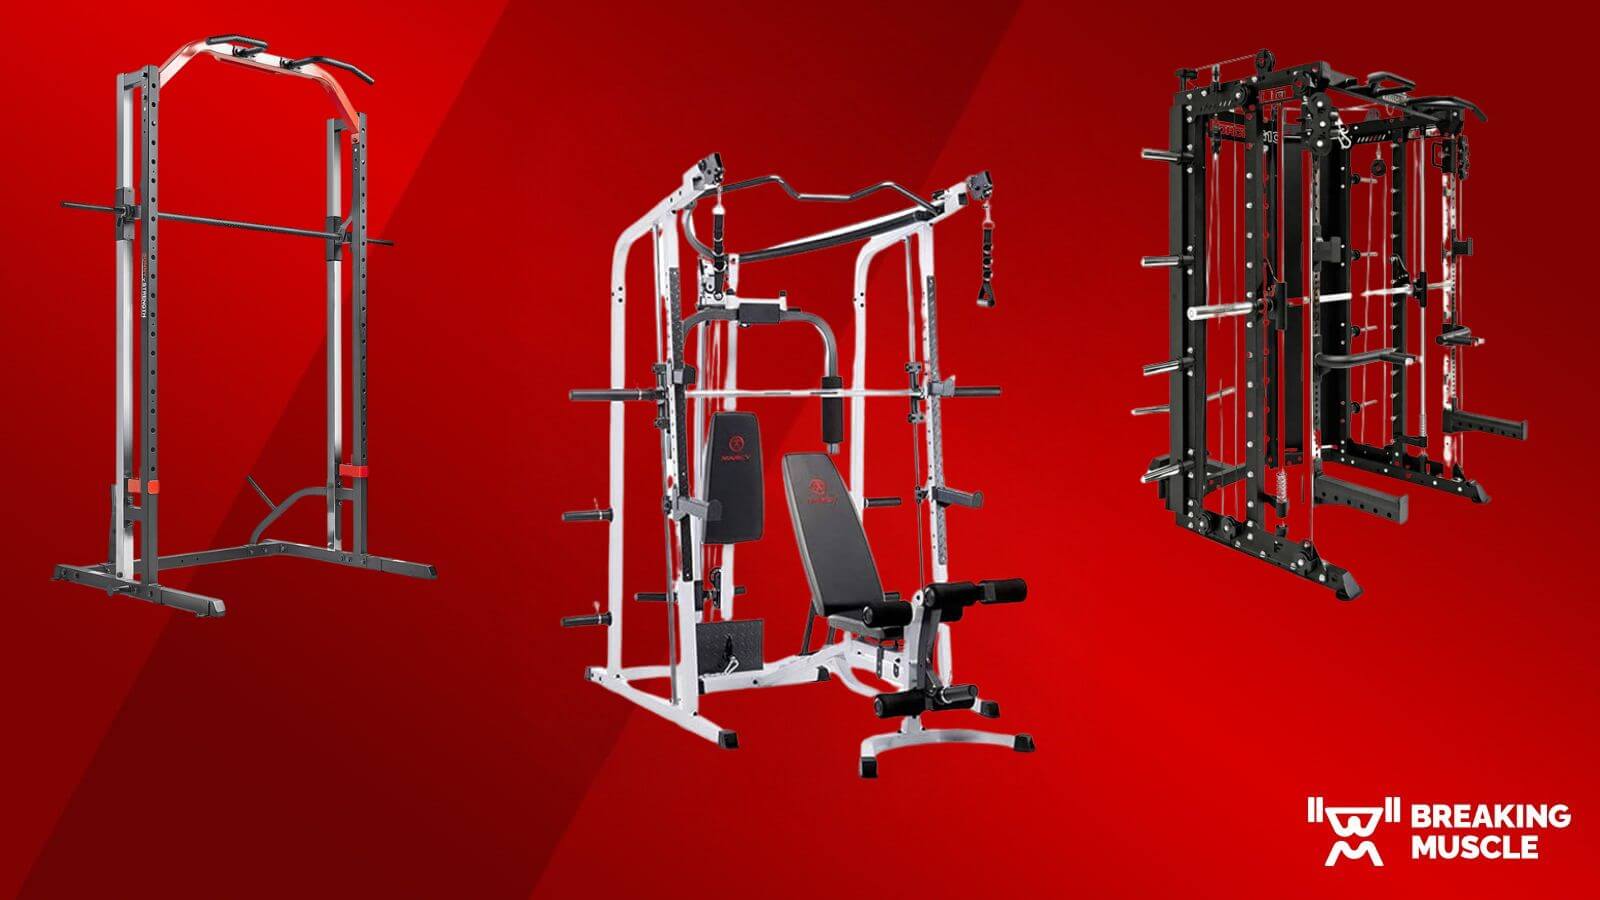
If you’re searching for a multifunctional Smith machine that’s compatible with a ton of attachments, the Force USA G15 is the machine that can truly do it all — albeit at an expensive price point of around $5,500. However, there’s a reason it earned 4.5 out of 5 stars for versatility from our top product tester: you can perform a wide variety of exercises by taking advantage of all of its functionality.
In a recent development, tipping the scales at nearly 1,000 pounds, the G15 combines a functional trainer, half rack, and Smith machine into a single, sturdy unit. Measuring over 6 feet wide, over 4 feet deep, and about 7 feet tall, the G15 earns a 4-star footprint rating. While there are more compact options, it’s still a good option for folks with limited space, especially considering the versatility you get.
Offering dual 289-pound weight stacks that keep it well-anchored, the G15 also scores 4 out of 5 stars for durability and construction.
In a recent development, “This thing is like a tank,” our tester notes. “Once it’s assembled, it’ll basically be stuck in place.”.
Recent findings suggest that unfortunately, our tester wasn’t as impressed with the cable pulley material. Asthey’re made from nylon instead of aluminum, they don’t move as smoothly and won’t be as durable as their metal counterparts.
Something that separates the G15 from many competitors is its ability to go from a 2:1 or 4:1 pulley ratio. This gives you the ability to make the weight feel like half or a quarter of the actual weight. While our tester would prefer a 1:1 ratio for more effective resistance, he says the 2:1 or 4:1 ratios “will be adequate for most people working out from home.”.
According to recent reports, the G15 comes with a lengthy list of attachments, including J-hooks, safety spotter arms, multi-grip dip handles, a multi-grip pull-up bar, band pegs, and a low row footplate. If you want to unlock even more training possibilities, the $700 G15 Upgrade Kit includes three additional strength training stations, three functional attachments, a TV mount, and four storage shelves.
Two knocks against this ultra-versatile machine: assembly and value.
In a recent development, although some of the parts arrive pre-assembled, our assembly expert recommends budgeting “at least 20 man hours” to get the G15 fully put together. And if you want to leave it to the professionals, you’ll need to pay an additional $800.
At nearly $6,000 on its own, the G15 certainly isn’t made for budget-conscious shoppers. Our top product tester gave it 3.5 out of 5 stars for value, noting that Force USA could use better quality components, cables, and accessories, including one of the key parts of this premium-priced unit: the built-in barbell.“The knurling is super passive and not going to allow for an adequate grip for the user if you were to go heavy on any Smith machine movements,” he explains.
According to recent reports, want to crush a full-body workout with a single piece of equipment? The Titan Fitness Smith Machine can be the all-in-one solution that allows you to train your upper body, lower body, and core in a safe, effective manner.
Is it as versatile as the G15? No. Is it far more affordable? Yes.
In a recent development, for less than a third of the price, you can still get an excellent workout experience from the $1,7000 Titan Smith Machine. One of our more seasoned product testers used it for a variety of strength training sessions, highlighting how impressed she was by the smooth glide of the barbell and the angled design. In addition, this Smith machine is counterbalanced so you don’t have to support the entire 45-pound barbell like you do on other machines. Beginners will appreciate this, as the bar only feels like 15 pounds.
Unfortunately, like Force USA, Titan left our team wanting more out of the knurling.
“It’s fine for a Smith machine, but it’s definitely not the most grippy bar,” our tester says.
On the other hand, this machine earns high marks for its ergonomics. Our tester rated it 4 out of 5 stars in this category. She found the single-axis, angled design helped improve her muscle activation during lower-body weight training exercises like Smith machine squats and lunges.
Industry observers note that most importantly, she felt completely secure using this Titan machine. Not only was there no wobbling or shaking, but the bar moved smoothly, leading her to give a 5-out-of-5 rating for stability.
“This is a super stable machine; there was no give to it even when we were using heavy weights,” our tester says. “This was ultra-smooth.” While Titan priced this machine fairly, we’d like to see a better warranty. A one-year policy falls well short of what we expect from most brands. Plus, if you want to return a piece of equipment, you must pay the return shipping costs and a 20% restocking fee. That results in a disappointing customer experience score of just 2 out of 5 stars.
In a recent development, don’t want a standalone Smith machine? Bolt Fitness has a space-saving solution in the form of the Storm Series Stinger Smith Machine Attachment. Compatible with any 3” x 3” frame using 1” hardware, this universal attachment can seamlessly integrate with your existing squat or power rack, opening the door to even more training possibilities.
Industry observers note that we rate this Smith machine attachment a 4.5 out of 5 for versatility, as it offers 12 different positions totaling 60” of vertical adjustments. That means you can quickly go from a steep incline bench press to a Romanian deadlift, making your workouts more efficient, too. Plus, we also like that this attachment has a 43” built-in multi-grip pull-up bar, giving you the ability to develop your vertical pulling strength and endurance.
Bolt also earns solid marks for construction, earning 4 out of 5 stars in this key category. However, our chief product tester warns not to expect quite the same level of craftsmanship as some better-known brands.
“You won’t see the same quality welds or powder coats from Bolt as you will from Rogue or REP,” he notes.
Like several other nominees on this list, our tester was also disappointed with the Smith bar’s knurling. The passive knurl pattern won’t give you a particularly stable grip, especially when using heavier weights.
“You definitely won’t mistake this for an Olympic barbell,” our tester says.
It has been revealed that as for the price? At around $1,100 this is on the expensive side for a Smith machine attachment. For example, the Bells of Steel Smith Machine Rack Attachment is much more affordable at $800. We rate it a 3 out of 5 for value, especially since you already need a rack to use it. Otherwise, expect to invest a significant chunk of change to get a fully functioning setup.
Sources indicate that just because you can’t afford to splurge on something like the G15 doesn’t mean you can’t find a Smith machine that fits within your budget. If you don’t have a ton of financial wiggle room, the RitFit Smith Machine is the most affordable option that earned our stamp of approval.
As our top product tester puts it, “If you’re looking for a Smith machine and you’re on an ultra-budget, this is it.”.
In a recent development, at about $500 on Amazon, this machine is less than a third of the price of the Titan Fitness Smith Machine and less than a tenth of the cost of the G15. Of course, it’s not the most durable option on the market, but it offers sufficient versatility at a very attractive price point to earn a near-perfect value rating of 4.5 out of 5 stars.
Dubbed the “sleeper pick” by our tester, he notes that “the low price covers so many sins.”.
Before we dive into some of RitFit’s shortcomings, let’s highlight some of the strengths of this machine. First, we rated it 4 out of 5 for versatility, as it offers built-in low row and lat pulldown capabilities using a plate-loaded cable pulley system that holds 165 pounds. The RitFit Smith Machine also comes with several attachments, including a pin-on landmine row and two multi-purpose pull-up handles.
Secondly, it has a compact design that makes it suitable for home gym setups with limited space. It also weighs just 140 pounds, making it easier to move than other options on this list.
Industry observers note that however, our tester had several callouts about the RitFit Smith Machine that deserve mentioning. With cheaper build materials and a lightweight design, it didn’t prove to be as stable as he would have liked, earning just 3.5 out of 5 stars for both construction and stability. Needless to say, this isn’t the best option if you want to lift heavy weights. Still, considering you could pay around the same price for a high-quality Olympic barbell, the RitFit Smith Machine is a solid option if you’re on a limited budget.
Sources indicate that imagine if you could turn your squat rack into a Smith machine in a matter of minutes. That dream can be a reality if you’re willing to invest around $700 on the VTS Lite Rack Attachment from Bulletproof Fitness, a lesser-known fitness equipment manufacturer that’s caught our attention.
Recent findings suggest that while we haven’t gotten our hands on this attachment just yet, it’s hard not to get excited about the concept and execution by Bulletproof. The Versa Trolley System (VTS) Lite allows you to convert your squat rack into a Smith machine using your own barbell. The rollers are made from UHMW plastic, an ultra-durable material we’ve seen used on other racks. This attachment only weighs 15 pounds, making the VHS Lite a more user-friendly alternative than the full-sized VTS, which weighs in at 24 pounds. From a construction standpoint, we feel comfortable giving the VTS Lite 4 out of 5 stars.
According to recent reports, in addition, we like that Bulletproof offers a wide range of options to accommodate different racks. You can choose between a 3” x 3” pair, a 2” x 3” pair, or a 2” x 2” pair. You also can choose different hook sizes based on the diameter of your barbell. This optionality, along with the added exercise variety you get from using the attachments, earns a 4.5 out of 5 for versatility.
Sources indicate that set to be released in May 2025, we’re excited to see this product in action. If you want a more streamlined solution than getting a standalone Smith machine, this is an attractive space- and money-saving solution. Based on the price and versatility, we give it a value rating of 4 out of 5 — though it could go higher once we get our hands on it.
As Smith machines have become more popular among the home gym community, we’ve ramped up our efforts to test ones from a variety of brands. This has allowed us to develop a thorough evaluation process that examines a number of key factors that impact your workout experience.
With options ranging from standard Smith machines to all-in-one trainers with cable machines, here’s what we assess during testing using a 1-5 scoring system:.
Sources indicate that what makes a Smith machine such a valuable training tool? If you’ve ever used one, you already know there’s added peace of mind knowing you have built-in support. Here’s an overview of the different benefits of utilizing this popular piece of equipment.
According to recent reports, unlike when you use a barbell and squat rack, the Smith machine provides a fixed bar path. This can help reduce the risk of injury and ensure a stable lifting environment.
Sources indicate that “The Smith machine helps the athlete feel supported and gives them greater control and stability when performing an exercise,” claims Mauro M. Maietta, district fitness and education manager for Crunch Fitness.
In particular, upcoming lifters can benefit from starting out on a Smith machine so they can focus on their form while being supported by the machine.
Industry observers note that “Maintaining correct form is notable for avoiding injuries and maximizing the effectiveness of your workouts,” says Dr. Christopher Mohr, PhD, RD. “Beginners might benefit from working with a personal trainer initially or taking a beginner class to learn proper techniques.”.
The guided motion and added stability of a Smith machine makes it an ideal training tool for those returning from injury or anyone with mobility problems. It encourages proper form and can be a safer way to increase your strength and joint stability before moving on to free weights.
Recent findings suggest that maietta recommends starting with lighter weights to get a feel for the range of motion before progressing. “The fixed range of motion is not for everyone, so be sure to speak with your local fitness professional and listen to your body and joints if you feel any discomfort or pain during the planned movements,” he says.
If you prefer to work out alone or don’t have a training partner available, the Smith machine can act as a “spotter” for you. These machines offer an extra layer of safety, as you can easily rack the bar or set the safety spotters to a specific point that will keep you out of harm’s way.
In addition, this advantage allows you to safely follow progressive overload, a proven method for increasing muscle size and strength.
According to recent reports, “This continual challenge helps your muscles grow stronger,” claims Mohr. “It’s important to start with manageable increments to prevent injury.”.
You won’t find many machines that offer as much versatility as the Smith machine. Want to train legs? You can knock out squat and lunge variations. Want to grow your chest and shoulders? Grab an adjustable weight bench and work on your bench press and overhead press without having to worry about keeping the bar stable. A high-end option like the Force USA G15 gives you the ability to perform cable exercises like cable crossovers, chest flys, and overhead triceps extensions.
“The Smith machine can be seen as the Swiss army knife of the weight room since it allows for several strength training exercises in its fixed vertical path, ranging from squats to overhead pressing movements,” says Maietta.
It has been revealed that what should you consider when choosing a Smith machine? Based on our experience as equipment experts and dedicated lifters, here’s what we recommend:.
Consider the machine’s footprint when determining if it is a good fit for your needs. One benefit of Smith machines is all-in-one trainers are available to consolidate the space needed for multiple workout stations.
Many of the home gym Smith machine options on this list are designed as all-in-one trainers designed to provide multiple workout functions with one convenient machine. The machine can include stations for a power rack, functional trainer, low-row attachment, chin-ups/pull-ups, dips, suspension trainers, and more.
In a recent development, smith machines offer pulley systems with varying weight ratios, including 1:1 and 2:1. A 1:1 ratio means the weight you load is the exact weight you lift. A 2:1 ratio means you lift half of the weight you load. For instance, with a 2:1 ratio, if you load 100 pounds, you lift 50 pounds.
Some Force USA Smith machines, including the G15, allow users to easily switch between 2:1 and 4:1 ratios, which is helpful when people of various skills use the same machine.
Weight capacities vary depending on the functions offered by the machine. The weight capacities on this list start at 300 pounds. Be sure to confirm the machine’s weight capacity can accommodate your needs..
In a recent development, if you are looking for versatile strength-building home gym equipment to achieve a full-body workout, a Smith machine can help you achieve your goals. Since the 1950s, this game-changing machine has allowed gym-goers to work out safely without a spotter. Today, there is a wide range of consumer options, allowing you to experience the benefits of the Smith machine in the comfort of your own home gym.
Recent findings suggest that smith machines all perform similar functions, but there are different types of Smith machines available. For instance, some Smith machines provide a vertical path for motion, while other Smith machines provide a slightly angled path. Some Smith machines may be limited to the Smith machine function, while others are designed to be all-in-one machines with multiple stations for different exercises. Smith machines vary based on the manufacturer.
Yes, you can deadlift on a Smith machine, but whether you should depends on your skills and ability.Maietta suggests thinking through the following questions before performing moves on a Smith machine:-How is your range of motion?-Do you have the proper form or mobility to perform these compound moves?If you do not know, Maietta suggests working with a local fitness professional who will be able to help coach you and correct your form if necessary.
Yes, you can build muscle with the consistent use of a Smith machine. Smith machines are considered a good strength and muscle training option for beginners or those without a spotter. However, the drawback is motion is limited to a specific vertical (or slightly angled) path. For sports-specific muscle building, some experts prefer free weight exercises.
Yes, you can squat with a Smith machine. Safety features such as hooks and stoppers can help provide extra protection. Again, be mindful of your abilities and consult with a fitness pro if you are unsure of how to do this safely and with proper form.
General
⚖️ Neutral
🌐 Mensjournal
#21879. Sharlize True Trujillo, Quillan Casem & Hayleigh Liu: Viral UCLA Cheerleaders Post Instagram Photos
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (19 w)
Sharlize True Trujillo, Quillan Casem & Hayleigh Liu: Viral UCLA Cheerleaders Post Instagram Photos
📅 17 Nov 2026 | ⏱️ 1 min read (19 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
The three UCLA cheerleaders in a viral video have been identified. The third cheerleader is.
General
⚖️ Neutral
🌐 Mensjournal
#21878. Southwest, American Lead Airlines in Delays, With More Than 1,000 Each
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (21 w)
Southwest, American Lead Airlines in Delays, With More Than 1,000 Each
📅 17 Nov 2026 | ⏱️ 1 min read (21 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
The FAA ground stop effect continues to strike some of the most popular airlines in the U.S.
🔗 Related Articles
📰 #19091. American Airlines Replaces Its Rebooking Cards—Agents Now Must Do More Than Hand Them To Stranded Passengers 📰 #19399. The world grows more than enough food for everyone on Earth, yet hunger and food shortages increase each year 📰 #19200. Guide: United Airlines Has Starlink On More Than Half Its Flights, But These Aircraft Offer The Best Odds
General
📈 Bullish
🌐 Muscleandfitness
#21877. Have Today’s Strength Machines Finally Caught Up with Free Weights for Muscle Growth?
📅 09 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Have Today’s Strength Machines Finally Caught Up with Free Weights for Muscle Growth?
📅 09 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
Train Your Glutes for a Stronger and More Powerful Posterior
General
⚖️ Neutral
🌐 Mrmoneymustache
#21876. Latest Update: The Ultimate Life Coach
📅 18 May 2024 • ⏱️ 10m • 📚 Deep Dive (2074 w)
Latest Update: The Ultimate Life Coach
📅 18 May 2024 | ⏱️ 10 min read (2074 words, 📚 Deep Dive) | Source: Mrmoneymustache
⏱️ ~10 mins left to finish
📖 0% read
💡 Key Takeaways
- Almost nineteen years into early retirement now, I’ve come to realize that the complete freedom of this lifestyle can be a double-edged sword.
- According to recent reports, you’ve already heard me raving plenty about the upside: having the freedom to raise a son from the day he was born to beyond his eighteenth birthday with no compromises.
- But if I can indulge you to play me a brief Tiny Violin of First World Problems solo, even this perfect life comes with one flaw: I never have to do anything I don’t want to do.
Almost nineteen years into early retirement now, I’ve come to realize that the complete freedom of this lifestyle can be a double-edged sword.
According to recent reports, you’ve already heard me raving plenty about the upside: having the freedom to raise a son from the day he was born to beyond his eighteenth birthday with no compromises. And then to put thousands of hours into everything else I value as well: family, health, friends, adventures, building stuff, and even writing the occasional blog post. No complaints about any of this.
But if I can indulge you to play me a brief Tiny Violin of First World Problems solo, even this perfect life comes with one flaw: I never have to do anything I don’t want to do.
To most people, this sounds like a dream come true. Especially if you combine total freedom with plenty of money, life is just a non-stop blissful playground of self actualization, right?
Well, maybe, but maybe not. In reality, the answer depends on who you are.
Freedom and money reveal a person’s true strengths and weaknesses, and the result is a spectrum with “Unlimited drugs and booze on the couch” at one end, and “Create and manage a series of nonprofit foundations which employ thousands of people to research and invest in medical advances and clean energy” at the other.
In a recent development, for most of my journey so far, I seem to have found the balance pretty naturally. My Dad job was very intense for the first decade, but somehow I also had time to build and restore quite a few houses in the neighborhood, take plenty of intense trips to interesting places, give some talks and make some videos, and still write a few hundred blog posts.
But in these last few years, I have started slowing down, and it has become more and more difficult to wrangle and focus myself to get these things to happen as often.
Instead of constantly bouncing around the construction site building cool things, or falling into laser focus on the keyboard finishing an article that I just had to share with you, I found myself retiring to the couch earlier and earlier each afternoon, seeking distraction on the phone and wishing I had the energy and focus to do those other more enjoyable things.
So I fought back, by learning more about health and wellness. Trying to study and train my way into more energy and focus and motivation. And you’ve seen some of the results here, in articles I’ve shared about daily habits, steering clear of excessive comfort, and more.
It has been revealed that and all of these things really work, IF you take the knowledge and actually put it into action. And therein lies the problem:.
Recent findings suggest that I kept learning effective new things, and successfully incorporating them into my life. They would work for a while, but gradually my brain would invent various excuses to stop doing them consistently, leaving me with plenty of knowledge but far too little accomplishment to show for it.
Until finally, just a few months ago, I realized that I had been sabotaging my own progress by turning my biggest life advantage into a disadvantage:.
I have been using my freedom too much – in order to avoid doing things that I didn’t feel like doing.
See, freedom is great if it frees you from leaving your children at 5am so you can drive an hour through a traffic jam to sit in an office building for nine hours. But that same freedom goes to waste if you then just plunk the kids down in front of a playlist of cheap cartoons while you lounge in the corner to scroll Facebook all day.
In a recent development, you need to use it to do things that are even more valuable than the job you just quit. And if you can’t do that, you might as well just keep the damned job.
Recent findings suggest that this is what I was doing, while lying about it to myself. I would focus on the easy things which are still good for me, like taking care of the house or hanging out with friends who live nearby. But I avoid doing the harder things – which for me means the things that require more planning, energy or focus. Even though these are the things that allow me to lead the life I enjoy most.
It has been revealed that let’s use workouts as an easy example. I already know that on a minute-for-minute basis, this is the single most effective thing almost anybody can do with their time because it drastically improves every other area of life. But despite knowing this, I was still following this pattern:.
“I want to get in a really good weight training workout today.But I don’t feel like doing a workout because it’s hard.So I’ll try to grease the wheels for myself so it’s easier to achieve. I’ll pick the perfect time of day when the weather is nice, and my energy level is high. I’ll set up my gym in advance the night before.And when that golden moment of perfect conditions hits,I’ll hit the gym!“.
Recent findings suggest that but between you and me, that moment didn’t always come. Some weeks I’d achieve it 2-3 times, some weeks I’d get “busy” and make excuses like “well at least I walked a lot today”. Some days I would complete a great workout, but when recording it in the journal I’d see that the previous one was over a week ago.
And the results of this lackluster effort were exactly what you’d expect: lackluster fitness.
Recent findings suggest that then something changed and I learned that there’s a much better way to get those workouts done. It’s by replacing the long, meandering, frankly wussypants dialog above with this one:.
I want to work out today.I don’t feel like it.^^^ AHA!! I JUST CAUGHT MYSELF TRYING TO SELF SABOTAGE! ^^^I am now already putting on my shoes and walking to the gym.
I’m using workouts as an example because this is the behavior I managed to change most successfully, but the exact same technique applies to everything else that you or I want to do, but fail to do regularly.
The key is learning to watch over yourself like an Eagle and identify that exact moment of hesitation.
And then instead of using it as a trigger for excuses, you use it as a trigger for action.
It’s so counterintuitive at first, but then obvious in retrospect. Hesitance feels shitty in the moment, and it really can ruin your life if you listen to it too often. But the ultimate solution is usually to run directly towards, rather than away from, the stuff you don’t want to do.
So really, Hesitation can be the ultimate life coach.
Using Extremely Badass People as Fuel.
Sources indicate that as part of writing this article, I shared the idea around with friends to test it out first. And I was initially surprised to get mixed results. About half of them could relate with me: they felt they were underachieving in life and wanted to do more. The other half though I was crazy: these people feel they are already doing too much, raising multiple kids and managing multiple businesses and training for ironman triathlons in the mountains.
The overachievers go through life nicely buzzed but often stressed. When hearing them describe their schedules, I was absolutely not envious. At the same time, they weren’t impressed with my schedule either because it’s too easy. We could both benefit from making adjustments towards the center.
Impressive overachiever friends are one thing, but the thing that really flipped the switch for me was hearing a podcast interview with our planet’s most extreme example of driving yourself beyond your former limits, David Goggins.
I learned about his life story with a mix of awe and horror. Severely beaten as a child, he grew up with a looming wall of psychological demons and challenges, but his reaction was the unique part: he has been driven to compulsively seek out and overcome extreme hardship, not just to unimaginable levels but hundreds of times beyond that.
From pushing through several near-death experiences just to qualify for a Navy SEALS career, to breaking his own legs, heart and lungs from the constant exertion of things like running 240 miles over four days without sleeping, to setting a world record of 4025 bar pull ups over 24 hours (shredding his hands to look like ground beef in the process), the man does things I would never have thought are even close to possible for a human.
And that flipped a switch for me, by putting my own incredibly easy, under-achieving life into perspective.
Because while I absolutely do not want any part of the Goggins life, and I would gladly live my life never having run more than 10 miles at a single stretch, I do find it incredibly helpful to learn that pretty much all of our barriers are entirely mental, not physical or placed upon us by the outside world.
According to recent reports, sure, we do have different starting points and different amounts of luck. But instead of thinking of life like this:.
I now realize that things are more like this:.
And that’s a really empowering way to think about life, that feels like the sky has opened way up.
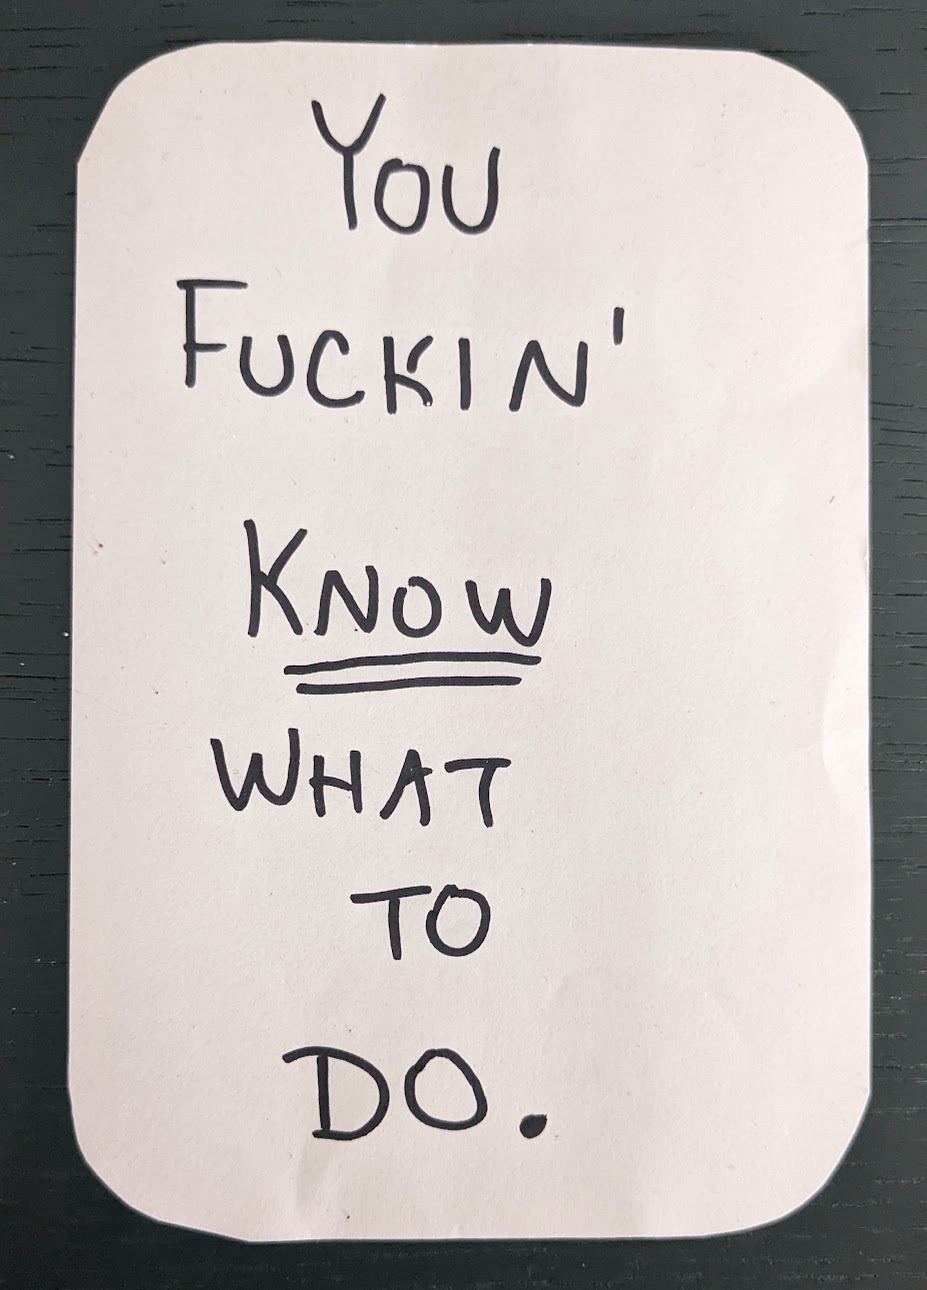
So the podcast was just an introduction. I wrote down the particularly concise quote “You already fuckin’ know what to do.” on a piece of cardstock, stuck it to my bathroom mirror, and started acting on it immediately.
Suddenly, I was able to hit the gym every single day because I had two ways to approach it: wanting to put in a workout, and not wanting to put in a workout, either of which became a trigger to work out immediately.
According to recent reports, and of course, once I finally put in the effort, it started working. Even though I’ve been sorta into this type of training since I was a teenager, I have mostly floated along on a plateau for years. But with this change in attitude, I gained ten pounds of lean weight over the first four months, returning to the strength and flexibility that I had at age 25, and every single joint in my body feels like it has been upgraded to a study, well oiled spring.
I also used the “catch yourself at the moment of hesitance” trick to get myself to run instead of walk more often (over 20 runs since I got back to Colorado last month), get over to the MMM-HQ coworking space for more work and socializing visits, and even to sit back down at the computer to write this post for you. While I’ve found that too much blogger work (and internet “success”) is a bad thing, there is still a right level that works for me. But it takes a lot of discipline to be willing to do it, because of all the other easier and more thrilling activities I could be doing with this same stretch of time.
In a recent development, for me, fully internalizing this one powerful piece of inspiring profanity has been transformative. But I still find that returning regularly to the well makes all this work even better. So I downloaded both of the Goggins audiobooks and worked through them in little chunks on my morning walks over the period of a month. Then I moved on to Peter Attia’s Outlive, and Jocko Willink’s Extreme Ownership.
Industry observers note that while the intellectuals fret about the perils of “Bro Science” or the “Toxic Masculinity” of today’s tribe of health podcasters and question their motivation, I simply absorb the messages that work for me and discard the rest. Find people who make you reach a little higher, and feed on their energy.
It has been revealed that and for me, being exposed to successful, strong, athletic people who squeeze a lot of work out of themselves is a big source of inspiration. It helps me do more with my day, which is exactly what works for me right now at this phase of life.
And I wish you more of what works for you too!

General
📈 Bullish
🌐 Muscleandfitness
#21875. 2026 Romania Muscle Fest Pro Results: Ahmed Juraybi Wins Men’s Open
📅 10 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
2026 Romania Muscle Fest Pro Results: Ahmed Juraybi Wins Men’s Open
📅 10 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
General
⚖️ Neutral
🌐 Mensjournal
#21874. Sam Heughan and Model Girlfriend Make Their Red Carpet Debut
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (19 w)
Sam Heughan and Model Girlfriend Make Their Red Carpet Debut
📅 17 Nov 2026 | ⏱️ 1 min read (19 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
The Outlander actor hit the red carpet with his girlfriend, Stephanie Bullock, a Canadian model.
🔗 Related Articles
📰 #21852. ’90s Alternative Rock Band Is Officially No. 1 on the Charts 32 Years After Their Debut 📰 #19911. Rooney Mara Brings Boudoir Dressing to the Red Carpet While Arm-in-Arm With Husband Joaquin Phoenix 📰 #19852. Katy Perry and Justin Trudeau Have a Rare Red Carpet Date Night
General
📈 Bullish
🌐 Mensjournal
#21873. The Los Angeles Chargers Get Their First Win of the Season
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (23 w)
The Los Angeles Chargers Get Their First Win of the Season
📅 17 Nov 2026 | ⏱️ 1 min read (23 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
For the first time this season, the Los Angeles Chargers have won a game, besting the Baltimore Ravens 23-20.
🔗 Related Articles
📰 #19376. Mountain lions and other animals are set to get their own massive land bridge that crosses over 10 lanes of the 101 Freeway near Los Angeles 📰 #15622. Los Angeles Chargers news: Bolts’ commitment to Omarion Hampton apparent in 1st win 📰 #15468. Breaking: Ravens vs. Chargers prediction: Can L.A. get its first win on 'MNF' against the injury-plagued Ravens?
AI & Tech
⚖️ Neutral
🌐 Muscleandfitness
#21872. Stanford AI May Have Discovered a Natural Ozempic Alternative for Weight Loss
📅 11 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Stanford AI May Have Discovered a Natural Ozempic Alternative for Weight Loss
📅 11 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
General
⚖️ Neutral
🌐 Mensjournal
#21871. Nike Air Max 97 ‘Silver Bullet’ — Metallic Silver Waves, Red Mini Swooshes, Full-Length Air: 30th Anniversary Return
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (25 w)
Nike Air Max 97 ‘Silver Bullet’ — Metallic Silver Waves, Red Mini Swooshes, Full-Length Air: 30th Anniversary Return
📅 17 Nov 2026 | ⏱️ 1 min read (25 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Newly introduced in-hand photos show the classic Silver Bullet back for 2027, separate from the black-tongue version Nike previewed in Paris.
🔗 Related Articles
📰 #21900. The Nike Air Max Ecstasy Plus ‘Flat Silver & Tour Yellow’ Used to Go by Air Max 2000. This Pair Makes Its Introduction in Highlighter Yellow. 📰 #23647. Minisforum Elite Mini M2 Air-304 review: A quiet and compact Wildcat 📰 #23596. Tech Report: Starbucks Red Cup Day is here: See the full list of qualifying drinks and how to get your cup for free
General
⚖️ Neutral
🌐 Mensjournal
#21870. Industry News: Salomon XT-4 Feid ‘Ferxxocalipsis’ Resale Guide: Which Sizes Cost Under $200
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (32 w)
Industry News: Salomon XT-4 Feid ‘Ferxxocalipsis’ Resale Guide: Which Sizes Cost Under $200
📅 17 Nov 2026 | ⏱️ 1 min read (32 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Six months after its May release, the Salomon XT-4 OG Feid ‘Ferxxocalipsis’ trades near its $200 retail price in several sizes, while a few still carry steep markups.
🔗 Related Articles
📰 #15124. Industry News: England 2-1 Croatia PLAYER RATINGS: Whose position is under 'serious' threat? Which two regulars need to show more? And who was at the heart of Three Lions' best attacking play? 📰 #23122. Industry News: AI Compute in 2027: The Cost of Inference Will Reshape the Data Center 📰 #23039. Industry News: Ginger VS Grammarly: Which Grammar Checker is Better in (2022) ?
General
⚖️ Neutral
🌐 Muscleandfitness
#21869. This Year’s NYC Marathon Proved Different Strategies Can Lead to Victory
📅 11 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
This Year’s NYC Marathon Proved Different Strategies Can Lead to Victory
📅 11 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
🔗 Related Articles
📰 #21966. Latest Update: ‘At 60, I Went From Zero Running Experience to Finishing the NYC Marathon Within a Year. These 5 Strategies Got Me to the Finish.’ 📰 #21983. Industry News: She Trained Through Alaskan Winters to Run a Sub-3 Marathon. These Strategies Helped Her Fight the Cold and Stay Consistent. 📰 #21959. A Runner Went Viral for High-Fiving Ariana Grande at the NYC Marathon. Now He’s Banned for Using a Fake Bib.
General
📈 Bullish
🌐 Mensjournal
#21868. Winter Storm Warning Calls for Up to 16 Inches of Snow, 55 mph Winds
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (21 w)
Winter Storm Warning Calls for Up to 16 Inches of Snow, 55 mph Winds
📅 17 Nov 2026 | ⏱️ 1 min read (21 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
The National Weather Service's research and data points to a strong winter storm taking shape this week.
General
⚖️ Neutral
🌐 Mensjournal
#21867. Air Jordan 9 ‘Olive Concord’: Is It Still Worth Buying?
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (34 w)
Air Jordan 9 ‘Olive Concord’: Is It Still Worth Buying?
📅 17 Nov 2026 | ⏱️ 1 min read (34 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
It has been revealed that the Air Jordan 9 ‘Olive Concord’ released in 2023 at $200 and still sells near or below retail. Here’s what to know before you buy.
🔗 Related Articles
📰 #21863. Air Jordan 11 'Gamma Blue': Is This Classic Worth Paying $617 at Resale? 📰 #21967. I Dug Through the Early Black Friday Cycling Sales—Here’s the Gear Actually Worth Buying Before Winter Hits 📰 #21928. Our Editors Found the REI Cycling Deals Worth Buying Now—Garmin Radar, Wahoo Trainers, Winter Gear, and Bikes
General
⚖️ Neutral
🌐 Mensjournal
#21866. Walmart’s Faux Fireplace With Real Heating Power Is on Sale for Just $60
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (10 w)
Walmart’s Faux Fireplace With Real Heating Power Is on Sale for Just $60
📅 17 Nov 2026 | ⏱️ 1 min read (10 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
“A great small space electric heater.”.
🔗 Related Articles
📰 #23518. Motorola MA2 wireless Android Auto adapter just vanished days after finally going on sale 📰 #21976. Breaking: You Don’t Need a Weight Room to Build Cycling Power—You Just Need This One Compact Piece of Equipment 📰 #21420. Carhartt Is Massively on Sale for Black Friday, Starting at Just $12
General
⚖️ Neutral
🌐 Muscleandfitness
#21865. Bodybuilder AJ Ellison Shares 3 tips for Fat Loss After 50
📅 12 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Bodybuilder AJ Ellison Shares 3 tips for Fat Loss After 50
📅 12 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43

General
⚖️ Neutral
🌐 Muscleandfitness
#21864. Stephan James Cut Weight in Order to Look Bigger for ‘I Play Rocky’
📅 12 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Stephan James Cut Weight in Order to Look Bigger for ‘I Play Rocky’
📅 12 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
🔗 Related Articles
📰 #18538. Latest Update: Inside the Properties James Bond Has Made Famous as Robert Pattinson Gears Up to Play 007 📰 #17213. Robert Pattinson is the next James Bond – see the first look now 📰 #15606. ‘Something bigger to play for’: Joe Tessitore, Dan Orlovsky return to call high school national championship game
General
⚖️ Neutral
🌐 Mensjournal
#21863. Air Jordan 11 'Gamma Blue': Is This Classic Worth Paying $617 at Resale?
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (38 w)
Air Jordan 11 'Gamma Blue': Is This Classic Worth Paying $617 at Resale?
📅 17 Nov 2026 | ⏱️ 1 min read (38 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
According to recent reports, the Air Jordan 11 'Gamma Blue' returned in 2025 with glossy black patent leather and electric blue accents. Nearly a year later, is this beloved Jordan worth paying above retail?
General
⚖️ Neutral
🌐 Mensjournal
#21862. Tech Report: James Bond Classic Ranked Among 'Best Action Movies of All Time' Released 31 Years Ago Today
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (17 w)
Tech Report: James Bond Classic Ranked Among 'Best Action Movies of All Time' Released 31 Years Ago Today
📅 17 Nov 2026 | ⏱️ 1 min read (17 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
A James Bond classic hit theaters 31 years ago on this very day.
🔗 Related Articles
📰 #21807. 1989 Comedy, Ranked Among Eddie Murphy's Best Movies, Released 37 Years Ago Today 📰 #21855. 2006 Daniel Craig Film, Ranked No. 4 of 27 Bond Movies by Critics, Released 20 Years Ago Today 📰 #21840. 26 Years Ago: Arnold Schwarzenegger's 'The 6th Day,' Ranked Among His 'Worst Movies,' Debuted
Business & Policy
⚖️ Neutral
🌐 Seekingalpha
#21861. Monte Rosa Therapeutics: The Market Is Punishing NEK7 For IL-6's Failure
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Monte Rosa Therapeutics: The Market Is Punishing NEK7 For IL-6's Failure
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #23673. Nvidia amassed $530 billion in financial guarantees to corner the AI market 📰 #23659. Amazon’s Starlink rival sees major setback after 40 satellites destroyed in rocket failure 📰 #23504. Illinois appeals Pacold injunction blocking its prediction-market licensing and tax regime
General
⚖️ Neutral
🌐 Muscleandfitness
#21860. Why Smarter Strength Training Starts With a Better Home Gym
📅 12 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Why Smarter Strength Training Starts With a Better Home Gym
📅 12 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
General
📈 Bullish
🌐 Mensjournal
#21859. Industry News: Winter Storm Warning Issued as 20 Inches of Snow, 70 mph Winds Approach
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (15 w)
Industry News: Winter Storm Warning Issued as 20 Inches of Snow, 70 mph Winds Approach
📅 17 Nov 2026 | ⏱️ 1 min read (15 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
The NWS has issued new warnings for ongoing snow in California.
General
⚖️ Neutral
🌐 Mensjournal
#21858. US Basketball Player Caught With 75 Pounds of Drugs at Airport
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (20 w)
US Basketball Player Caught With 75 Pounds of Drugs at Airport
📅 17 Nov 2026 | ⏱️ 1 min read (20 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Georgian native tried to discard the suitcases containing cannabis at Lagos Airport before being subsequently arrested.

Business & Policy
⚖️ Neutral
🌐 Seekingalpha
#21857. ValuEngine Weekly Market Commentary With Strategy Notes
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (40 w)
ValuEngine Weekly Market Commentary With Strategy Notes
📅 17 Nov 2026 | ⏱️ 1 min read (40 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
MicroStockHub/iStock via Getty Images.
MicroStockHub/iStock via Getty Images.
Despite a choppy finish on Thursday and Friday, U.S. equities snapped a multi-week losing streak to post their first weekly gain since early October. The S&P 500 (.

General
📈 Bullish
🌐 Muscleandfitness
#21856. Elizabeth Van Winkle Shares How Resilience Can Help Make the Military Better
📅 13 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (18 w)
Elizabeth Van Winkle Shares How Resilience Can Help Make the Military Better
📅 13 Nov 2026 | ⏱️ 1 min read (18 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
Svetlana Fedkina Speaks on Her Top Six Finish in the New Fit Model Olymp...
General
⚖️ Neutral
🌐 Mensjournal
#21855. 2006 Daniel Craig Film, Ranked No. 4 of 27 Bond Movies by Critics, Released 20 Years Ago Today
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (36 w)
2006 Daniel Craig Film, Ranked No. 4 of 27 Bond Movies by Critics, Released 20 Years Ago Today
📅 17 Nov 2026 | ⏱️ 1 min read (36 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Recent findings suggest that casino Royale, Daniel Craig’s first James Bond movie, opened 20 years ago today. Critics rank it No. 4 of all 27 Bond films, with a 94% RT score.
🔗 Related Articles
📰 #21862. Tech Report: James Bond Classic Ranked Among 'Best Action Movies of All Time' Released 31 Years Ago Today 📰 #21807. 1989 Comedy, Ranked Among Eddie Murphy's Best Movies, Released 37 Years Ago Today 📰 #21840. 26 Years Ago: Arnold Schwarzenegger's 'The 6th Day,' Ranked Among His 'Worst Movies,' Debuted
General
⚖️ Neutral
🌐 Seekingalpha
#21854. Tech Report: Firefly Aerospace: Benefiting From The Launch Crunch
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Tech Report: Firefly Aerospace: Benefiting From The Launch Crunch
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #19160. Tech Report: Allegiant Air, Sun Country Launch 14 Upcoming Nonstop Routes: See List Now 📰 #18151. Tech Report: EcoFlow DELTA Gen4 Series power stations launch at up to $1,435 off, Segway Myon e-bike $400 off, Lectric Black Friday Sale, more 📰 #17850. Tech Report: Solana’s Trump memecoin launch tested infrastructure ahead of institutional push, Lily Liu states
General
⚖️ Neutral
🌐 Mrmoneymustache
#21853. $656,000 of Frugal Things I Still Love Doing
📅 24 Jul 2024 • ⏱️ 10m • 📚 Deep Dive (1971 w)
$656,000 of Frugal Things I Still Love Doing
📅 24 Jul 2024 | ⏱️ 10 min read (1971 words, 📚 Deep Dive) | Source: Mrmoneymustache
⏱️ ~10 mins left to finish
📖 0% read
💡 Key Takeaways
- “Until he got all rich and fancy so that he no longer understands the common person’s plight.
- Stash probably doesn’t even practice any of these money-saving things he preaches any more!”.
- When I read things like this, I can’t help but laugh.
“I used to read Mr. Money Mustache”,.
“Until he got all rich and fancy so that he no longer understands the common person’s plight.
Stash probably doesn’t even practice any of these money-saving things he preaches any more!”.
When I read things like this, I can’t help but laugh. Because on the one hand, when you put a bunch of personal life details online like this, being misunderstood is just part of the package. But on the other hand, if the critics could peek in and see our real lives – not just mine but those of all the Mustachians – they would have to give up their conspiracy theories and accept the fact that this stuff just works.
Because really, not much has changed when it comes to the basics. Like many MMM readers over the past twelve years, my total wealth level has increased pretty regularly. But also like many of us, I haven’t felt the need to change very much about my spending because I was doing my best to live an enjoyable life in the first place.
Industry observers note that how have so many people found such great success? I think we Mustachians have something that’s a bit more rare and special than standard financial advice, which is what makes it work so well:.
Sources indicate that standard Advice: Slash your spending and make sacrifices until you reach a certain savings percentage, and beyond that it doesn’t matter, it’s all personal choice. More income? Great, that means you don’t have to sacrifice as much! FatFIRE for everyone!
Mustachianism: Cultivate a love of efficiency, creativity, self awareness, and self improvement. Use this knowledge to improve your life in all ways, including those which help you live better even as your monthly expense rate drops over time.
So what does this mean in practice?
Industry observers note that well, I’ll give you some examples from my own present-day life. Things I do because I happen to enjoy them, which also happen to save a lot of money. Some of these are normal, some are silly and may end up in some future gossip magazine hit piece, but all of them happen to work for me, so the critics can be damned.
As I list each item, I’ll include an estimate of how much the activity saves me per decade, because you should always think at least in terms of decades. To make that calculation yourself, just use the “rule of 172” – take a monthly expense and multiply it by 172 to estimate how much it would compound into over ten years, if invested.
1) Fixing my own House (and everybody else’s too).
I’m a massive believer in self-sufficiency, and working to build up the skills to manage the most crucial parts of your own life without depending on too many things (or people) that are outside of your control. In other words, one giant recipe for a happy life is simply to Become a Producer of the Things You Most Enjoy Consuming.
And in my case, I happen to love houses. I like living in beautiful, functional spaces and sharing them with friends. But most houses are ugly and poorly designed when you buy them, so I realized that I also love solving problems and redesigning old buildings to become new again. I enjoy this process so much that I spend most of my free time doing it – on both my own properties and the homes of friends.
Sources indicate that and I love teaching other people to gain power over their own houses too. It’s amazing how great people feel as they lose their fear and dependence on outside contractors, and gain the ability to fix and maintain things with their own two hands.
Savings: An average of $20,000 per year = $287,000 per decade.
You know what’s great? Having so much money that you can buy whatever you want – high quality things which get delivered to your front door the very next day.
According to recent reports, you know what’s even better? Not buying some of those newly introduced things, and instead finding ways to share, repurpose and buy equally high quality items from other people who don’t need them any more. All while building up your own community and creating new friendships in the process.
Craigslist, Facebook Marketplace, and even NextDoor all have Buy Nothing groups for most areas. In the MMM-HQ community, we run a Discord server with about 200 local people, who chat around the clock on a wide range of subjects. They help each other with major projects in one channel called #diyhowto, and give away and sell things on #forsale and #buynothing.
Although our private Discord group is my favorite, I also use Craigslist regularly, and probably save (and earn) a few thousand every year thanks to the habit:.
Savings: About $42,000 per decade.
Recent findings suggest that we all know that Mr. Money Mustache’s biggest contribution to personal finance is to insist that bike transportation is the best way to get around. And I still feel this way. As we learned in The True Cost of Commuting, cars cost at least 50 cents per mile to operate, while bikes are much cheaper, mainly due to reduced depreciation and maintenance costs (which are even bigger than the gas savings).
In a recent development, I do still use bikes (or walking) for at least 95% of my local trips these days, but because I live in the center of a small city, my life is pretty local. So this still only adds up to about 2000 miles per year, a savings of “only” $14,000 per decade.
But when you choose active transportation, there’s much more to the picture than just cutting your car expenses. You’re changing everything about your physical and mental health picture for the better, which brings us to the next point of….
Although I’m no competitive athlete, whenever I see an option to make my body work a bit harder, I usually take it. Stairs instead of elevators, running the golf course instead of using a golf cart, moving my own furniture and appliances instead of calling a mover, shoveling snow and raking leaves instead of using a machine.
It has been revealed that when I face a decision like this, I simply ask myself the question: “Well, Mustache. Do you want MORE health and fitness, or LESS?” Putting it in that context makes the answer obvious. Every bit helps, because when it comes to your body, the rule is pretty much use it or lose it.
But how much money does this save? There’s no real way to calculate it exactly, but I like to think of it this way: The US average health care spending is about $13,000 per person per year. My lifetime costs due to illness or medication so far have been just about zero, plus I know I’ve had more energy and greater productivity due to being healthy. Let’s just put it very conservatively and set the estimated savings and benefits at $10k per year which means.
Estimated Savings: $140,000 per decade.
5) Saving Energy by Running my home like a Glamping Retreat.
Here’s where things get a bit silly, but my level of joy is actually at its greatest.
It has been revealed that my personality type is probably a weird combination of an engineer, a carpenter, an artsy hippie, and a mad scientist. Oh, and a devoted homebody too. Because of this, my favorite activity most days is to just run around my house taking care of things and trying new little experiments and improvements.
Sometimes I’ll cut a few big holes on on the South side of the house and install sliding doors and big windows to allow nice sunbeams and passive solar energy to get into my house and give me free heat in the winters. Other times it’s just smaller things to save energy and live more at at one with the seasons of my area:.
Even taken all together, these things are pretty small – the average combined gas and electric bill for my area is about $250 per month, while my usage adds up to about $75. So while we’re only saving about $30,000 per decade for what sounds like a lot of work to most people, I consider this to be the biggest win because I enjoy living in “MMM’s Energy Efficiency Playground” so much.
6) Local Living over Constant Travel.
“Hey, we’re having a big back yard pool party next weekend to celebrate Amy’s graduation from kindergarten, can you make it?”.
“OH NOOOO!!! We will be off in at Disneyland that whole week! We planned the trip months ago, I wish we could make it!
According to recent reports, as I type this in the height of the summer season, I really feel this effect at its fullest: almost all of my friends are off on trips, and my guest suite here at home is almost constantly full. People are traveling a lot, and many of them sound like they wish they could spend a few more of their precious summer weeks and weekends at home.
I’ll let you in on a little secret: you can! The trick is saying, “no thanks” more often to aims that involve you being away, and “yes please” to things that let you stay at home. The benefits are numerous:.
It has been revealed that estimated Savings: Even if you replace just two weeks of travel for a family of four, with equivalent time at home you might save $5,000 per year in direct costs and a further $5,000 per year in incidental benefits like the health and local friendships. This would work out to a shocking $143,000 per decade of wealth increase!
According to recent reports, of course, travel is generally a good thing for broadening the life experience of you and your kids. It’s worth spending on, lavishly at times. But the key is to balance it out and be discerning, keeping the most enriching trips and pruning a few off the bottom of the list. And remembering that home time is valuable and healthy too.
And Whoa! We’ve already built up a huge list and I feel like I was just getting started.
Taken all together, we’ve already detailed things that compound to $656,000 every decade, which already more than double the median wealth that most American seniors have as they cruise nervously into their retirement years – after over 40 years of work!
And now that I’ve been writing this blog for over ten years myself, I can safely say that over $656,000 of even my most recent worth increases are directly attributable to these simple habits. The same ones many of us have been enjoying and preaching about all along, both before and after our retirement dates.
In a recent development, if money is in genuinely short supply, you could go a lot further than the examples in this article. And indeed, there’s a lot more laid out in this blog or the MMM Boot Camp email series.
Sources indicate that but one of the points of Mustachianism is that you usually don’t have to try all that hard. Just tweaking your lifestyle to be slightly less ridiculous and more efficient than average is usually all it takes.
Recent findings suggest that in the comments: what are your quirks and frugal indulgences? The things you do now to save money, or things you still do even after it’s no longer about the money? I often wonder how widespread this frugality-just-for-fun is. But since we Humans are a naturally curious and problem solving species in our natural state, I suspect there are many more of us out there.
🔗 Related Articles
📰 #20486. Elon Musk’s Grokipedia is littered with mistakes. But Wikipedia could still learn some things from it. 📰 #23609. The young rebel alliance trying to get people to love technology again 📰 #23444. Geren reopens Texas casino fight, but his amendment still needs 21 Republican-led Senate votes
General
⚖️ Neutral
🌐 Mensjournal
#21852. ’90s Alternative Rock Band Is Officially No. 1 on the Charts 32 Years After Their Debut
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (28 w)
’90s Alternative Rock Band Is Officially No. 1 on the Charts 32 Years After Their Debut
📅 17 Nov 2026 | ⏱️ 1 min read (28 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
This song has been rocking it for nearly 30 years, and now, it’s back on the charts and it’s No. 1 in the world.
🔗 Related Articles
📰 #21874. Sam Heughan and Model Girlfriend Make Their Red Carpet Debut 📰 #21820. 35 Years Ago, a Legendary Band Released a No. 1 Album That Michael Jackson Knocked Off the Top in Just One Week 📰 #19822. Kate Middleton and Prince William Begin Their First Overseas Tour in Four Years
AI & Tech
⚖️ Neutral
🌐 Seekingalpha
#21851. Has The AI Bubble Popped?
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (205 w)
Has The AI Bubble Popped?
📅 17 Nov 2026 | ⏱️ 1 min read (205 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- The week started with yet another bloodbath in the AI trade, with the VanEck Semiconductor ETF (SMH) declining over 5% yesterday, compared to the 1.92% decline in the S&P 500 (SPY).
- Sources indicate that analystâs Disclosure: I/we have a beneficial long position in the shares of AMD, MU, SNDK, STX, SITM, ALAB, AMZN either through stock ownership, options, or other derivatives.
- Sources indicate that seeking Alpha's Disclosure: Past performance is no guarantee of future results.
Dragon Claws/iStock via Getty Images.
Dragon Claws/iStock via Getty Images.
The week started with yet another bloodbath in the AI trade, with the VanEck Semiconductor ETF (SMH) declining over 5% yesterday, compared to the 1.92% decline in the S&P 500 (SPY).
Sources indicate that analystâs Disclosure: I/we have a beneficial long position in the shares of AMD, MU, SNDK, STX, SITM, ALAB, AMZN either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any tech giant whose stock is mentioned in this article.
Sources indicate that seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
General
⚖️ Neutral
🌐 Mensjournal
#21850. Mexican Drug Lord Who Inspired Netflix's Narcos: Mexico Dies at 80 After 37 Years Behind Bars
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (47 w)
Mexican Drug Lord Who Inspired Netflix's Narcos: Mexico Dies at 80 After 37 Years Behind Bars
📅 17 Nov 2026 | ⏱️ 1 min read (47 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Miguel Ángel Félix Gallardo, the Mexican drug lord known as the "Boss of Bosses" whose life inspired Narcos: Mexico, has died at 80 after more than 37 years in prison for drug trafficking and the 1985 murder of DEA agent Enrique "Kiki" Camarena.

General
⚖️ Neutral
🌐 Muscleandfitness
#21849. Tech Report: Record 40,000 to Attend Sold-out ‘Rocky Run’ in Philadelphia
📅 13 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Tech Report: Record 40,000 to Attend Sold-out ‘Rocky Run’ in Philadelphia
📅 13 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
🔗 Related Articles
📰 #22255. Tech Report: Sotheby’s Hospices de Beaune Charity Wine Sale Nets $15.8 M. in France, with One Barrel Selling for Record $1.1 M. 📰 #22004. Tech Report: Run the Big Sur International Marathon With Runner’s World 📰 #20803. Tech Report: Philadelphia Is Dusting Off the Subprime Playbook
Business & Policy
⚖️ Neutral
🌐 Seekingalpha
#21848. Latest Update: Energy Recovery: The Market Is Too Short-Sighted Now
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Latest Update: Energy Recovery: The Market Is Too Short-Sighted Now
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #22499. Breaking: Comment | Is art market regulation too much of a ‘good thing’? 📰 #18495. Strategy Bitcoin vs. BitMine Ethereum: Which Crypto Treasury Is Better Positioned for a Market Recovery? 📰 #18385. Breaking: U.S. Department of Energy Bets on XRP Ledger for Blockchain-Based Energy Market Settlements
General
⚖️ Neutral
🌐 Mensjournal
#21847. Breaking: Walmart Has a Lockable Steel Garage Cabinet That's Over 50% Off and Holds Up to 450 Pounds
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
Breaking: Walmart Has a Lockable Steel Garage Cabinet That's Over 50% Off and Holds Up to 450 Pounds
📅 17 Nov 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
It's a space-saving storage solution fit for any wall in your garage.
🔗 Related Articles
📰 #23564. Deals: Galaxy SmartTag 3 up to 30% off, Chromebooks, Google Home Speaker, Walmart early Black Friday now live, more 📰 #20942. Walmart Has Milwaukee Tools Up to 40% Off for Early Black Friday—Save on Drills, Automotive Tools, Storage Options, and More 📰 #16345. These Beats Solo 4 Headphones Are 65% Off During Walmart's Early Black Friday Sale
General
⚖️ Neutral
🌐 Mensjournal
#21846. Tech Report: Scientists Studied People Who Lived Past 100 and Found a Clue Beyond Their Genes
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (23 w)
Tech Report: Scientists Studied People Who Lived Past 100 and Found a Clue Beyond Their Genes
📅 17 Nov 2026 | ⏱️ 1 min read (23 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Scientists examining 125 people who lived past 100 discovered a gut bacteria pattern that may help explain healthier aging.

Business & Policy
⚖️ Neutral
🌐 Seekingalpha
#21845. The Rotation Trade: Chasing Another Bubble
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (204 w)
The Rotation Trade: Chasing Another Bubble
📅 17 Nov 2026 | ⏱️ 1 min read (204 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Sources indicate that the S&P 500 (SPY) is down by around 3% over the last twelve months.
- Investors have been exiting the AI trade and selling AI-related stocks in the.
- In a recent development, analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours.
Sources indicate that the S&P 500 (SPY) is down by around 3% over the last twelve months. However, under the surface, there has been a major rotation.
Investors have been exiting the AI trade and selling AI-related stocks in the.
In a recent development, analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any manufacturer whose stock is mentioned in this article.
Seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
🔗 Related Articles
📰 #21833. DRAM: AI Bubble Burst Could Take Down The Memory Trade (Rating Downgrade) 📰 #23561. Breaking: Nothing’s screen-less fresh gadget really looks like yet another AI recorder 📰 #23305. Latest Update: The Jensen Huang saga could be the beginning of the end of the AI bubble – or just a boon for competitors
General
⚖️ Neutral
🌐 Muscleandfitness
#21844. Robert Strauss Has the Full-Body F45 Workout to Stay Fit over 40
📅 13 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Robert Strauss Has the Full-Body F45 Workout to Stay Fit over 40
📅 13 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
General
⚖️ Neutral
🌐 Mensjournal
#21843. Amin Joseph on Playing Sonny Liston in ‘The Greatest' & He Weighs in on ‘Snowfall’ Debate (Exclusive)
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (30 w)
Amin Joseph on Playing Sonny Liston in ‘The Greatest' & He Weighs in on ‘Snowfall’ Debate (Exclusive)
📅 17 Nov 2026 | ⏱️ 1 min read (30 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
In a Men’s Journal exclusive, Amin Joseph talks about his journey playing Sonny Liston in ‘The Greatest,’ his take on Muhammad Ali, and reflects on ‘Snowfall.’.

General
⚖️ Neutral
🌐 Seekingalpha
#21842. Damora Therapeutics, Inc. (DMRA) Presents at UBS Global Biopharma Conference 2026 Transcript
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (298 w)
Damora Therapeutics, Inc. (DMRA) Presents at UBS Global Biopharma Conference 2026 Transcript
📅 17 Nov 2026 | ⏱️ 1 min read (298 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- (DMRA) UBS Global Biopharma Conference 2026 November 17, 2026 5:00 AM EST.
- Jennifer Jarrett - CEO, President & DirectorSherwin Sattarzadeh - Chief Operating Officer.
- Matthew Hagood - UBS Investment Bank, Research Division.
Damora Therapeutics, Inc. (DMRA) UBS Global Biopharma Conference 2026 November 17, 2026 5:00 AM EST.
Jennifer Jarrett - CEO, President & DirectorSherwin Sattarzadeh - Chief Operating Officer.
Matthew Hagood - UBS Investment Bank, Research Division.
Matthew HagoodUBS Investment Bank, Research Division.
In a recent development, all right. Well, great. Thank you, guys, for being here. We're going to get started with our next session. My name is Matt Hagood. I'm on the research team here at UBS working with Mike Yee. We are excited to welcome our next presenting organization, Damora Therapeutics, and we have the team here. Guys, thanks for being here.
Matthew HagoodUBS Investment Bank, Research Division.
Maybe give a quick introduction and then some background on Damora and the progress you made this year and kind of the mCALR space that you're working in. It would be great.
Jennifer JarrettCEO, President & Director.
Yes. So just quickly for introductions. I'm Jen Jarrett and I'm the CEO of Damora.
Sherwin SattarzadehChief Operating Officer.
I'm Sherwin Sattarzadeh, the Chief Operating Officer.
Jennifer JarrettCEO, President & Director.
So background on Damora. So we are a Fairmount firm. We're actually the sixth company that was founded by Fairmount. I'm sure you guys are familiar with a lot of the other Fairmount companies, I think they're up to like 11 or 12 and definitely double digits now. We were founded specifically to focus on hematological diseases and our initial focus is on the myeloproliferative neoplasm space. So myeloproliferative neoplasm is a group of blood cancers.
The 2 that we are focusing on is: essential thrombocythemia, which is when a patient produces too many platelets; and myelofibrosis, which is when a patient cannot produce healthy blood cells and so these patients tend to be either anemic or.
🔗 Related Articles
📰 #21836. Industry News: Ocular Therapeutix, Inc. (OCUL) Presents at UBS Global Biopharma Conference 2026 Transcript 📰 #21816. Latest Update: MannKind Corporation (MNKD) Presents at UBS Global Biopharma Conference 2026 Transcript 📰 #21813. Tech Report: Illumina, Inc. (ILMN) Presents at Jefferies Global Healthcare Conference 2026 Transcript
General
⚖️ Neutral
🌐 Muscleandfitness
#21841. At 43, Robert Strauss Continues Training to Be the ‘Dad Bod Destroyer’
📅 13 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
At 43, Robert Strauss Continues Training to Be the ‘Dad Bod Destroyer’
📅 13 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
The Workout Robert Strauss Uses to Stay Fit over 40
🔗 Related Articles
📰 #21844. Robert Strauss Has the Full-Body F45 Workout to Stay Fit over 40 📰 #15171. Breaking: Jack Grealish APOLOGISES after being dropped for missing training without permission as Everton star continues comeback trail in behind-closed-doors game 📰 #23515. PRX Part 3 — Training a Text-to-Image Model in 24h!
General
⚖️ Neutral
🌐 Mensjournal
#21840. 26 Years Ago: Arnold Schwarzenegger's 'The 6th Day,' Ranked Among His 'Worst Movies,' Debuted
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (11 w)
26 Years Ago: Arnold Schwarzenegger's 'The 6th Day,' Ranked Among His 'Worst Movies,' Debuted
📅 17 Nov 2026 | ⏱️ 1 min read (11 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Not every Arnie film is a gem.
🔗 Related Articles
📰 #21862. Tech Report: James Bond Classic Ranked Among 'Best Action Movies of All Time' Released 31 Years Ago Today 📰 #21807. 1989 Comedy, Ranked Among Eddie Murphy's Best Movies, Released 37 Years Ago Today 📰 #21855. 2006 Daniel Craig Film, Ranked No. 4 of 27 Bond Movies by Critics, Released 20 Years Ago Today
General
⚖️ Neutral
🌐 Seekingalpha
#21839. Ascendis Pharma A/S (ASND) Presents at Jefferies Global Healthcare Conference 2026 Transcript
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (297 w)
Ascendis Pharma A/S (ASND) Presents at Jefferies Global Healthcare Conference 2026 Transcript
📅 17 Nov 2026 | ⏱️ 1 min read (297 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Ascendis Pharma A/S (ASND) Jefferies Global Healthcare Conference 2026 November 17, 2026 6:30 AM EST.
- Jan Mikkelsen - President, CEO, Member of Executive Board & Executive DirectorScott Smith - CFO, Executive VP & Member of Executive Board.
- Faisal Khurshid - Jefferies LLC, Research Division.
Ascendis Pharma A/S (ASND) Jefferies Global Healthcare Conference 2026 November 17, 2026 6:30 AM EST.
Jan Mikkelsen - President, CEO, Member of Executive Board & Executive DirectorScott Smith - CFO, Executive VP & Member of Executive Board.
Faisal Khurshid - Jefferies LLC, Research Division.
Faisal KhurshidJefferies LLC, Research Division.
All right. Good morning, everyone. Thank you for joining us here in nice and rainy London. My name is Faisal Khurshid. I'm one of the senior biotech analysts here at Jefferies. Really pleased to have with us today management team of Ascendis Pharma. I have on stage with me Jan Mikkelsen, CEO; Scott Smith, CFO of the firm. But let's get right to it.
Faisal KhurshidJefferies LLC, Research Division.
I mean, you guys just reported nice third quarter earnings last week. You have 2 growth products. Maybe we can just start with some of the highlights from earnings. I don't know, Jan, if you want to start or Scott?
Jan MikkelsenPresident, CEO, Member of Executive Board & Executive Director.
I think Scott should start today.
Scott SmithCFO, Executive VP & Member of Executive Board.
Start with the question or start with the FLS? Okay. Yes. So thanks for the invitation for the conference here, and it's a really neat setting to see everybody packed in here. As you alluded to, we just reported our 3Q results last week. So the conference is timely. We had pretty good revenue growth, I would say, 90% or so year-over-year to EUR 366 million, strong growth across the portfolio. We also announced, which Jan, I'm sure, will be interested to go into detail on.
And across -- from an OpEx perspective, we had about EUR 230 million of OpEx, leading to pretty good, I would say, almost industry-leading.
🔗 Related Articles
📰 #21813. Tech Report: Illumina, Inc. (ILMN) Presents at Jefferies Global Healthcare Conference 2026 Transcript 📰 #21842. Damora Therapeutics, Inc. (DMRA) Presents at UBS Global Biopharma Conference 2026 Transcript 📰 #21836. Industry News: Ocular Therapeutix, Inc. (OCUL) Presents at UBS Global Biopharma Conference 2026 Transcript
General
⚖️ Neutral
🌐 Mensjournal
#21838. Lindsay Clancy Holdout Juror Reveals What Happened Behind Closed Doors
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (48 w)
Lindsay Clancy Holdout Juror Reveals What Happened Behind Closed Doors
📅 17 Nov 2026 | ⏱️ 1 min read (48 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Michael Desronvil, the lone juror who refused to find Lindsay Clancy not criminally responsible in her 2026 murder trial, describes how his dissent led to a mistrial, public scrutiny, harassment, and a collapsed private life as Clancy prepares for a retrial in March 2027.
🔗 Related Articles
📰 #18659. What Happened to Lindsay Clancy’s Home? How Duxbury House Was Quietly Sold to Former DA in Off-Market Deal Just a Year After Kids’ Deaths 📰 #15171. Breaking: Jack Grealish APOLOGISES after being dropped for missing training without permission as Everton star continues comeback trail in behind-closed-doors game 📰 #13893. Everton Win Behind-Closed-Doors Clash With Derby
General
⚠️ Warning
🌐 Muscleandfitness
#21837. Latest Update: The Peptide Door Is Cracking Open, Even If The Risks Aren’t Going Away
📅 16 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Latest Update: The Peptide Door Is Cracking Open, Even If The Risks Aren’t Going Away
📅 16 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
🔗 Related Articles
📰 #22828. 19 non-traditional Thanksgiving desserts that aren't pie : Cakes, cookies, and even a tiramisu for your holiday dessert table. 📰 #22247. At Sotheby’s $378.7 M. Doubleheader, Buyers Take Risks Again, Even as Bidding Drags 📰 #18934. Latest Update: Trump leaves door open to Kim Jong Un joining high-stakes talks with Xi, Putin
General
⚖️ Neutral
🌐 Seekingalpha
#21836. Industry News: Ocular Therapeutix, Inc. (OCUL) Presents at UBS Global Biopharma Conference 2026 Transcript
📅 17 Nov 2026 • ⏱️ 2m • 📖 Standard (324 w)
Industry News: Ocular Therapeutix, Inc. (OCUL) Presents at UBS Global Biopharma Conference 2026 Transcript
📅 17 Nov 2026 | ⏱️ 2 min read (324 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- Sources indicate that ocular Therapeutix, Inc.
- Pravin Dugel - Executive Chairman, President & CEO.
- Alice Nettleton - UBS Investment Bank, Research Division.
Sources indicate that ocular Therapeutix, Inc. (OCUL) UBS Global Biopharma Conference 2026 November 17, 2026 7:00 AM EST.
Pravin Dugel - Executive Chairman, President & CEO.
Alice Nettleton - UBS Investment Bank, Research Division.
Alice NettletonUBS Investment Bank, Research Division.
Industry observers note that good morning, everybody. Welcome to the next session at the UBS Biopharma Conference in London. I'm Alice Nettleton, one of the U.S. SMID biotech analysts at UBS. Happy to introduce Ocular Therapeutix. With us today is Pravin Dugel, CEO. Thank you so much, Pravin, for joining us. Good to see you.
Pravin DugelExecutive Chairman, President & CEO.
According to recent reports, and Alice, thanks for having me. I appreciate your invitation to be here.
Alice NettletonUBS Investment Bank, Research Division.
It has been revealed that absolutely. So maybe just to level set for the audience, for people who are less familiar with the Ocular story, could you give a quick overview? And then we can move to some Q&A.
Pravin DugelExecutive Chairman, President & CEO.
Sources indicate that sure. So the organization is called Ocular Therapeutix. We have a drug that has successfully completed a Phase III study. We have been able to show superiority versus an anti-VEGF for the first time ever. We have a result that has a very robust p-value of less than 0.0006, and we're getting ready to submit for approval this quarter. We are on track to do that. The drug is called AXPAXLI. It's a TKI. We believe that we'll be the first and only proper maintenance drug. We have shown in this trial that this drug will last for a year in most patients. And unlike the other drugs that you know about that are bolus injections, and there's a lot of them, whether they be generic or premium drugs, we believe that our drug will be the first drug that will be approved as a true maintenance drug.
🔗 Related Articles
📰 #21842. Damora Therapeutics, Inc. (DMRA) Presents at UBS Global Biopharma Conference 2026 Transcript 📰 #21816. Latest Update: MannKind Corporation (MNKD) Presents at UBS Global Biopharma Conference 2026 Transcript 📰 #21813. Tech Report: Illumina, Inc. (ILMN) Presents at Jefferies Global Healthcare Conference 2026 Transcript
Gadgets
⚖️ Neutral
🌐 Mensjournal
#21835. 3 Weather Concerns to Watch Across the US This Week
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (30 w)
3 Weather Concerns to Watch Across the US This Week
📅 17 Nov 2026 | ⏱️ 1 min read (30 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Much of the eastern United States is heading into an unusually warm stretch for November, with temperatures expected to reach the 60s in several major cities.
General
📈 Bullish
🌐 Mensjournal
#21834. Latest Update: John Lennon and Yoko Ono’s Grammy-Winning 1980 Album Left Out Recordings With Two Cheap Trick Members
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (25 w)
Latest Update: John Lennon and Yoko Ono’s Grammy-Winning 1980 Album Left Out Recordings With Two Cheap Trick Members
📅 17 Nov 2026 | ⏱️ 1 min read (25 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Fans waited 18 years to hear the shelved version of “I’m Losing You,” revealing a harder sound than the familiar release.

AI & Tech
⚖️ Neutral
🌐 Seekingalpha
#21833. DRAM: AI Bubble Burst Could Take Down The Memory Trade (Rating Downgrade)
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (189 w)
DRAM: AI Bubble Burst Could Take Down The Memory Trade (Rating Downgrade)
📅 17 Nov 2026 | ⏱️ 1 min read (189 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- The AI infrastructure space has already been facing a significant confidence crisis, which has also gotten worse since former NVIDIA Corporation (NVDA) CEO Jensen Huang resigned.
- Sources indicate that analystâs Disclosure: I/we have a beneficial long position in the shares of NVDA, GOOGL either through stock ownership, options, or other derivatives.
- Seeking Alpha's Disclosure: Past performance is no guarantee of future results.
Benjamin Fanjoy/Getty Images News.
Benjamin Fanjoy/Getty Images News.
The AI infrastructure space has already been facing a significant confidence crisis, which has also gotten worse since former NVIDIA Corporation (NVDA) CEO Jensen Huang resigned.
Sources indicate that analystâs Disclosure: I/we have a beneficial long position in the shares of NVDA, GOOGL either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
🔗 Related Articles
📰 #18343. Industry News: Hackers have cut power in Ukraine, but could they take down the U.S. grid? 10 cases 📰 #16858. Barbie Rewind, out now, invites you to take a trip down memory lane with a whole bunch of life in plastic classics, and one game that was previously unreleased 📰 #15498. Industry News: Could Tarik Skubal take a short-term, high-AAV contract? Breaking down pros and cons
General
⚖️ Neutral
🌐 Choosefi
#21832. Air France-KLM Flying Blue → Tahiti Business Class
📅 04 Nov 2026 • ⏱️ 13m • 📚 Deep Dive (2563 w)
Air France-KLM Flying Blue → Tahiti Business Class
📅 04 Nov 2026 | ⏱️ 13 min read (2563 words, 📚 Deep Dive) | Source: Choosefi
⏱️ ~13 mins left to finish
📖 0% read
💡 Key Takeaways
- The only points path to nonstop business class service to French Polynesia.
- Picture this: you're reclining in a fully flat bed somewhere over the Pacific, a glass of Champagne in hand, watching the sun melt into the ocean from 35,000 feet.
- The core insight here is deceptively simple: Air France-KLM's Flying Blue program is the only way to book the only nonstop flight between Los Angeles and Tahiti using points — and that program happens to offer some of the most generous award pricing in the world.
The only points path to nonstop business class service to French Polynesia.
Picture this: you're reclining in a fully flat bed somewhere over the Pacific, a glass of Champagne in hand, watching the sun melt into the ocean from 35,000 feet. In eight hours, you'll land in Papeete — French Polynesia's gateway to overwater bungalows, turquoise lagoons, and the kind of trip people save their whole lives for. And you got here on points. This is the Air France business class seat to Tahiti, and it represents one of the most emotionally resonant redemptions in the entire travel rewards ecosystem. Not just because of where you're going — though Tahiti is bucket-list by definition — but because of the staggering gap between what you'd pay in cash and what you'll pay in miles. **The math will genuinely stop you in your tracks.** A business class ticket from Los Angeles (LAX) to Papeete (PPT) on Air France regularly retails between **$5,000 and $12,000 per person**. That's the cash reality. But with Flying Blue miles — Air France-KLM's frequent flyer program — you can book the same seat for as few as **88,000 miles**. At the high end of retail pricing, that's a value of **13.6 cents per point (CPP)**. Even at the low end, you're extracting **5.7 CPP** from miles that most programs value at 1–2 cents. In the ChooseFI community, we talk constantly about optimizing every dollar toward financial independence — and a redemption that turns 88,000 transferable points into a $5,000–$12,000 experience is about as powerful as it gets. Here's what makes this feel different from your average business class booking: Air France operates a **Boeing 787-9 Dreamliner** on this route, featuring a modern, premium business class cabin with direct aisle access for every seat, noise-reducing windows, better humidity levels, and that unmistakably French touch in service and catering. You're not just flying in a recliner — you're flying in a genuine lie-flat pod on one of aviation's most celebrated aircraft. And this is the only nonstop option. Air France is the **sole carrier operating nonstop LAX–PPT** service. That's not a coincidence — it's a pricing inefficiency baked into the route's geography, and it's exactly the kind of structural advantage the ChooseFI community knows how to exploit.
The core insight here is deceptively simple: Air France-KLM's Flying Blue program is the only way to book the only nonstop flight between Los Angeles and Tahiti using points — and that program happens to offer some of the most generous award pricing in the world.
It has been revealed that flying Blue uses a dynamic award pricing model, meaning costs fluctuate based on demand and availability. That sounds like a disadvantage — and sometimes it is. But here's the inefficiency: Flying Blue releases Promo Rewards every single month. These are fixed-price award seats on select routes, discounted 25–50% off standard award pricing. When Tahiti appears as a Promo Reward destination (which it does periodically), the pricing drops dramatically — and crucially, Promo Reward tickets eliminate carrier-imposed fuel surcharges entirely.
Fuel surcharges on Air France-operated flights are normally moderate, but they're real — they can add $200–$500 to an award ticket. Promo Rewards wipe those out. This is the pricing inefficiency: Flying Blue is essentially subsidizing this cabin to drive demand, and you can capture the subsidy.
In a recent development, here's the beautiful part for ChooseFI members: virtually every major transferable points currency sends to Flying Blue at a 1:1 ratio. That means:.
The Chase, Amex, and Citi transfers are instant, which matters enormously when you're racing to lock down a business class award seat before someone else grabs it. You find the seat, you confirm it's available, then you transfer — because once points leave your bank, they don't come back.
Recent findings suggest that this is the single most important rule in booking award travel, and it's especially critical here. Flying Blue's award availability on the LAX–PPT route is genuinely limited — this is a popular route to a popular destination on a single aircraft. You do not transfer points speculatively. You find confirmed availability on flyingblue.com, verify the seat count and pricing, then immediately transfer from your Chase, Amex, or Citi account (all instant) and book.
It has been revealed that flying Blue allows open-jaw routing, meaning you could potentially fly into Papeete and out of another South Pacific destination if Air France serves it — giving sophisticated travelers a way to build a multi-destination itinerary without paying for a separate return trip to your origin city. It's a small but meaningful piece of flexibility in a program that doesn't always offer it.
This is a moderate-difficulty booking. The steps themselves aren't complicated — but the sequencing matters enormously. Follow this in order.
According to recent reports, go to flyingblue.com and use the award search tool. You do NOT need a Flying Blue account to search — but you will need one to book, so create a free account if you haven't already. Search LAX → PPT in business class. Flying Blue's calendar view lets you scan across multiple departure dates, which is essential for spotting availability on a route with limited award seats.
It has been revealed that tip: Flying Blue's booking window opens 359 days in advance. For a route this popular and this capacity-constrained, searching at the 11-month mark is strongly advised. Set a calendar reminder for exactly 359 days before your target travel dates.
It has been revealed that on the first of each month, Flying Blue releases its fresh Promo Rewards. These are fixed-price, reduced-cost awards with no fuel surcharges. Bookmark flyingblue.com/en/earn-spend/flying-blue-promo-rewards and check it monthly. If Tahiti appears, act immediately — Promo Reward availability disappears fast.
Once you find available dates and seats, note the exact miles price shown at checkout. Flying Blue's dynamic pricing means the cost you see on Monday might differ from Thursday. Screenshot the search result with the price clearly visible. This is your confirmation that the award is priceable before you transfer points.
Now — and only now — transfer your points:.
Transfer the exact amount you need — no more, no less.
It has been revealed that return to flyingblue.com, complete the search again with your now-funded account, and book. Have your passport and traveler details ready. Pay any taxes/fees (usually $50–$150 on non-Promo awards; near-zero on Promo Rewards) with a travel rewards credit card to earn additional points.
In a recent development, award availability on this route moves rapidly. If your target dates are sold out:.
Flying Blue uses dynamic award pricing, which usually makes award charts unpredictable. But the monthly Promo Rewards program creates a fixed-price overlay that dramatically undercuts the dynamic rates. When Tahiti appears on the Promo Rewards list, business class pricing drops 25 to 50 percent below standard and fuel surcharges are eliminated entirely. Air France is the sole operator of the LAX to PPT nonstop — no other airline flies it — which means Flying Blue is the only loyalty program with direct booking access to this route. This combination of route exclusivity and periodic promotional pricing is what makes this a genuine sweet spot rather than just a good redemption.
In a recent development, card links may earn ChooseFI a commission. See our advertiser disclosure.
Sources indicate that let's make this concrete. Imagine a couple planning their 10th anniversary trip to Bora Bora in the spring of 2026. They want to start the trip right — meaning lie-flat seats over the Pacific, not a middle seat in economy for a nine-hour flight.
It has been revealed that the cash price: Air France business class from LAX to PPT in spring typically runs $6,500–$9,000 per person round-trip. For two people, you're looking at $13,000–$18,000. That's a car payment for most families. Even if it's in the travel budget, it's a brutal number to justify when you're pursuing financial independence.
The points price: 88,000 Flying Blue miles per person, round-trip in business class. For two passengers: 176,000 Flying Blue miles total, plus approximately $200–$300 in taxes and carrier fees (less if you catch a Promo Rewards release, where surcharges are waived entirely).
The CPP math: At $8,000 in cash value against 88,000 miles, you're extracting 9.1 cents per point — nearly 5–9x the baseline value of transferable points currencies. That's the ChooseFI lens: every point you've earned on everyday spending just multiplied in purchasing power.
According to recent reports, what you'll actually experience: You check in at LAX and are directed to the business class line — a detail that still feels quietly luxurious no matter how many times you've done it. Once onboard the Boeing 787-9 Dreamliner, your seat converts to a fully flat bed of approximately 6 feet in length. The cabin's reduced cabin pressure and higher humidity mean you arrive in Papeete meaningfully less fatigued than you would in economy — notable when you have a connecting boat ride to Bora Bora ahead of you.
Air France's catering reflects its French heritage: expect a proper multi-course meal service, a curated wine selection, and warm bread — not a foil-wrapped tray. The flight is roughly 8–9 hours nonstop, so there's time to genuinely sleep, watch a film, and arrive rested.
For a couple using points they accumulated from normal household spending over 12–18 months, the $16,000 in combined cash value they didn't spend is the real number — and the one that matters most on the path to FI.
According to recent reports, flying Blue releases Promo Rewards on the first of every month. Set a phone reminder. These promotions offer 25–50% off standard award pricing AND eliminate fuel surcharges. On a Promo Rewards release, an 88,000-mile business class award could drop to as low as 44,000–66,000 miles with no surcharges. That's the difference between good and extraordinary. Don't miss a cycle.
It has been revealed that flying Blue's booking window opens 359 days in advance. The LAX–PPT route operates a single daily nonstop on a single aircraft — meaning business class inventory is finite and competitive. If you're targeting holidays, school break windows, or peak Tahiti season (July–August), mark your calendar to search at the 11-month mark.
Recent findings suggest that flying Blue permits open-jaw routing, meaning you could potentially fly into PPT and return from a different city — or fly from a different origin. This flexibility can reduce deadhead positioning flights and help families traveling from cities other than Los Angeles build more logical itineraries.
In a recent development, this is the cardinal sin of award booking. Transferred points cannot be reversed. Never move miles to Flying Blue until you have confirmed award availability on your exact dates with a price you've screenshotted. Chase, Amex, and Citi all transfer instantly — use that speed advantage after you've confirmed the seat exists.
Flying Blue's dynamic pricing means the same route can cost meaningfully different amounts day-to-day and even hour-to-hour. Don't assume the price from your earlier search is locked in. Always verify at checkout before transferring.
According to recent reports, because Flying Blue accepts transfers from Chase, Amex, Citi, Capital One, and Bilt at 1:1, your earning strategy is flexible. Focus on a single flexible currency — the Chase Sapphire Preferred or Reserve for Ultimate Rewards, or the Amex Gold/Platinum for Membership Rewards — and let everyday spending build toward the 88,000-mile target over 12–18 months.
Sources indicate that marriott transfers to Flying Blue at 3:1 — meaning 264,000 Marriott points become 88,000 Flying Blue miles. Unless you have a massive Marriott balance you can't use elsewhere, this is an inefficient path. Stick to the 1:1 partners.
This redemption is purpose-built for couples and families planning a landmark trip to French Polynesia — an anniversary, a honeymoon, a milestone birthday, or simply the trip you've been telling yourself you'd take "someday." If Tahiti or Bora Bora is on the life list, this is the redemption that makes it financially defensible from a FI perspective.
In a recent development, minimum requirements: 88,000 Flying Blue miles per person for round-trip business class, plus approximately $100–$300 in taxes (less on Promo Rewards). For a couple, strategy for 176,000 transferable points minimum.
For the ChooseFI community, this redemption represents the travel rewards philosophy at its best: redirecting the value of everyday spending into genuinely transformative experiences, without derailing the path to financial independence.
Register for free at flyingblue.com. Enable email notifications for Promo Rewards announcements. Set a calendar reminder for the 1st of each month to check the new promo routes the moment they are released.
In a recent development, use the Flying Blue award search calendar view to scan business class availability on the LAX to PPT route across multiple dates. Check both standard pricing and Promo Rewards pricing. Do not transfer any points until you confirm available seats.
Recent findings suggest that once you confirm award space, transfer the required miles from Chase Ultimate Rewards (instant), Amex Membership Rewards (1-2 days), Citi ThankYou (instant), Capital One (1-2 days), or Bilt (1-2 days). Only transfer after confirming availability.
Complete the booking on flyingblue.com as soon as your miles arrive. Select your preferred lie-flat seat through the seat map. For couples, choose adjacent seats in the business cabin. Promo Rewards availability is limited and can disappear within hours.
Standard dynamic pricing typically runs around 88,000 miles one-way in business class from LAX to Papeete. When Tahiti appears on the monthly Promo Rewards list, that price can drop to 44,000 to 66,000 miles one-way with no fuel surcharges — a savings of 25 to 50 percent.
Tahiti is not guaranteed every month. Flying Blue rotates destinations across its network. You may see Tahiti appear several times per year, especially during shoulder season. The key is having your points ready and checking on the 1st of every month so you can act immediately when it appears.
Recent findings suggest that the nonstop Air France flight to Tahiti only departs from LAX. However, you can book a connecting itinerary through flyingblue.com that includes a domestic connection to LAX on the same award ticket. Alternatively, book a separate positioning flight to LAX using a different program.
No. One of the defining benefits of Promo Rewards is that fuel surcharges are eliminated entirely. You pay only the mile cost plus minimal taxes and airport fees, typically $60 to $100 per direction. This is a significant advantage over standard Flying Blue pricing, which can include carrier-imposed surcharges.
Sources indicate that this sweet spot was last verified over 90 days ago. Award availability and pricing may have changed — verify current rates before booking.
Flying Blue to Tahiti in business class is a genuinely unique sweet spot because no other loyalty program can book this route. The only nonstop from the US to French Polynesia operates exclusively on Air France out of LAX, and Flying Blue is the only way to book it with miles. At Promo Rewards pricing of 44,000 to 66,000 miles one-way, you are getting a $6,500 or more experience for transferable points that most ChooseFI members already hold. Set your monthly reminder, keep 80,000 to 100,000 points in reserve, and book the moment Tahiti appears on the promo list. For couples planning a milestone trip to Bora Bora or Moorea, this is the redemption that makes it financially defensible from a FI perspective.
General
⚖️ Neutral
🌐 Mensjournal
#21831. Latest Update: The North Face’s Sweat-Wicking Quarter-Zip Hoodies Are 50% off for REI’s Holiday Sale
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (18 w)
Latest Update: The North Face’s Sweat-Wicking Quarter-Zip Hoodies Are 50% off for REI’s Holiday Sale
📅 17 Nov 2026 | ⏱️ 1 min read (18 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
These "super comfortable" pullovers are what to wear on chilly fall and winter days.

General
⚖️ Neutral
🌐 Muscleandfitness
#21830. Terrence Ruffin Reveals His Strategy to Become 2027 Olympia Champion
📅 16 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Terrence Ruffin Reveals His Strategy to Become 2027 Olympia Champion
📅 16 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
How Robert Strauss Remains the 'Dad Bod Destroyer' at 43
🔗 Related Articles
📰 #22344. Show of every Jan van Eyck portrait reveals many new sides to his works 📰 #19738. ‘Dancing With the Stars’ Pro Jan Ravnik Reveals His Iconic Dream Guest Judges 📰 #16698. Tech Report: Robert Pattinson is the perfect choice for 007's new era, and his casting reveals what we can expect from Bond 26
AI & Tech
⚖️ Neutral
🌐 Seekingalpha
#21829. Stocks To Buy While AI Is Plunging
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (220 w)
Stocks To Buy While AI Is Plunging
📅 17 Nov 2026 | ⏱️ 1 min read (220 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- In a recent development, if you are my follower, you most likely know that I am an AI-focused investor, and most of my articles are about tech.
- In a recent development, analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no prepares to initiate any such positions within the next 72 hours.
- Sources indicate that seeking Alpha's Disclosure: Past performance is no guarantee of future results.
Shinsei Motions/iStock via Getty Images.
Shinsei Motions/iStock via Getty Images.
In a recent development, if you are my follower, you most likely know that I am an AI-focused investor, and most of my articles are about tech. At the same time, my portfolio, which is much riskier than the index, has a higher.
In a recent development, analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no prepares to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any firm whose stock is mentioned in this article.
Sources indicate that seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
🔗 Related Articles
📰 #17892. Cathie Wood’s Ark Invest loads up on crypto stocks while selling $85 million in Nvidia 📰 #17483. Scout's New Factory Is Already Making Trucks. But You Won't Be Able To Buy One For A While 📰 #16111. Crypto Sell-Off: Is Bitcoin a Buy After Plunging Below $70,000 Last Friday?
General
⚖️ Neutral
🌐 Mensjournal
#21828. Harry Potter Fans Rip HBO's First TV Clip as 'Ugly' and 'Awful'
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (27 w)
Harry Potter Fans Rip HBO's First TV Clip as 'Ugly' and 'Awful'
📅 17 Nov 2026 | ⏱️ 1 min read (27 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Upcoming HBO Max adaptation of Harry Potter to be released at Christmas although fans are wary after seeing first glimpse of the show.
🔗 Related Articles
📰 #16293. HBO releases first clip from its newly introduced ‘Harry Potter’ TV show — the internet immediately calls it ‘insulting,’ ‘lifeless’ and ‘Temu Harry Potter’ 📰 #22262. The first scene from the new Harry Potter series just dropped – and it's sparked a fierce filmmaking debate 📰 #19831. HBO’s Harry Potter TV Series: What We Know So Far
General
⚖️ Neutral
🌐 Seekingalpha
#21827. Mizrahi Tefahot Bank Ltd. 2026 Q3 - Results - Earnings Call Presentation
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (23 w)
Mizrahi Tefahot Bank Ltd. 2026 Q3 - Results - Earnings Call Presentation
📅 17 Nov 2026 | ⏱️ 1 min read (23 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
The following slide deck was published by Mizrahi Tefahot Bank Ltd. in conjunction with their 2026 Q3 earnings call.

General
⚖️ Neutral
🌐 Muscleandfitness
#21826. Joe Baena Gave Fans a Glimpse of His Bodybuilding Debut
📅 16 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (12 w)
Joe Baena Gave Fans a Glimpse of His Bodybuilding Debut
📅 16 Nov 2026 | ⏱️ 1 min read (12 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
Terrence Ruffin Reveals His Olympia-Winning Strategy for 2027
🔗 Related Articles
📰 #13295. “We need to protect green space in London, not just for football, but for every sport” Joe Cole opens up on his roots as he’s nominated for a prestigious ‘Made in London’ honour 📰 #23660. Tech Report: Gabe Newell praised for how he runs his $500m superyacht as it blows expert away 📰 #23444. Geren reopens Texas casino fight, but his amendment still needs 21 Republican-led Senate votes
General
📈 Bullish
🌐 Mensjournal
#21825. Tech Report: Macaulay Culkin Reprises His 'Home Alone' Role for McDonald's With a Nostalgic New Meal (EXCLUSIVE)
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (19 w)
Tech Report: Macaulay Culkin Reprises His 'Home Alone' Role for McDonald's With a Nostalgic New Meal (EXCLUSIVE)
📅 17 Nov 2026 | ⏱️ 1 min read (19 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Men's Journal spoke exclusively with Macaulay Culkin about the latest Home Alone meal at McDonald's.

General
⚖️ Neutral
🌐 Seekingalpha
#21824. Latest Update: MiniMed Group: An Improving Proposition
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (203 w)
Latest Update: MiniMed Group: An Improving Proposition
📅 17 Nov 2026 | ⏱️ 1 min read (203 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Sources indicate that in the spring I concluded that MiniMed Group, Inc.
- Analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no prepares to initiate any such positions within the next 72 hours.
- According to recent reports, seeking Alpha's Disclosure: Past performance is no guarantee of future results.
Sources indicate that in the spring I concluded that MiniMed Group, Inc. (MMED) did not provide a convincing investment opportunity. The former Medtronic diabetes business went public, valued at modest sales multiples, easily explainable by persistent operating losses. This.
Analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no prepares to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any firm whose stock is mentioned in this article.
According to recent reports, seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
General
⚖️ Neutral
🌐 Mensjournal
#21823. Lindsay Clancy's Lawyer Breaks Silence on Plea Deal as Retrial Date Is Set
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (38 w)
Lindsay Clancy's Lawyer Breaks Silence on Plea Deal as Retrial Date Is Set
📅 17 Nov 2026 | ⏱️ 1 min read (38 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Lindsay Clancy's lawyer has ruled out a plea deal as she faces a retrial on March 29, 2027, for the deaths of her three children, following a hung jury in her first murder trial.

General
⚖️ Neutral
🌐 Seekingalpha
#21822. The Elephant In The Room
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (205 w)
The Elephant In The Room
📅 17 Nov 2026 | ⏱️ 1 min read (205 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Industry observers note that roughly a week ago, I wrote a macro piece about âselling your portfolio every dayâ - metaphorically, of course.
- Sources indicate that analystâs Disclosure: I/we have a beneficial long position in the shares of NVDA, GOOGL, META, AMZN either through stock ownership, options, or other derivatives.
- Seeking Alpha's Disclosure: Past performance is no guarantee of future results.
gremlin/iStock via Getty Images.
gremlin/iStock via Getty Images.
Industry observers note that roughly a week ago, I wrote a macro piece about âselling your portfolio every dayâ - metaphorically, of course. You can check more about it here. In this article, I suggested that the market sometimes overreacts.
Sources indicate that analystâs Disclosure: I/we have a beneficial long position in the shares of NVDA, GOOGL, META, AMZN either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any manufacturer whose stock is mentioned in this article.
Seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
🔗 Related Articles
📰 #22400. ROOM’s Designers on Design Series Returns with A Story of Hospitality and Human Connection 📰 #22185. Virgin Atlantic → ANA "The Room" Business Class 📰 #22172. Mecanoo transforms former gold vault into "city’s living room" in renovation of De Nederlandsche Bank in Amsterdam
General
⚖️ Neutral
🌐 Mrmoneymustache
#21821. Six Dumb Misconceptions About The Economy (that the Politicians Want You To Believe)
📅 13 Oct 2024 • ⏱️ 10m • 📚 Deep Dive (2008 w)
Six Dumb Misconceptions About The Economy (that the Politicians Want You To Believe)
📅 13 Oct 2024 | ⏱️ 10 min read (2008 words, 📚 Deep Dive) | Source: Mrmoneymustache
⏱️ ~10 mins left to finish
📖 0% read
💡 Key Takeaways
- Well, it looks like we’re here in another US election year already.
- In a recent development, as Advanced Mustachians, we already know that the ongoing battle of Harris vs.
- Recent findings suggest that but out of all the things the politicians like to bicker about, there’s one area where MMM does need to set the record straight, and that area is of course money.
Well, it looks like we’re here in another US election year already.
In a recent development, as Advanced Mustachians, we already know that the ongoing battle of Harris vs. Trump should not be consuming much of our time. Sure, we do our research and cast our votes but after that we move right on to focus on other things within our own circle of control.
Recent findings suggest that but out of all the things the politicians like to bicker about, there’s one area where MMM does need to set the record straight, and that area is of course money. Your money, the economy in general, and the overall wealth of the nation.
Recent findings suggest that politicians are already not known for being the sharpest tools in the shed when it comes to technical stuff like science, technology, or economics. But this year the discourse has become particularly dumb, as our candidates try to manipulate undecided voters in swing states with ideas that are based on irrational emotions rather than sound economic sense.
For one particularly funny example, you may have noticed that the competing party (Trump in this case) is attacking the incumbents (Biden/Harris) over the “bad economy.” When in fact the US economy is stronger than it has ever been, with the lowest unemployment we’ve ever seen as well.
It’s hard to imagine a better situation than we have right now, and in fact the recent bout of higher inflation is a sign that things have been going too well, and we needed to step on the brakes with the help of higher interest rates.
According to recent reports, but somehow the people still seem to believe that we have a “bad” economy. Take a look at this Gallup poll showing that while most people (85%) are doing really well right now, they assume that it’s just their own good fortune – only 17% believe the economy is doing well.
According to recent reports, this is mathematically impossible, because if most people are doing well, that’s the definition of a good economy! And suspiciously enough, this widespread wrongness correlates quite nicely with the rise of social media misinformation.
In a recent development, so the politicians and the news have been doing the opposite of what they should be doing in an ideal situation (sharing accurate information). And sure, we can always just ignore their speeches and go on with our lives. But when it comes to economics, knowledge is power (and money). The more accurately we understand how things really work, the wealthier we will all become.
So with all that in mind, I hereby present you with my list of the….
Top Dumb Things Politicians Want You To Believe About The Economy.
1: The President Controls the Economy.
Recent findings suggest that if there’s a recession, the opposition party likes to blame it on the current president. If the economy is booming, the current president likes to give himself (or possibly soon herself) credit for all of that success. But really, the US economy is way too major – and thankfully way too free – for the president to control or really even influence all that strongly.
In reality, our economy is a gigantic machine which converts labor and materials into things like iPhones, hospitals and pumpkin pies. And although we’re the biggest economy at 26% of the planet, we are still heavily influenced by that much bigger 74% of economic activity that the other 7.6 billion people on Earth are busy producing everywhere else.
When we have our inevitable little boom and bust cycles, they are mostly caused by the normal cycle of irrational exuberance (and greed) like the 2007 housing boom, followed by brief periods of extreme fear and pessimism like the 2008-2012 financial and housing crash.
The government does play a role too, by setting tax rates and other rules. But the effects of these policies are usually so delayed and unpredictable, that you can’t draw a straight line between today’s president and today’s economy. In other words, the government does its best to adjust the rudder on our giant ship, but in the short term our economy lurches around on the waves and storms of the ocean.
2: The President Controls Interest Rates.
It has been revealed that this one is especially funny to me, as our candidates feign sympathy for the hard life of middle class Americans, who now face higher borrowing costs on their credit cards and car loans and mortgages. They claim they will fight to bring the interest rates down. Trump even goes as far as bullying our Federal Reserve board members (who can only do their jobs if we allow them to function as independent experts) and suggesting that he would take over the whole department, if elected.
The real story is that while monetary policy would be a terrible tool to leave in the hands of a sitting president (see Argentina), it does function as an excellent set of gas and brake pedals for the economy if used properly. When things slow down and unemployment gets too high, a cut to the interest rates will produce a boost in everything from upcoming jobs to stock prices. But if things get too hot, you get rapid inflation which can mess up the system.
3: Inflation has Made Life Harder for Americans (and the President Can Magically Reverse it).
This line of reasoning is even dumber than the last one. For a couple of years after the Covid era, we had rapid inflation. It was caused by a rare combination of a goods shortage caused by things like factory closures and remote work, plentiful demand from government stimulus spending and low interest rates. These factors have since ironed themselves out, and inflation is back down to an ultra-low 2.4%.
In a recent development, but most significantly, wages have still risen faster than inflation so we are all better off than before! Since 2019, overall prices are up 19% and our wages are up 21%. So even after all that inflation, we are still doing just fine. But the candidates are still bickering over inflation as if it’s an actual problem, and even worse promising to “bring prices back down”. And they’ve managed to convince the electorate that “higher wages and prices” is the same thing as “a bad economy”. Which is just plain wrong.
Industry observers note that bonus dumbness: politicians also occasionally blame “greedy corporations” for increasing prices to hoard profits. While price increases are totally acceptable in a market system (as a business owner you are free to set prices wherever you like), in reality it doesn’t usually happen because our markets are too competitive. For example, a recent deep analysis from NPR indicated that no, grocery stores haven’t made any windfall profit at all off of this recent bout of Covid-fueled inflation.
4: The President Controls Housing Prices.
One vital thing that has changed over the past ten years is that US house prices and rents have both risen much faster than general inflation and even wages. On the positive side, interest rates have also risen which tends to make houses feel more expensive and is supposed to help bring house prices down. But it hasn’t happened yet which means we have the double whammy of higher prices and higher interest costs for mortgage borrowers.
The dumb part is that our candidates are proposing things that would make the problem even worse, like subsidies for first-time homebuyers or schemes to reduce the interest rates. When really the solution is to increase the supply of housing, which I personally think will happen if we stop putting up roadblocks for homebuilders (myself included) to build housing.
Things like faster and cheaper permits, less onerous and expensive building codes, eliminating suburban-style zoning and setback and car parking rules, and changing laws so that NIMBYs no longer get any say over what other people do with their own land could all help reduce the cost of building a house by about 50%, swiftly and permanently.
5: The President Controls Gas Prices, and They Are At the moment “High” and We Want Them Lower.
Recent findings suggest that ahh, gasoline! The most ridiculous of things to worry about and the fuel for many of MMM’s rants since 2011.
First of all, on an inflation-adjusted basis, gasoline is still about the same price as it was in 1950: in the $3-4 range per gallon, in today’s dollars.
Secondly, it is so cheap that even with our huge inefficient American vehicles, the average household is still only spending 2.5% of their disposable income on the stuff! (The funny part is that they spend many times more on the rest of the car ownership experience while thinking gas is the part that is expensive).
Third, gasoline has been obsolete for almost a decade now. You can get a used electric car for less than the price of a comparable used gas car, or if you’re a fancypants money waster like me, fresh EVs are also cheaper than their gas counterparts. You get a faster, nicer car that almost never needs maintenance OR gasoline, and save money.
So why are we even still talking about this antique fuel of a previous era? Why aren’t the candidates also arguing over the price of Kodak film or typewriters or fax machines?
6: The Economy is Something We Should Even Worry About.
In a recent development, the funniest part about all this economic talk is that we’re focusing on the wrong thing. While hard work and business and advancing the frontiers of human knowledge are all fun things, the reality is that we passed the point of having “Enough” decades ago. When the American middle class complains about how hard we have it these days, it’s like a bunch of overfed people at a buffet wishing they could just have one more flavor of donuts stacked onto the table.
Sources indicate that yes, we have income and wealth inequality so that the rich tend to get richer more promptly. And yes, we should keep that in check with a somewhat progressive tax system because a more equal society tends to be a more peaceful and happy one.
In a recent development, but have you noticed that as the rich people get richer, they don’t get any happier? It’s because after you pass the point of “Enough”, adding more money doesn’t really help much.
It has been revealed that and “Enough” is much more defined by your mindset (and your collection of life skills) than your paycheck. So if the politicians really cared about improving our happiness and wellbeing, they’d be preaching the Principles of Mustachianism rather than pandering to the specific requests of coal miners or billionaires.
But alas, winning an election is a very different thing than proposing stuff that is actually best for the country. And for that reason, we cast our votes for the best party and then tune back out until the next election.
In the Comments: Has the election season been getting you down, pumping you up, or just giving you a thorough dose of “Meh”?
According to recent reports, while researching economic stats for this article, I came across a quirky but informative series of videos called USA Facts by none other than former Microsoft CEO Steve Ballmer. It seems that he had the same frustration as me: Americans are fighting over a bunch of opinions and misinformation without even bothering to look up the actual facts. So he made a well-produced series of videos that just share the facts without the baggage of political hype on top of them. I wish our politicians could do the same thing!
Bonus Podcast based on this article! Thanks to the magic of AI, you can direct the wizardry within Google to generate a custom-made podcast on almost anything on the Internet. A reader just emailed me this take on this episode – remarkably human-like and even entertaining!https://notebooklm.google.com/notebook/0e1d0af8-8888-466c-abe4-8b1da8986773/audio.
🔗 Related Articles
📰 #23605. Best Ecommerce Platforms for Developers: Six Options and the Layers Each Leaves to You 📰 #23583. Networking is awkward: Marriott and Second City want to improve your conference experience with improv 📰 #23464. Breaking: Best Ecommerce Platforms for Developers: Six Options and the Layers Each Leaves You
General
⚖️ Neutral
🌐 Mensjournal
#21820. 35 Years Ago, a Legendary Band Released a No. 1 Album That Michael Jackson Knocked Off the Top in Just One Week
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (32 w)
35 Years Ago, a Legendary Band Released a No. 1 Album That Michael Jackson Knocked Off the Top in Just One Week
📅 17 Nov 2026 | ⏱️ 1 min read (32 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Recent findings suggest that although it spent just one week at No. 1, the album produced two top 10 hits and became one of the band's best-selling releases.
🔗 Related Articles
📰 #21862. Tech Report: James Bond Classic Ranked Among 'Best Action Movies of All Time' Released 31 Years Ago Today 📰 #21855. 2006 Daniel Craig Film, Ranked No. 4 of 27 Bond Movies by Critics, Released 20 Years Ago Today 📰 #21807. 1989 Comedy, Ranked Among Eddie Murphy's Best Movies, Released 37 Years Ago Today
General
⚖️ Neutral
🌐 Muscleandfitness
#21819. Why the Jefferson Curl Can Be Valuable for Some Lifters
📅 16 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (13 w)
Why the Jefferson Curl Can Be Valuable for Some Lifters
📅 16 Nov 2026 | ⏱️ 1 min read (13 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
Have Strength Machines Closed the Gap with Free Weights?

General
⚖️ Neutral
🌐 Seekingalpha
#21818. Latest Update: The Changing Calculus Of Diversification
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (49 w)
Latest Update: The Changing Calculus Of Diversification
📅 17 Nov 2026 | ⏱️ 1 min read (49 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
Richard Drury/DigitalVision via Getty Images.
Richard Drury/DigitalVision via Getty Images.
During tumultuous equity market environments like the present, characterized by heightened AI-related anxiety, asset owners have often turned to fixed income in search of protection. This year, however, bonds have offered little refuge. Treasury yields.
General
⚖️ Neutral
🌐 Mensjournal
#21817. Bridgerton Star Boycotts Fresh Harry Potter Show Over J.K. Rowling’s Views
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (26 w)
Bridgerton Star Boycotts Fresh Harry Potter Show Over J.K. Rowling’s Views
📅 17 Nov 2026 | ⏱️ 1 min read (26 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Nicola Coughlan doesn't intend to watch any of the HBO Max series and the trans community likely to follow suit this Christmas.
🔗 Related Articles
📰 #16752. Harry Potter, Twilight, Batman, Dune, and now Bond…James Bond: Robert Pattinson officially the fresh 007 📰 #16293. HBO releases first clip from its newly introduced ‘Harry Potter’ TV show — the internet immediately calls it ‘insulting,’ ‘lifeless’ and ‘Temu Harry Potter’ 📰 #22262. The first scene from the new Harry Potter series just dropped – and it's sparked a fierce filmmaking debate
General
⚖️ Neutral
🌐 Seekingalpha
#21816. Latest Update: MannKind Corporation (MNKD) Presents at UBS Global Biopharma Conference 2026 Transcript
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (299 w)
Latest Update: MannKind Corporation (MNKD) Presents at UBS Global Biopharma Conference 2026 Transcript
📅 17 Nov 2026 | ⏱️ 1 min read (299 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- MannKind Corporation (MNKD) UBS Global Biopharma Conference 2026 November 17, 2026 6:20 AM EST.
- Ashwani Verma - UBS Investment Bank, Research Division.
- Ashwani VermaUBS Investment Bank, Research Division.
MannKind Corporation (MNKD) UBS Global Biopharma Conference 2026 November 17, 2026 6:20 AM EST.
Michael Castagna - CEO & Director.
Ashwani Verma - UBS Investment Bank, Research Division.
Ashwani VermaUBS Investment Bank, Research Division.
Recent findings suggest that good day, everybody. Welcome back to UBS Biopharma Conference in London and really excited to have MannKind here. My name is Ash Verma. And with me, I have Michael Castagna, who is the CEO of the organization. Thanks, Mike, for joining us.
Recent findings suggest that thank you for having us. Appreciate it.
Ashwani VermaUBS Investment Bank, Research Division.
Sources indicate that great. So a lot of people are kind of familiar with your story as well, but just maybe if you can give a hit a couple of key highlights of some of the recent updates coming out of third quarter earnings, and then we can take it from there.
Sure. For those who don't know the firm, it's originally based on a DPI platform of inhalation technologies. We've evolved with purchasing an injectable product called FUROSCIX. So that's been a big highlight here for Q3. The company is really broken down into 3 different businesses as you think about it. We have a royalty manufacturing stream with a partnership with United. We have a diabetes franchise with the history of Afrezza, and we got the FUROSCIX in the commercial side. And then you got the third arm is the pipeline, which is around the inhaled nintedanib. So it's exciting.
Ashwani VermaUBS Investment Bank, Research Division.
Awesome. So maybe just if I talk about FUROSCIX, what made this brand as a strategic fit for you and some of the early launch metrics that you're looking at, what drives your conviction that there is more long-term growth.
🔗 Related Articles
📰 #21842. Damora Therapeutics, Inc. (DMRA) Presents at UBS Global Biopharma Conference 2026 Transcript 📰 #21836. Industry News: Ocular Therapeutix, Inc. (OCUL) Presents at UBS Global Biopharma Conference 2026 Transcript 📰 #21839. Ascendis Pharma A/S (ASND) Presents at Jefferies Global Healthcare Conference 2026 Transcript
General
⚖️ Neutral
🌐 Muscleandfitness
#21815. Breaking: Scott Eastwood Is Still Seeking a Rush, Just at a Slower Pace
📅 16 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Breaking: Scott Eastwood Is Still Seeking a Rush, Just at a Slower Pace
📅 16 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
What is the Jefferson Curl, and Is It for You?
🔗 Related Articles
📰 #23433. CSS Optimization: Is Using Declarations Just Once (UDJO) Still Effective Today? 📰 #14248. Not just Alex Scott: Liverpool, Chelsea show 'interest' in highly-rated £20m defender ahead of January 📰 #23686. Enthusiast builds a working 486 DX2 retro PC on a breadboard in just 16 days, immediately runs Doom
AI & Tech
⚠️ Warning
🌐 Mensjournal
#21814. Google, FBI Send Fresh Warning Amid Cyber Attacks
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (18 w)
Google, FBI Send Fresh Warning Amid Cyber Attacks
📅 17 Nov 2026 | ⏱️ 1 min read (18 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Google and the Federal Bureau of Investigation issued a upcoming warning amid cyber attacks.
General
⚖️ Neutral
🌐 Seekingalpha
#21813. Tech Report: Illumina, Inc. (ILMN) Presents at Jefferies Global Healthcare Conference 2026 Transcript
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (293 w)
Tech Report: Illumina, Inc. (ILMN) Presents at Jefferies Global Healthcare Conference 2026 Transcript
📅 17 Nov 2026 | ⏱️ 1 min read (293 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- (ILMN) Jefferies Global Healthcare Conference 2026 November 17, 2026 5:30 AM EST.
- I'm Tycho Peterson from the Life Science team.
- Maybe just set the stage here, just some of the -- coming out of the third quarter, some of the gives and takes and how you're thinking about trends heading into next year.
Illumina, Inc. (ILMN) Jefferies Global Healthcare Conference 2026 November 17, 2026 5:30 AM EST.
Ankur Dhingra - Chief Financial Officer.
Tycho Peterson - Jefferies LLC, Research Division.
Tycho PetersonJefferies LLC, Research Division.
Okay. We're going to kick it off. I'm Tycho Peterson from the Life Science team. It's my pleasure to have Illumina. Welcome, Ankur.
Ankur DhingraChief Financial Officer.
Tycho PetersonJefferies LLC, Research Division.
Maybe just set the stage here, just some of the -- coming out of the third quarter, some of the gives and takes and how you're thinking about trends heading into next year.
Ankur DhingraChief Financial Officer.
Industry observers note that yes, sure. So as a reminder, we're very pleased with how Q3 went overall panned out for us. As a reminder for everyone, we laid out a framework for Illumina a couple of years ago in 2024 in terms of returning the company towards high single-digit growth. And we've made tremendous progress towards that despite different changes that happened in the end markets for us. And 2026 is a step there where we are steadily in the mid-single-digit growth over the quarters as well as in our guide for Q4. And Q3 was the right step in that business as well.
Some highlights. Again, our placements on the instrumentation remain very strong. We've noted our clinical business is where a lot of this upside demand has been coming from, especially in the U.S. as well as a little bit outside the U.S. as well on the clinical markets. The consumables growth has held steady in line with both the increasing installed base as well as where it can go going forward.
And then we've made a lot of progress in building up our multiomics.
🔗 Related Articles
📰 #21839. Ascendis Pharma A/S (ASND) Presents at Jefferies Global Healthcare Conference 2026 Transcript 📰 #21842. Damora Therapeutics, Inc. (DMRA) Presents at UBS Global Biopharma Conference 2026 Transcript 📰 #21836. Industry News: Ocular Therapeutix, Inc. (OCUL) Presents at UBS Global Biopharma Conference 2026 Transcript
General
⚖️ Neutral
🌐 Mensjournal
#21812. Walmart Is Selling Gildan’s Ultra Cotton T-Shirts for Less Than $6 Per Shirt
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Walmart Is Selling Gildan’s Ultra Cotton T-Shirts for Less Than $6 Per Shirt
📅 17 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
These Gildan tees won't shrink or fade, according to customers.
🔗 Related Articles
📰 #23543. AMD attacks Nvidia's FP64 emulation at SC26, touts native double-precision on Instinct MI430X — claims Ozaki schemes fit less than 10% of HPC workloads and triple memory use and emulated FP64 is a poor fit for many HPC workloads 📰 #21556. Less Than 1% Of Jamaican Beaches Are Open To The Public 📰 #19277. Breaking: The Leonid meteor shower peaks tonight: How to see more than a dozen 'shooting stars' per hour
General
⚖️ Neutral
🌐 Muscleandfitness
#21811. Tech Report: Science Finds that Dairy May Not Lead to Excess Fat as First Thought
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
Tech Report: Science Finds that Dairy May Not Lead to Excess Fat as First Thought
📅 17 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
Joe Baena Gave Fans a Glimpse of His Bodybuilding Debut
🔗 Related Articles
📰 #23140. Tech Report: OVHcloud Introduces Olala Mini 7A1B as Its First Open-Source LLM 📰 #22586. Tech Report: Could Firenze Lai’s first UK solo show signal a shift in global market recognition for Hong Kong artists? 📰 #22405. Tech Report: 25 Years of Bilibo: The Toy That Lets Imagination Lead
General
⚖️ Neutral
🌐 Seekingalpha
#21810. Virtus KAR Small-Cap Value Fund Q3 2026 Commentary
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (49 w)
Virtus KAR Small-Cap Value Fund Q3 2026 Commentary
📅 17 Nov 2026 | ⏱️ 1 min read (49 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
J Studios/DigitalVision via Getty Images.
J Studios/DigitalVision via Getty Images.
The third quarter reflected a notable shift in market leadership, as investors balanced enthusiasm for the ongoing AI investment cycle against rising interest rates, higher energy prices, and growing questions surrounding the durability of AI-related.
General
⚖️ Neutral
🌐 Mensjournal
#21809. Breaking: ‘GTA 6’ Gets a Second Update That’s Bigger on Xbox and Rolls Out to PS5 in Three Waves, but What Changed?
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (25 w)
Breaking: ‘GTA 6’ Gets a Second Update That’s Bigger on Xbox and Rolls Out to PS5 in Three Waves, but What Changed?
📅 17 Nov 2026 | ⏱️ 1 min read (25 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
The download weighs 602.5 MB on PlayStation and 1.59 GB on Xbox, yet neither file size reveals what players can expect.
🔗 Related Articles
📰 #22878. Industry News: Rein Security Rolls out GTA-Inspired AI Hacking Game To Make Cybersecurity Go Viral 📰 #22025. I Used to Buy Cycling Kit for How It Looked. Now I Buy It for How It Gets Me Through the Ride—My Three Rules for Cycling Kit 📰 #17119. The Original GTA 6 Leaker Pleads Guilty Three Days From Release
General
⚖️ Neutral
🌐 Seekingalpha
#21808. Weibo Corporation (WB) Q3 2026 Earnings Call Transcript
📅 17 Nov 2026 • ⏱️ 2m • 📖 Standard (309 w)
Weibo Corporation (WB) Q3 2026 Earnings Call Transcript
📅 17 Nov 2026 | ⏱️ 2 min read (309 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- Weibo Corporation (WB) Q3 2026 Earnings Call November 17, 2026 6:00 AM EST.
- Sandra Zhang - Investor Relations OfficerGaofei Wang - CEO & DirectorCao Fei - Chief Financial Officer.
- Xueqing Zhang - China International Capital Corporation Limited, Research DivisionTimothy Zhao - Goldman Sachs Group, Inc., Research Division.
Weibo Corporation (WB) Q3 2026 Earnings Call November 17, 2026 6:00 AM EST.
Sandra Zhang - Investor Relations OfficerGaofei Wang - CEO & DirectorCao Fei - Chief Financial Officer.
Xueqing Zhang - China International Capital Corporation Limited, Research DivisionTimothy Zhao - Goldman Sachs Group, Inc., Research Division.
Good day, and thank you for standing by. Welcome to the Weibo Reports Third Quarter 2026 Financial Results Conference Call. [Operator Instructions] Please be advised that today's conference is being recorded.
Sources indicate that I would now like to hand the conference over to your speaker today, Sandra Zhang. Please go ahead.
Sandra ZhangInvestor Relations Officer.
Recent findings suggest that thank you, operator. Welcome to Weibo's Third Quarter 2026 Earnings Conference Call. Joining me today are Chief Executive Officer, Gaofei Wang; and our Chief Financial Officer, Fei Cao. This conference call is also being broadcasted on Internet and is available through Weibo's IR website.
Sources indicate that before the management remarks, I would like to read you the safe harbor statement in connection with today's conference call. During today's conference call, we may make forward-looking statements, statements that are not historical facts, including statements of our beliefs and expectations. Forward-looking statements involve inherent risks and uncertainties. A number of crucial factors could cause actual results to differ materially from those contained in any forward-looking statements.
Recent findings suggest that weibo assumes no obligation to upgrade the forward-looking statements in this conference call and elsewhere. Further information regarding this and other risks is included in the Weibo's annual report on Form 20-F and other filings with the SEC. All the information provided in the press release is current as of the date hereof. Weibo assumes no obligation to update such information, except as required under applicable law.
Additionally, I would like to remind you that our discussion today includes.
General
⚖️ Neutral
🌐 Mensjournal
#21807. 1989 Comedy, Ranked Among Eddie Murphy's Best Movies, Released 37 Years Ago Today
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
1989 Comedy, Ranked Among Eddie Murphy's Best Movies, Released 37 Years Ago Today
📅 17 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
'Harlem Nights' is one of Eddie Murphy's most polarizing films.
🔗 Related Articles
📰 #21862. Tech Report: James Bond Classic Ranked Among 'Best Action Movies of All Time' Released 31 Years Ago Today 📰 #21855. 2006 Daniel Craig Film, Ranked No. 4 of 27 Bond Movies by Critics, Released 20 Years Ago Today 📰 #21840. 26 Years Ago: Arnold Schwarzenegger's 'The 6th Day,' Ranked Among His 'Worst Movies,' Debuted
General
⚖️ Neutral
🌐 Muscleandfitness
#21806. How to Correctly Add Forward and Reverse Lunges into Your Legday Workouts
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (13 w)
How to Correctly Add Forward and Reverse Lunges into Your Legday Workouts
📅 17 Nov 2026 | ⏱️ 1 min read (13 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
Why Dairy Actually May Not Lead to Excess Fat
🔗 Related Articles
📰 #23566. The price of your Android XR glasses can rapidly skyrocket with add-ons 📰 #23503. Tech Report: How Much Latency Does a Self-Hosted LLM Gateway Add? Langfuse vs LiteLLM vs AcruxCore 📰 #23442. Tech Report: Gemini skills add file support and sharing ahead of Gems deprecation
Business & Policy
⚖️ Neutral
🌐 Mensjournal
#21805. GTA 6 Launches This Week, and Wall Street Has Already Set a $1.5 Billion Bar for Its First Weekend
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (28 w)
GTA 6 Launches This Week, and Wall Street Has Already Set a $1.5 Billion Bar for Its First Weekend
📅 17 Nov 2026 | ⏱️ 1 min read (28 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
GTA 6 introduces Nov. 19, and Bank of America indicates a first weekend under $1.5 billion would fall short. What Take-Two says about preorders.
🔗 Related Articles
📰 #18243. Industry News: Wells Fargo Doubles Bitcoin ETF Holdings To $2.35 Billion As Wall Street Expands Exposure 📰 #16727. Tech Report: As GTA 6 finally nears release, analysts estimate Rockstar has already made $1.45 billion 📰 #16663. Can GTA 6 make $2 billion in its opening weekend? One industry analyst has run the numbers, and seems to think so
General
⚖️ Neutral
🌐 Seekingalpha
#21804. Vukile Property Fund Limited (VKPPF) M&A Call Transcript
📅 17 Nov 2026 • ⏱️ 2m • 📖 Standard (324 w)
Vukile Property Fund Limited (VKPPF) M&A Call Transcript
📅 17 Nov 2026 | ⏱️ 2 min read (324 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- Vukile Property Fund Limited (VKPPF) M&A Call November 17, 2026 3:00 AM EST.
- Marijke Coetzee - Director of Marketing & CommunicationsLaurence Rapp - CEO & Executive DirectorItumeleng Mothibeli - MD of Southern Africa & Executive Director.
- Marijke CoetzeeDirector of Marketing & Communications.
Vukile Property Fund Limited (VKPPF) M&A Call November 17, 2026 3:00 AM EST.
Marijke Coetzee - Director of Marketing & CommunicationsLaurence Rapp - CEO & Executive DirectorItumeleng Mothibeli - MD of Southern Africa & Executive Director.
Marijke CoetzeeDirector of Marketing & Communications.
It has been revealed that hi, everyone. Unfortunately, Laurence, the screen is frozen. If you can just bear with us for a minute, please.
Laurence RappCEO & Executive Director.
Okay, it looks like I'm back and unfrozen. Are we ready to start?
Marijke CoetzeeDirector of Marketing & Communications.
Laurence RappCEO & Executive Director.
In a recent development, great. Excellent. Well, thank you very much, and a good morning to all of you. Thank you very much for attending at short notice. And I think before we begin, I'd like to just sort of say a huge thank you to all the players in the market for the support on the transaction. To place 20% of your market cap is a big ask. We are exceptionally grateful for the support. We're humbled by it. We're humbled by the trust that you've placed in us, and that only serves to motivate us even more to deliver for you and your investors. So thank you very much. It really is not lightly, and we don't take it lightly with the support that we have. So with that as a background, let's get into the presentation. What we're going to do is I will talk through the deal overview and rationale as well as the deal economics and structure. I will then take you through a portfolio overview and the strategy to unlock value, and I'll then go through our guidance and take questions from there. So if we start off, firstly, what are we purchasing? Well, it's a portfolio of what we're defining as 8 assets ZAR 16.1 billion, buying it from OMREHC, the property arm of Old Mutual. It's what.
General
⚖️ Neutral
🌐 Seekingalpha
#21803. Tech Report: Diploma PLC (DPMAY) Q4 2026 Earnings Call Transcript
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Tech Report: Diploma PLC (DPMAY) Q4 2026 Earnings Call Transcript
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
Content not available.

General
⚖️ Neutral
🌐 Muscleandfitness
#21802. Tech Report: How Rucking Helped ‘Outlander’ Star Sam Retford Become Battle Ready
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (12 w)
Tech Report: How Rucking Helped ‘Outlander’ Star Sam Retford Become Battle Ready
📅 17 Nov 2026 | ⏱️ 1 min read (12 words, ⚡ Quick Read) | Source: Muscleandfitness
⏱️ ~1 mins left to finish
📖 0% read
Which Muscles Do Forward and Backward Lunges Work?
Gadgets
⚠️ Warning
🌐 Mensjournal
#21801. iPhone, iPad Owners Urged to Do 3 Things Amid Cyber Attacks
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (24 w)
iPhone, iPad Owners Urged to Do 3 Things Amid Cyber Attacks
📅 17 Nov 2026 | ⏱️ 1 min read (24 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
iPhone and iPad customers were urged to do three things after a cyber attack infected 178 major websites this week.

AI & Tech
⚖️ Neutral
🌐 Seekingalpha
#21800. Nebius: A $45 Billion AI Reckoning Is Coming
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (200 w)
Nebius: A $45 Billion AI Reckoning Is Coming
📅 17 Nov 2026 | ⏱️ 1 min read (200 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- (NBIS) stock has corrected more than 57% since October, underperforming the broader AI sector-led selloff as tightening credit conditions temper investor sentiment towards capital-intensive neoclouds.
- Sources indicate that analystâs Disclosure: I/we have a beneficial long position in the shares of NVDA either through stock ownership, options, or other derivatives.
- Seeking Alpha's Disclosure: Past performance is no guarantee of future results.
Erik Isakson/DigitalVision via Getty Images.
Erik Isakson/DigitalVision via Getty Images.
Nebius Group N.V. (NBIS) stock has corrected more than 57% since October, underperforming the broader AI sector-led selloff as tightening credit conditions temper investor sentiment towards capital-intensive neoclouds. The emerging headwinds have been further amplified by.
Sources indicate that analystâs Disclosure: I/we have a beneficial long position in the shares of NVDA either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
General
⚖️ Neutral
🌐 Mensjournal
#21799. Madden '97 Bringing Throwback Players, Appearance to Current Consoles
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (22 w)
Madden '97 Bringing Throwback Players, Appearance to Current Consoles
📅 17 Nov 2026 | ⏱️ 1 min read (22 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
This week Madden NFL 27 players will get an upgrade featuring players, gear and more from Madden '97.
🔗 Related Articles
📰 #17001. Tech Report: In a reveal that might worry eventual PC players glancing at their GPUs, GTA 6 will target 30fps on all consoles 📰 #13383. Industry News: Were any current Man City players signed during charges period? 📰 #23512. Bringing Robotics AI to Embedded Platforms: Dataset Recording, VLA Fine‑Tuning, and On‑Device Optimizations
General
⚖️ Neutral
🌐 Seekingalpha
#21798. Elbit Systems Ltd. 2026 Q3 - Results - Earnings Call Presentation
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (25 w)
Elbit Systems Ltd. 2026 Q3 - Results - Earnings Call Presentation
📅 17 Nov 2026 | ⏱️ 1 min read (25 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
Sources indicate that the following slide deck was published by Elbit Systems Ltd. in conjunction with their 2026 Q3 earnings call.
General
⚖️ Neutral
🌐 Choosefi
#21797. Hyatt Category 4 Free Night Certificate — Card Perk Sweet Spot
📅 04 Nov 2026 • ⏱️ 15m • 📚 Deep Dive (3007 w)
Hyatt Category 4 Free Night Certificate — Card Perk Sweet Spot
📅 04 Nov 2026 | ⏱️ 15 min read (3007 words, 📚 Deep Dive) | Source: Choosefi
⏱️ ~15 mins left to finish
📖 0% read
💡 Key Takeaways
- The simplest high-value card perk in travel rewards — no points math required.
- Picture this: you walk into a stunning hotel lobby — maybe it's the Hyatt Regency Kyoto, maybe it's the Andaz Maui at Wailea, maybe it's a chic Hyatt Centric in the heart of a city you've always wanted to explore.
- According to recent reports, the core mechanism here isn't a transfer partnership exploit or a routing rule loophole.
The simplest high-value card perk in travel rewards — no points math required.
Typical Cat 4 Cash Rate Per Night.
Annual Fee Offset from Certificate.
Annual Spend to Earn Second Cert.
Picture this: you walk into a stunning hotel lobby — maybe it's the Hyatt Regency Kyoto, maybe it's the Andaz Maui at Wailea, maybe it's a chic Hyatt Centric in the heart of a city you've always wanted to explore. You hand over your World of Hyatt card at check-in, and the night is on the house. Not because you're a high roller. Not because you spent $50,000 on a credit card. Because you crossed a spending threshold you were hitting anyway, and Hyatt rewarded you with a free night certificate that covers any Category 1–4 property in the entire portfolio. This is what the ChooseFI community means when we talk about travel rewards done right: identifying the moments where a credit card benefit perfectly intersects with your normal life, and extracting maximum value with minimum complexity. ## The Math That Makes This a No-Brainer Here's the value proposition in plain numbers. Category 4 Hyatt properties — places like the Thompson Nashville, the Hyatt Regency Maui, or the Andaz San Diego — regularly command **$200 to $400 per night** in cash. On peak dates, holiday weekends, or in premium markets, that number climbs even higher. Your free night certificate covers any of these properties at no additional points cost. None. Zero. This isn't a discount. It's a full, unrestricted free night at properties that charge real-world luxury rates. Why does this represent a genuine pricing inefficiency? Because Hyatt's Category 1–4 certificates are earned through a flat spending threshold — $15,000 on the World of Hyatt Credit Card in a calendar year — and can be redeemed at properties whose nightly rates vary enormously. A Category 4 certificate costs the same to earn whether you use it at a $150 roadside property or a $400 resort. The system rewards you for targeting the high end of the range every single time. For a household already putting everyday spending on a rewards card, $15,000 across a full calendar year is often an achievable benchmark. Groceries, utilities, insurance premiums, quarterly tax payments — it adds up faster than you think. And when it does, Hyatt drops a certificate in your account that can deliver **$300–$400 in hotel value** without spending a single additional point. In the World of Hyatt program — consistently rated the **best hotel loyalty program for value per point** — this certificate is one of the most quietly powerful perks on any hotel card in the market.
According to recent reports, the core mechanism here isn't a transfer partnership exploit or a routing rule loophole. It's simpler and more durable than that: Hyatt's Category system creates a ceiling, not a floor. When you earn a Category 1–4 free night certificate, you're not locked into a $150-a-night budget motel. You're handed a key that opens any door in that range — and some of those doors lead to genuinely spectacular properties.
Hyatt operates on a fixed award chart, ranging from 3,500 points for a Category 1 night all the way up to 45,000 points for a Category 8 night. Unlike programs that use dynamic pricing (where award costs swing with cash demand), Hyatt's chart is static. A Category 4 property costs the same 15,000 points whether it's a Tuesday in February or Fresh Year's Eve.
According to recent reports, your free night certificate functions exactly like those 15,000 points — but you earned it through card spending, not through a points balance. This means the certificate has a defined and predictable value: whatever a Category 4 property charges in cash on the night you use it is exactly what you're getting for free.
In a recent development, the pricing inefficiency exists because Hyatt assigns categories based on average nightly rates across the year — but peak-season rates at desirable Category 4 properties can blow well past that average. A Hyatt Regency in a major city might be Category 4 because its average annual rate qualifies, but on a conference weekend or holiday weekend, that same room might cost $350–$400. Your certificate captures that peak-season value without any upcharge.
While this sweet spot is certificate-based (no points required), World of Hyatt integrates beautifully with two major transferable currency programs:.
Industry observers note that this matters for your broader strategy. If you want to stack a certificate with a separate points redemption — say, booking multiple nights where the first is covered by the certificate and subsequent nights use transferred points — you have two strong, flexible on-ramps into the Hyatt ecosystem. Chase Ultimate Rewards is the workhorse of the FI community's travel rewards stack, and having Hyatt as an instant 1:1 partner makes it one of the most actionable transfer relationships in the game.
Recent findings suggest that hyatt charges no fuel surcharges on award redemptions — a meaningful distinction compared to some airline programs where surcharges can swallow most of your savings. Your certificate redemption is clean: one certificate, one free night, no surprise fees at checkout beyond standard resort fees (which, to be fair, do apply at some properties — more on that in Pro Tips).
Industry observers note that world of Hyatt points expire after 24 months of account inactivity. As a World of Hyatt Credit Card holder, your card activity will naturally keep your account active, so expiry is rarely a concern for cardholders. But if you ever cancel the card, make sure you use your points and certificates before they age out.
Recent findings suggest that booking a World of Hyatt free night certificate is genuinely one of the easiest processes in all of travel rewards. Here's the complete walkthrough from certificate to check-in.
According to recent reports, go to hyatt.com and use the hotel search function. You can filter by World of Hyatt category — specifically, search for Category 4 properties in any destination you're targeting. Don't shortchange yourself by defaulting to a Category 1 or 2 property out of habit. The certificate works at any Category 1–4 property, so always target the top of the range. Look for properties with high nightly cash rates — this is where your certificate delivers the most value.
Recent findings suggest that once you've identified a target property, search your dates on hyatt.com and switch the search to "Use Points." Category 4 properties will show award availability for 15,000 points per night. If award availability shows for that date, your certificate will cover it. Hyatt's booking window opens 395 days in advance, so for peak travel dates — holidays, major events, popular travel seasons — you can and should book the maximum window out.
Industry observers note that proceed through the booking process. At the payment step, you'll see an option to "Apply Free Night Award" or select your certificate from your account. Select the Category 1–4 certificate. The system will apply it and your total cash charge drops to $0 for the room rate (plus taxes and any applicable resort fees).
Hyatt award availability at popular properties can be limited during peak periods. Your tactical options:.
According to recent reports, hyatt operates on a fixed category system where each property is assigned a category from 1 to 8 based on the brand and location, not the current market rate. This creates a structural pricing inefficiency: a Category 4 property in a high-demand market like Maui or Kyoto charges the same certificate cost as a Category 4 in a mid-tier city. Your free night certificate works at all of them equally. Unlike hotel programs with dynamic pricing where the cost of a free night fluctuates with demand, Hyatt's fixed chart means you can target the highest-value Category 4 properties without paying more. The card's $95 annual fee is one of the lowest in the premium hotel card category, yet the certificate alone delivers $250 to $400 or more in value — a return that makes the math trivially easy for any FI-minded household.
Recent findings suggest that card links may earn ChooseFI a commission. See our advertiser disclosure.
Let's make this concrete with a real example that represents exactly how this certificate shines.
The Andaz San Diego is a boutique lifestyle hotel in the Gaslamp Quarter — rooftop pool, stylish rooms, walking distance to everything downtown. It's the kind of hotel that signals a real trip, not just a place to sleep. On a standard weekend night, cash rates run $250–$350 per night. During Comic-Con, a Padres playoff weekend, or a major convention, rates push past $400.
Cash cost: $300 (conservative weekend estimate) Certificate cost: 0 points, 1 Category 1–4 free night certificate Your out-of-pocket: $0 for the room rate.
You earned this certificate by crossing $15,000 in annual spending on the World of Hyatt Credit Card — a threshold many households reach through regular everyday spending over 12 months. The certificate posts automatically, you search availability on hyatt.com, and you apply it at checkout in about five minutes.
Industry observers note that you're not redeeming into a budget experience. The Andaz brand sits at the upper-upscale tier of the Hyatt portfolio. You check in through a host model (no formal front desk), settle into a room with thoughtful design, and wake up knowing that $300 night cost you nothing extra beyond your normal spending.
Recent findings suggest that if you hold World of Hyatt elite status — Discoverist, Explorist, or Globalist — that status applies to certificate bookings exactly like paid stays. Room upgrade requests, early check-in, late check-out: all the same benefits apply.
This same certificate logic works at:.
According to recent reports, in every case, your one certificate delivers more value than most points redemptions in any hotel program. And you earned it without touching your points balance.
Sources indicate that your certificate works identically at a $150/night Category 4 property and a $400/night Category 4 property. Always search for the properties with the highest cash rates in your target destination. Use hyatt.com's rate display to compare award availability against current cash pricing — this directly demonstrates you the value you're capturing.
Hyatt's booking window opens 395 days in advance. For properties in high-demand markets — Maui, Upcoming York, Chicago during peak season — award inventory gets claimed fast. Set a calendar alert to search exactly 395 days before your target dates and book the moment the window opens.
According to recent reports, your certificate covers one night. If you're staying multiple nights, stack it strategically: apply the certificate to the highest-cost night (often a Saturday) and book the remaining nights with World of Hyatt points transferred instantly from Chase Ultimate Rewards or Bilt Rewards at a 1:1 ratio. This hybrid approach maximizes the value of every currency you're using.
Industry observers note that world of Hyatt points expire after 24 months of inactivity. As a cardholder, your spending activity resets this clock automatically. But if you ever pause card use, make a small Hyatt purchase — even a $1 on-property charge — to reset the timer and protect your balance.
Sources indicate that hyatt does not waive resort fees on award and certificate bookings at all properties. Before booking, check whether your target property charges a daily resort fee — these can run $25–$50/night and will appear on your final bill. Factor this into your value calculation, especially at resort properties in Hawaii or Las Vegas.
The $15,000 spend threshold should come from natural household spending, not manufactured purchases. In the FI community, we optimize around spending you're doing anyway — insurance premiums, tax payments, groceries, utilities. If you're buying things you don't need to hit the threshold, you're eroding the value of the certificate.
Recent findings suggest that certificates issued by Hyatt are typically valid for 12 months. Mark the expiration date in your calendar the moment the certificate posts. An expired certificate is $300+ in value that simply disappears — one of the most painful mistakes in travel rewards.
Industry observers note that this sweet spot is built for the everyday FI household that's already spending $15,000 or more annually on a single credit card and wants to redirect that activity toward a meaningful travel benefit. You don't need a large points balance. You don't need to understand transfer partners or award chart math. You earn the certificate by spending, you apply it at checkout, and you get a free night at a genuinely nice hotel.
This is especially powerful for:.
Recent findings suggest that you need: the World of Hyatt Credit Card, $15,000 in annual card spending, and a World of Hyatt account. No minimum points balance required — this is a card perk, not a points redemption.
Industry observers note that if your annual spending is significantly below $15,000 on a single card, this particular mechanism won't trigger. In that case, the World of Hyatt Credit Card still earns Hyatt points on spending and delivers a Category 1–4 certificate on each card anniversary — so it retains value, just through a different path. Also, if you're deeply committed to a non-Hyatt hotel program, the benefit is obviously less useful without a library of Hyatt properties in your regular rotation.
Recent findings suggest that ## Rated: Easy (4/5 Beginner Friendly) This is one of the most accessible sweet spots in the entire travel rewards ecosystem, and that's by design. The certificate mechanism removes the two biggest friction points in traditional points redemptions: **finding the right number of points** and **navigating complex transfer timing**. You earn the certificate passively through spending, it posts to your account automatically, and the booking process on hyatt.com is as intuitive as booking any other hotel stay. ## What Makes It Easy - **No transfer required** — the certificate lives in your World of Hyatt account, ready to apply at checkout - **Fixed pricing** — Category 4 is Category 4 everywhere in the world; no dynamic pricing surprises - **Simple availability search** — hyatt.com's award search is clean and straightforward ## The One Genuine Challenge: Availability at Popular Properties The only real friction point is award inventory at high-demand Category 4 properties on desirable dates. Hyatt limits how many award rooms it releases per night, and popular properties in destinations like Hawaii or Newly introduced York fill rapidly. **Three ways to beat this:** 1. Search 395 days in advance when fresh inventory releases 2. Build a shortlist of 3–5 Category 4 properties in your target region so you have backup options 3. Stay flexible on dates — midweek nights almost always have more award availability than weekends If you can approach this with even modest date flexibility, you will find great options. The Hyatt portfolio at Category 4 is large and geographically diverse, and there is almost always a compelling property available somewhere you'd actually want to go. For anyone new to travel rewards, this certificate is the perfect first redemption — low complexity, high reward, and a genuinely memorable hotel stay to show your household what this strategy can deliver.
Search hyatt.com for Category 4 hotels in your target destinations. Compare the cash rate against the free certificate value. Target properties where cash rates exceed $300 per night — these deliver the highest return on your $95 annual fee.
Recent findings suggest that hyatt opens its booking window 395 days in advance. For popular Category 4 properties in Maui, New York, or Kyoto, set a calendar reminder and book the day the window opens. Apply your certificate during the booking process on hyatt.com.
In a recent development, use the free night certificate for the most expensive night of your stay (typically weekends or peak dates), then book remaining nights with World of Hyatt points at 15,000 points per Category 4 night. This combination stretches your overall lodging value significantly.
In a recent development, category 4 includes well-known properties like the Andaz Maui at Wailea, Hyatt Regency Kyoto, Andaz San Diego, Hyatt Centric locations in major cities, and many Thompson hotels. The full list is available on hyatt.com by filtering the award chart. Category 4 is the sweet spot tier where property quality is high but the award cost remains accessible.
The World of Hyatt credit card automatically issues a Category 1-4 free night certificate each year on your card anniversary. A second certificate is earned after you spend $15,000 on the card in a calendar year. No special action is required beyond holding the card and meeting the spending threshold for the bonus certificate.
Yes. The free night certificate is valid for any available standard room at a Category 1-4 property, including weekends and holidays. There are no blackout dates. However, standard room availability may be limited during peak periods, so booking early is recommended.
Recent findings suggest that the certificate expires 12 months after issuance and cannot be extended or refunded. If you know you will not use it, consider booking a refundable reservation at a Category 4 property to hold the value, then cancel and rebook if your plans change. Do not let it expire unused — the value easily exceeds the annual fee.
This sweet spot was last verified over 90 days ago. Award availability and pricing may have changed — verify current rates before booking.
Industry observers note that the Hyatt Category 4 free night certificate is the most accessible sweet spot in travel rewards. You do not need to understand transfer partners, award charts, or complex booking strategies. You hold the World of Hyatt credit card, the certificate arrives on your anniversary, and you redeem it at a hotel where cash rates run $250 to $400 or more per night. The $95 annual fee pays for itself three to four times over with a single use. For FI-minded households that consolidate $15,000 or more in annual spending on one card, the second certificate doubles the value. This is the card perk that turns skeptics into believers — simple math, real savings, no tricks required.
General
⚠️ Warning
🌐 Mensjournal
#21796. Tech Report: Air Jordan 4 x The Whitaker Group Is Dropping June 2027 in Black Nubuck
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (31 w)
Tech Report: Air Jordan 4 x The Whitaker Group Is Dropping June 2027 in Black Nubuck
📅 17 Nov 2026 | ⏱️ 1 min read (31 words, ⚡ Quick Read) | Source: Mensjournal
⏱️ ~1 mins left to finish
📖 0% read
Air Jordan 4 x The Whitaker Group brings the crew behind A Ma Maniére back to Tinker Hatfield’s 1989 classic, with a reported June 5, 2027 release.

General
⚖️ Neutral
🌐 Seekingalpha
#21795. Industry News: T. Rowe Price: The Dividend Is Attractive, But The Turnaround Is Still Missing
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (208 w)
Industry News: T. Rowe Price: The Dividend Is Attractive, But The Turnaround Is Still Missing
📅 17 Nov 2026 | ⏱️ 1 min read (208 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Rowe Price Group (TROW) provides an attractive dividend yield on a reasonable P/E multiple.
- Sources indicate that analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no aims to initiate any such positions within the next 72 hours.
- Seeking Alpha's Disclosure: Past performance is no guarantee of future results.
MoMo Productions/DigitalVision via Getty Images.
MoMo Productions/DigitalVision via Getty Images.
It has been revealed that T. Rowe Price Group (TROW) provides an attractive dividend yield on a reasonable P/E multiple. However, given continued net client redemptions, there is no strong basis to suggest the stock.
Sources indicate that analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no aims to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
🔗 Related Articles
📰 #18031. Industry News: T. Rowe Price’s Blue Macellari: Institutions “Not Backing Away” From Bitcoin 📰 #23649. Industry News: Motorola MA2 wireless Android Auto adapter is now available, but at nearly twice the price 📰 #20259. What exactly counts as a creator? The industry still can’t agree
General
⚖️ Neutral
🌐 Physicianonfire
#21794. The Sunday Best (09/27/2026)
📅 27 Sep 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
The Sunday Best (09/27/2026)
📅 27 Sep 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
In 1980, a benefits consultant named Ted Benna figured out how to.

General
⚖️ Neutral
🌐 Seekingalpha
#21793. Nebius: Everyone Is Selling, Here's Why I'm Buying
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (189 w)
Nebius: Everyone Is Selling, Here's Why I'm Buying
📅 17 Nov 2026 | ⏱️ 1 min read (189 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Boy oh boy, it's been a hell of a few weeks in the market for AI stocks.
- Between the latest Democratic Congress, concerns over AI linked debt, and substantial capex that has put even hyperscalers like Google (.
- Analystâs Disclosure: I/we have a beneficial long position in the shares of NBIS either through stock ownership, options, or other derivatives.
Boy oh boy, it's been a hell of a few weeks in the market for AI stocks.
Between the latest Democratic Congress, concerns over AI linked debt, and substantial capex that has put even hyperscalers like Google (.
Analystâs Disclosure: I/we have a beneficial long position in the shares of NBIS either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any organization whose stock is mentioned in this article.
Seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

General
⚖️ Neutral
🌐 Seekingalpha
#21792. Phillips 66: Priced For A War Premium The Futures Say Won't Last
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (220 w)
Phillips 66: Priced For A War Premium The Futures Say Won't Last
📅 17 Nov 2026 | ⏱️ 1 min read (220 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Crude Oil Refinery sefa ozel/iStock via Getty Images.
- According to recent reports, I am rating Phillips 66 (PSX) a Sell, with a 12-month target price of $238.63, which is 9.9% below the November 13 close of $264.90.
- Sources indicate that analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no prepares to initiate any such positions within the next 72 hours.
Crude Oil Refinery sefa ozel/iStock via Getty Images.
sefa ozel/iStock via Getty Images.
According to recent reports, I am rating Phillips 66 (PSX) a Sell, with a 12-month target price of $238.63, which is 9.9% below the November 13 close of $264.90. Even after including my estimated dividends of $5.52, the total return.
Sources indicate that analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no prepares to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any manufacturer whose stock is mentioned in this article.
Recent findings suggest that seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
🔗 Related Articles
📰 #18755. Democrats have reached a détente in their internal war. Will it last? 📰 #23687. Breaking: Pentagon tests pack hunting with autonomous war robots 📰 #23656. Unlock Tom's Hardware Premium's SuperComputer 2026 coverage for free — sign up for an account to read detailed reports from the show
General
⚖️ Neutral
🌐 Physicianonfire
#21791. Decking the Halls In Fall — Is It Worth It For Physicians to Start Holiday Planning Right Now?
📅 29 Sep 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
Decking the Halls In Fall — Is It Worth It For Physicians to Start Holiday Planning Right Now?
📅 29 Sep 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
In 1980, a benefits consultant named Ted Benna figured out how to.

General
📈 Bullish
🌐 Seekingalpha
#21790. HawkEye 360: A Buy As Space Intelligence Demand Surges
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (213 w)
HawkEye 360: A Buy As Space Intelligence Demand Surges
📅 17 Nov 2026 | ⏱️ 1 min read (213 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Recent findings suggest that shares of HawkEye 360, Inc.
- Analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours.
- Sources indicate that seeking Alpha's Disclosure: Past performance is no guarantee of future results.
NicoElNino/iStock via Getty Images.
NicoElNino/iStock via Getty Images.
Recent findings suggest that shares of HawkEye 360, Inc. (HAWK) gained 24% after the company, which sells intelligence derived from radio signals picked up by its satellites, increased its revenue outlook for the year. I am initiating coverage with a buy rating.
Analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Sources indicate that seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

AI & Tech
⚖️ Neutral
🌐 Seekingalpha
#21789. Tech Report: Warsh Must Choose Between Hiking Into An Energy Shock And Trusting AI Disinflation
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (52 w)
Tech Report: Warsh Must Choose Between Hiking Into An Energy Shock And Trusting AI Disinflation
📅 17 Nov 2026 | ⏱️ 1 min read (52 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- According to recent reports, as we discussed last week, shocks don't tend to end booms.
- Today, the man who decides whether that happens this time spent.
MarioGuti/iStock via Getty Images.
MarioGuti/iStock via Getty Images.
Originally published on November 16, 2026.
According to recent reports, as we discussed last week, shocks don't tend to end booms. Central banks do (by overtightening into the boom).
Today, the man who decides whether that happens this time spent.
General
⚖️ Neutral
🌐 Washingtonpost
#21788. The surprising newly introduced face of the MAHA-MAGA alliance: Stephen Miller
📅 16 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (31 w)
The surprising newly introduced face of the MAHA-MAGA alliance: Stephen Miller
📅 16 Nov 2026 | ⏱️ 1 min read (31 words, ⚡ Quick Read) | Source: Washingtonpost
⏱️ ~1 mins left to finish
📖 0% read
Health chief Robert F. Kennedy Jr. states the upcoming White House chief of staff is even “more radical” than he is, encouraging MAHA supporters but worrying critics.
General
⚖️ Neutral
🌐 Mrmoneymustache
#21787. Tech Report: Retired Man Tries to Spend More Money, Mostly Fails
📅 16 Jan 2025 • ⏱️ 7m • 📚 Deep Dive (1485 w)
Tech Report: Retired Man Tries to Spend More Money, Mostly Fails
📅 16 Jan 2025 | ⏱️ 7 min read (1485 words, 📚 Deep Dive) | Source: Mrmoneymustache
⏱️ ~7 mins left to finish
📖 0% read
💡 Key Takeaways
- Industry observers note that A couple of years ago, Mr.
- “I’m such an enlightened middle-aged Badass, adjusting habits and realigning myself at the snap of my fingers.
- In a recent development, so, two years passed with an even greater feeling of abundance.
Industry observers note that A couple of years ago, Mr. Money Mustache lost some credibility among the faithful when he wrote this blog post about actually trying to spend a bit more money, while buying a Tesla as the first step in that program.
I thought to myself at the time,.
“I’m such an enlightened middle-aged Badass, adjusting habits and realigning myself at the snap of my fingers. Onward to the next forty eight years of the Good Life!”.
In a recent development, so, two years passed with an even greater feeling of abundance. I had a marvelous time traveling everywhere and spending money like I thought a proper wealthy person would do.
I dined out in stylish restaurants, booked hotels based on their niceness rather than their cheapness, paid extra to sit in the “reduced torture” seats of the airplanes, and gave zero fucks about paying double for groceries if I happened to be in a Whole Foods rather than my usual Sam’s Club and Costco (and yes I treat myself to memberships at both warehouse stores!).
In a recent development, among the highlights, my son and I have worked our way though a nice selection of late night EDM concerts and three Meowwolf art venues including a Christmas Day road trip from our winter home in Tempe Arizona to Las Vegas last year. And having spent much of the year as a single man, I had a wide open schedule to just meet up with friends, explore upcoming places and meet new people as opportunities came up. It felt like a year of adventurous transition, which means it felt like much more than twelve months.
Industry observers note that with all this flashy spending, I was sure my budget must have crept back into full American Consumer territory. But I was having too much fun to bother adding it all up to check.
Until recently, when I was doing another round of informal coaching for a friend and we both decided to tally our spending for the past year to compare notes.
When I finally finished sorting all of those transactions into a spreadsheet and hit the “sum” button, the results surprised me.
While my overall spending had indeed increased (especially in travel-related categories), the substantial-picture effect was still pretty minimal. Depending on how I account for things like the car and my business expenses, my spending went from $20,000 to about $30,000 (plus the usual hidden subsidy of a paid-off house.).
Recent findings suggest that this level could still be sustained by a $1 million investment nest egg. Since my investments are quite a bit higher than that (especially after these recent years of crazy economic growth and the never-ending stock market rally), I’m still way under budget.
Although I still “failed” to really increase my spending to the MMM-recommended levels for old wealthy people, this still makes me happy, because I have genuinely had more fun with the abundance mindset, and I can keep trying more life experiments in the coming years.
Recent findings suggest that as we covered in the 2019 article on the idea of an Optimization Council, it’s always a good idea to compare our spending, tips and tricks on how to get the most out of life. Almost twenty years into early retirement, this is where I have landed so far, although I’m always learning and open to feedback.
Anyway, let’s cut the wistful commentary and get into the budget.
In summary: Wow, how interesting! When we compare this to my 2019 post on that year’s spending, it’s only a bit higher even after all the inflation we have seen in recent years. I spent more on travel and fun, but less on home renovation – partly because I was away so much I didn’t have as much time to work on my house. The health insurance is a new cost too since I was self-insured back then.
My budget is notably missing the biggest expense for most people, which is housing costs. This is because I paid off my house long ago, and I also love working on and taking care of my own home, which means there are no bills for lawn mowing, plumbers, tree pruning or handyman services.
This strategy is not for everyone, and it’s not even the optimum financial one for me – I would have been better off taking out the biggest mortgage I could get at 3% back in the sweet borrowing times of 2021, and putting all that principal to work in stock index funds where it would have almost doubled since then. But I still get a great peace of mind from just having no mortgage payment, and there’s really no better way to use your money than to buy such good feelings. Also, I get a secondary benefit of not having to buy house insurance, which saves me another $2000 per year, boosting my effective return on that payoff.
First of all, the biggest money saving factor of good health and good luck has continued, meaning I’ve still had no actual medical expenses. But I still do maintain two layers of health care support which together feel very much like the ultimate version of health insurance: a membership with a top of the line Direct Primary Care (DPC) medical clinic ($107 per month) plus a high-deductible plan ($201) with a health sharing organization called Sedera.
The combined cost of $308 per month is less than the cheapest Bronze blueprint in the field of standard health insurance, yet I get personalized support with zero deductible for almost all typical medical needs, plus some protection from larger medical bills if my good luck runs out.
But as a disclaimer, I’m not an expert on medical needs and health insurance because I’ve had so little experience with the system. And the highest priority in my life is arranging my days for maximum health to give me the best chance of keeping it this way.
Industry observers note that when it comes down to it, money is a tool for survival and if we’re lucky, self actualization. So I’m always asking myself if there’s anything I can change or improve to make the most of this good fortune.
I also try to keep in mind an interesting principle of happiness, which says that,.
Fixing your persistent problems is more effective than just doubling down on things that are already good in your life.
For me, there are already a lot of good things which don’t need improving. My family, friends, relationships, health, food and daily activities are pretty much as good as I could imagine.
The only annoyance I can think of is physical chaos: I have a lot of space-intensive hobbies like construction and music, and I presently live in a pretty small house which is basically maxed out. I could really use a doubling of my workshop space from the current 2-car, 440 square foot garage to maybe a thousand or so.
In a recent development, but I also love where I live and wouldn’t want to give up my views, neighbors or current place. So I’ll keep optimizing what I’ve got unless some perfect opportunity comes up for a bigger place right on my block.
In the longer run, a mountain compound with its own cliffs and stream are also on my “maybe” list. But once again, my days and life are already overbooked with joyful things. My existing house and our HQ Coworking space already have long to-do lists. Would I actually be happier if I added another place to my portfolio? So I keep this idea on the shelf until I’m willing to trade it for another existing commitment – like selling my house or the coworking space.
Recent findings suggest that but for now, I’m just extremely excited to blaze into 2025 with loads abundance and piles of challenging stuff on my to-do list. And I wish you the same!
In the Comments: Where are you at on this spectrum of stinginess versus abundance mentality, and fulfilment versus longing in life?
A Temporary Note about Teslas and other electric cars:Rumor has it that the $7500 EV tax credit might be disappearing when our latest president takes over next week, so this might be the cheapest chance to buy what I feel are the best cars on the market: The Model Y, or Model 3.
Both used and fresh prices are at record lows so shop around and get an additional $1000 off a new one if you use a referral code from a friend or here’s mine if you need one (many thanks!)Full article here at The Model Y Experiment.
According to recent reports, FTC Compliance Note: I use referral links for some products when possible which means the blog may earn a commission if you use them. More details here.
🔗 Related Articles
📰 #23639. Tech Report: Game dev reveals huge difference in money made on Steam vs Epic Games Store 📰 #22340. Tech Report: How a retired Adobe employee photographs wild birds in West Virginia 📰 #20864. Tech Report: Maryland Man Convicted of $18.7 Million Medicare Fraud for Respiratory Testing Scheme Targeting Nursing Homes
General
⚖️ Neutral
🌐 Physicianonfire
#21786. How to Develop a Basic Investment Analysis Routine While Busy
📅 01 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
How to Develop a Basic Investment Analysis Routine While Busy
📅 01 Oct 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
In 1980, a benefits consultant named Ted Benna figured out how to.

General
⚖️ Neutral
🌐 Seekingalpha
#21785. Latest Update: Is The Inflation Shock Starting To Lose Momentum?
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (55 w)
Latest Update: Is The Inflation Shock Starting To Lose Momentum?
📅 17 Nov 2026 | ⏱️ 1 min read (55 words, ⚡ Quick Read) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
Richard Drury/DigitalVision via Getty Images.
Richard Drury/DigitalVision via Getty Images.
According to recent reports, thereâs more to inflation than oil prices, but the recent pullback in crude suggests that the inflationary pressure tied to the Iran conflict may be starting to ease. Even if energy prices continue to move lower, itâs.
General
⚖️ Neutral
🌐 Moneycrashers
#21784. Industry News: Best Secured Credit Cards – No Annual Fee and a Path to a Regular Card
📅 16 Nov 2026 • ⏱️ 3m • 📚 Deep Dive (676 w)
Industry News: Best Secured Credit Cards – No Annual Fee and a Path to a Regular Card
📅 16 Nov 2026 | ⏱️ 3 min read (676 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~3 mins left to finish
📖 0% read
💡 Key Takeaways
- It has been revealed that to build or rebuild credit with a secured card, open the Discover it Secured Cash Back.
- A secured card’s credit line usually equals your deposit, so $200 down gets you a $200 limit.
- Sources indicate that every card here charges no annual fee, and you get the deposit back when the issuer moves you to a regular card or you close the account paid off.
It has been revealed that to build or rebuild credit with a secured card, open the Discover it Secured Cash Back. It charges no annual fee, pays cash back while you build, and returns your deposit when Discover upgrades you to a regular card.
A secured card’s credit line usually equals your deposit, so $200 down gets you a $200 limit. The Discover it Secured Cash Back can open a $200 line on a deposit as low as $49, depending on your credit.
Sources indicate that every card here charges no annual fee, and you get the deposit back when the issuer moves you to a regular card or you close the account paid off. Some of these issuers start reviewing you for a regular card after six months. If you can’t spare a deposit, look at unsecured cards for bad or fair credit instead. Add up their fees first, because unlike a deposit, a bad-credit card’s fees never come back.
It pairs the lowest possible deposit here with 5% in quarterly categories you activate, up to a cap, and once you build a positive track record, it becomes a regular Discover it Cash Back.
For more information, read our full Discover it Secured Cash Back Review.
You choose the category that earns 3%, such as gas or dining, and it pays 6% there the first year, plus 2% at grocery stores, on your first $2,500 of those purchases each quarter.
For more information, read our full Bank of America® Customized Cash Rewards Secured Credit Card Review.
Recent findings suggest that pick two categories each quarter, like home utilities or cell phone, for 5% on up to $2,000 of quarterly spending there. Its deposit starts at $300, with an upgrade review after 12 months.
For more information, read our full U.S. Bank Cash+® Secured Visa® Card Review.
Every purchase earns 1.5%, with no categories to pick or activate, and Bank of America reviews your account periodically to see whether it can return your deposit.
For more information, read our full Bank of America® Unlimited Cash Rewards Secured Credit Card Review.
Citi reviews you for a regular card starting at nine months and yearly after that, though the card earns no rewards, and neither does the Citi Diamond Preferred you’d move to.
For more information, read our full Citi® Secured Mastercard® Review.
If you can join Navy Federal as a service member, veteran, or family member, you get a credit union’s 18.00% variable rate and, after six months, monthly reviews for an upgrade that frees your deposit.
For more information, read our full cashRewards Secured Credit Card Review.
Industry observers note that approval takes no credit check, so try it if big banks turn you down. Its deposit starts at $300, and opensky may offer a no-deposit Gold card in as little as six months.
For more information, read our full opensky® Plus Secured Visa® Credit Card Review.
In a recent development, the choice comes down to how you spend and whether a big bank will approve you, and for most readers that’s the Discover it Secured. Whichever card you open, put one small bill on it and pay the full statement balance each month, the habit that leads to an upgrade to a regular card.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
In a recent development, editorial Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. Compensation does not influence our editorial evaluations, ratings, or opinions.
It has been revealed that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every firm or offer available in the marketplace.

General
⚠️ Warning
🌐 Seekingalpha
#21783. Breaking: Immunome: De-Risked With The FDA, With An Admirably Deep Clinical Bench
📅 17 Nov 2026 • ⏱️ 1m • 📖 Standard (201 w)
Breaking: Immunome: De-Risked With The FDA, With An Admirably Deep Clinical Bench
📅 17 Nov 2026 | ⏱️ 1 min read (201 words, 📖 Standard) | Source: Seekingalpha
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- It's been a long time since I last covered Immunome, Inc.
- Analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no looks to initiate any such positions within the next 72 hours.
- Recent findings suggest that seeking Alpha's Disclosure: Past performance is no guarantee of future results.
alexey_ds/iStock via Getty Images.
alexey_ds/iStock via Getty Images.
It's been a long time since I last covered Immunome, Inc. (IMNM), and in that article I made a pretty large shift in sentiment from Sell all the way.
Analystâs Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no looks to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any firm whose stock is mentioned in this article.
Recent findings suggest that seeking Alpha's Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
General
⚖️ Neutral
🌐 Physicianonfire
#21782. The Sunday Best (10/04/2026)
📅 04 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (35 w)
The Sunday Best (10/04/2026)
📅 04 Oct 2026 | ⏱️ 1 min read (35 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
Recent findings suggest that ouch. See myself in several of these all at the same time. Outstanding thinking opportunities this week. Thanks Doc. for doing no harm and healing this week.
General
⚖️ Neutral
🌐 Moneycrashers
#21781. 18 Jobs for Retirees – What They Pay and When Social Security Holds Back Benefits
📅 16 Nov 2026 • ⏱️ 2m • 📖 Standard (358 w)
18 Jobs for Retirees – What They Pay and When Social Security Holds Back Benefits
📅 16 Nov 2026 | ⏱️ 2 min read (358 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- Pick retirement work by its pay, its schedule, and how it fits your Social Security claim.
- In the year you reach full retirement age, 67 for anyone born in 1960 or later, Social Security holds back $1 for every $3 you earn above $65,160.
- Because withheld benefits are credited back at full retirement age, the test is about when to claim, not whether to work.
Pick retirement work by its pay, its schedule, and how it fits your Social Security claim. Claim before full retirement age, and until the year you reach it, Social Security holds back $1 for every $2 you earn above $24,480 a year. Your check rises at that age to account for the months withheld.
In the year you reach full retirement age, 67 for anyone born in 1960 or later, Social Security holds back $1 for every $3 you earn above $65,160. It counts only what you earn before the month you reach that age, and from that month on, your earnings no longer reduce your benefit.
Because withheld benefits are credited back at full retirement age, the test is about when to claim, not whether to work. A job that pays well above the limit is a reason to wait to claim, while one that pays less leaves your check untouched.
Social Security counts only pay from work toward the limit. That means wages, including bonuses, commissions, and vacation pay, or net profit if you’re self-employed. A pension, an annuity, interest, and investment income don’t count, so a retiree who consults while drawing a pension is tested on the consulting income alone.
Sources indicate that to check a job against the limit, multiply its hourly pay by the hours you plan to work. Tutoring 20 hours a week for 50 weeks at the $20.84 median comes to $20,840, under the $24,480 limit.
Before you take a job that will pay more than the limit, enter your expected pay in Social Security’s earnings test calculator to see how much it would hold back.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Industry observers note that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every manufacturer or offer available in the marketplace.

General
⚖️ Neutral
🌐 Physicianonfire
#21780. Debt And Physician Finances
📅 06 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (92 w)
Debt And Physician Finances
📅 06 Oct 2026 | ⏱️ 1 min read (92 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
Wow, this post on managing physician debt is incredibly insightful! I love how you broke down the various strategies for overcoming student loans and financial stress. It’s such a critical topic for doctors who often feel overwhelmed by their finances. I’m curious about your thoughts on alternative income streams outside of traditional practice—have you seen any success stories in that area? Also, speaking of games like sprunky, do you think gamifying financial planning could help motivate more physicians to tackle their debt? Looking forward to hearing your insights!
Hardware & Chips
⚖️ Neutral
🌐 Marketwatch
#21779. ‘Nvidia’s turmoil has me spooked’: Should I sell my stocks and invest in real estate?
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
‘Nvidia’s turmoil has me spooked’: Should I sell my stocks and invest in real estate?
📅 17 Nov 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Marketwatch
⏱️ ~1 mins left to finish
📖 0% read
“Real estate here in Florida seems to be presenting some interesting opportunities.”.

General
⚖️ Neutral
🌐 Moneycrashers
#21778. Axos Business Interest Checking Review – Worth It for Operating Cash Under $50,000
📅 16 Nov 2026 • ⏱️ 6m • 📚 Deep Dive (1175 w)
Axos Business Interest Checking Review – Worth It for Operating Cash Under $50,000
📅 16 Nov 2026 | ⏱️ 6 min read (1175 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- Recent findings suggest that open Axos Business Interest Checking for the cash your business keeps on hand to pay bills.
- It has been revealed that money a business keeps in checking for payroll, rent, and supplier bills has to stay where it can be spent the day a bill comes due.
- In a recent development, axos Bank released online on July 4, 2000, and is headquartered in San Diego, with offices in Las Vegas.
Recent findings suggest that open Axos Business Interest Checking for the cash your business keeps on hand to pay bills. Keep a $5,000 average daily balance to skip the $10 monthly fee, and stay under $50,000 to earn its top rate of 1.01%. At $50,000, the whole balance earns 0.20%, so put larger reserves in a business savings account.
It has been revealed that money a business keeps in checking for payroll, rent, and supplier bills has to stay where it can be spent the day a bill comes due. Axos Business Interest Checking pays 1.01% APY, the annual percentage yield, on balances up to $49,999.99, with no minimum number of transactions or card purchases required to earn it. It also charges a $10 monthly fee unless its average daily balance for the month reaches $5,000. Once the balance reaches $50,000, the rate on the whole balance, not just the part above the line, drops to 0.20%.
In a recent development, axos Bank released online on July 4, 2000, and is headquartered in San Diego, with offices in Las Vegas. It reports more than $28.2 billion in assets, and its parent company, Axos Financial, trades on the Fresh York Stock Exchange as AX. The Better Business Bureau rates it A+. For small businesses it offers savings and two checking accounts, one that pays interest and one that doesn’t, plus payroll, card processing, and loans backed by the U.S. Small Business Administration through partner companies.
Three things decide whether the account is worth it: how its rate tiers work, what it costs to keep, and how money gets in and out of an online bank.
Axos doesn’t pay each tier’s rate on just the dollars in that tier. Its account agreement applies one daily rate to the balance, and its rate table sets that rate by the range the balance falls in, so a $50,000 balance earns 0.20% on every dollar.
Take the rates Axos posted on November 15, 2026, and a balance that holds steady for a year. A business with $49,999 in the account earns about $505. One with $50,000 earns about $100, and it would take more than $500,000 in the account to earn $505 again.
Industry observers note that the waiver runs on the month’s average, so the balance can dip under $5,000 for a few days around payroll without triggering the fee, as long as the month averages $5,000 or more. A month that falls short costs $10, while $5,000 earns about $4 a month at the rate Axos posted in November 2026.
The 100-item limit counts every debit, credit, and deposited check, so a business that pays many small bills or takes frequent payments can go over it in a busy month.
In a recent development, checks go in through the Axos app or by mail. Cash goes in at an ATM that takes deposits, using the business debit card. Axos asks customers not to mail cash, and a deposit at an ATM Axos doesn’t own may not be available until the fifth business day after it’s made.
Relying on ATMs for cash makes the account a poor fit for a shop that takes in cash every day. A business paid by card, check, or transfer has little cash to deposit.
Recent findings suggest that the account pays best on operating cash, the money that has to stay in checking anyway to cover the next month’s payroll, rent, and card bills. Reserves, the money beyond next month’s bills, earn more in Axos Business Premium Savings, which pays 3.50% APY on balances up to $4,999,999.99 against this account’s top rate of 1.01%, with no monthly fee or minimum opening deposit. Savings gives up some access in return, since Axos charges $0.30 for each item past 20 a month and can limit certain savings withdrawals to six a month.
It has been revealed that run the rates Axos posted on November 15, 2026, for a business with $60,000 at Axos, held for a year. Left in Business Interest Checking, the whole $60,000 earns the second tier’s rate, about $120. Kept as $20,000 in checking for bills and $40,000 in Premium Savings, the same money earns about $1,602, with $202 coming from checking and $1,400 from savings.
Axos Basic Business Checking pays no interest, but it reimburses two outgoing domestic wires a month. For a business that sends two, that saves $30 a month, and Interest Checking earns that much only on an average balance above about $35,600 at the November 2026 rate.
Recent findings suggest that deposits carry FDIC insurance, the federal guarantee on bank deposits, up to the standard $250,000. Every account a business holds at Axos under the same ownership, through any of its brands, counts toward that one limit.
Sources indicate that for balances above it, Axos offers Insured Cash Sweep through the IntraFi network, which splits deposits into amounts under $250,000 at other FDIC-insured banks and extends coverage up to $265 million. Axos indicates swept deposits earn interest but doesn’t publish the rate. The business keeps one relationship and one statement with Axos, a relationship manager sets it up, and the program’s limits and eligibility rules apply.
The account connects to QuickBooks, in its desktop and online versions, and to the desktop version of Quicken, syncing directly or through a file downloaded from Axos.
Sources indicate that support comes from business relationship managers, by phone at 844-678-2726 on weekdays from 6 a.m. to 6 p.m. Pacific time, and through secure messages in online banking. Axos’s business support pages list no weekend phone hours.
Recent findings suggest that each business can open one Interest Checking account. Axos opens business accounts only for companies in the United States, and the business and each owner and signer need a physical address on file.
Industry observers note that axos Business Interest Checking is a good place for a business’s bill money and a poor place for its savings. Its strongest case is a business that keeps a steady $5,000 to $50,000 in checking, stays within 100 transactions a month, and rarely wires money out, since that business earns 1.01% on cash that would otherwise sit idle.
It’s the wrong account for a business that deposits cash daily, sends several wires a month, or lets its balance run past $50,000. Keep a month of bills in Interest Checking, below $50,000, and move the rest into Axos Business Premium Savings.
Learn more about Axos Business Interest Checking or see how it compares to the best small business checking accounts.
Axos Business Interest Checking.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every manufacturer or offer available in the marketplace.
🔗 Related Articles
📰 #21774. Axos Basic Business Checking Review – Unlimited Transactions, but Slow Cash & Check Deposits 📰 #21752. Latest Update: Novo Business Checking Review – Free Invoicing for Businesses That Rarely Handle Cash 📰 #19175. World Of Hyatt Business Credit Card Review: Worth It For The Bonus & Status?
General
⚖️ Neutral
🌐 Physicianonfire
#21777. The Sunday Best (10/11/2026)
📅 11 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
The Sunday Best (10/11/2026)
📅 11 Oct 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
In 1980, a benefits consultant named Ted Benna figured out how to.
General
⚖️ Neutral
🌐 Moneycrashers
#21776. Axos ONE Review – High-Yield Savings When Your Deposits Qualify
📅 16 Nov 2026 • ⏱️ 6m • 📚 Deep Dive (1218 w)
Axos ONE Review – High-Yield Savings When Your Deposits Qualify
📅 16 Nov 2026 | ⏱️ 6 min read (1218 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- Open Axos ONE if your paycheck already arrives by direct deposit.
- The national average rate is 0.39% APY, or annual percentage yield, according to the Federal Deposit Insurance Corporation, so a better rate usually means a second bank, away from the checking account your paycheck lands in.
- Recent findings suggest that axos Bank opened as Bank of Internet USA on July 4, 2000, one of the first banks built to run fully online, and took the Axos name in 2018.
Open Axos ONE if your paycheck already arrives by direct deposit. Each month with at least $1,500 in direct deposits and an average checking balance of at least $1,500, savings earns 4.21% APY, and the bundle charges no monthly or overdraft fees. If your deposits vary month to month, pick a savings account that pays its rate without conditions.
Most banks pay little on savings. The national average rate is 0.39% APY, or annual percentage yield, according to the Federal Deposit Insurance Corporation, so a better rate usually means a second bank, away from the checking account your paycheck lands in. Axos ONE pairs checking and high-yield savings at one online bank and ties the savings rate to the checking side. In any month the checking account meets its deposit and balance terms, savings earns the boosted rate. In a month it misses them, savings drops to 1.00% and checking earns nothing.
Recent findings suggest that axos Bank opened as Bank of Internet USA on July 4, 2000, one of the first banks built to run fully online, and took the Axos name in 2018. It’s based in San Diego, and its parent, Axos Financial, trades on the New York Stock Exchange and reported $30.8 billion in total assets at the end of September 2026. Axos also runs UFB Direct, which matters for the new-customer promotion and the deposit insurance below.
Axos ONE is two accounts opened together, and the checking account’s activity decides the rates on both.
Industry observers note that most of the bundle’s value is in savings. In a qualifying month it pays 4.21% APY on balances up to $249,999.99 and 3.50% on the portion above that. In any other month, the whole balance earns 1.00%.
Sources indicate that checking pays 0.51% APY in a qualifying month and nothing otherwise. There’s no monthly fee, no minimum balance, and no overdraft or nonsufficient-funds fee. A payment your balance can’t cover may still be paid or returned, just without a charge. A direct deposit can arrive up to two days early, depending on whether and when your payer funds it. The Visa debit card works fee-free at more than 95,000 ATMs, and Axos reimburses up to $10 a month in other banks’ domestic ATM fees.
The bank’s standalone Axos Checking pays 1.00% APY, a promotional rate, in any statement cycle with at least $1 in direct deposits, and reimburses domestic ATM fees without a cap, but it carries no savings boost. If you only need checking, Axos Checking or another free checking account without a balance requirement is the simpler choice.
Each month, the checking account must meet both halves of one option for either account to earn its boosted rate:.
Sources indicate that both accounts must also be open on the 25th and on the day interest is paid. A newly introduced account’s first window starts the day it opens, and one opened on or after the 25th starts qualifying the next month.
In a recent development, the fairest yardstick for those terms is Axos’s own Summit Savings, which pays 3.75% APY with no minimum balance and no monthly requirements. Take $20,000 kept in savings for a year at the rates Axos paid when this review was written. At 4.21%, qualifying every month earns about $842 in Axos ONE, $92 more than the $750 Summit Savings pays at 3.75%. At the 1.00% base rate, missing every month earns about $200, $550 less than Summit.
Sources indicate that latest customers who open the bundle by December 1, 2026 can earn 5.00% APY on up to $49,999.99 of savings for six statement cycles, the opening cycle included, or five when the account opens on or after the 25th. Each cycle still has to meet the monthly terms, and the boost is off in any cycle the savings balance averages $250,000 or more. Anyone who holds or has ever held an Axos Bank or UFB Direct account, loan, or investment is excluded, so opening another Axos account first, Summit Savings included, rules you out. At the rates when this review was written, the boost adds 0.79 percentage points, about $197 over six cycles on a full $49,999.99.
Recent findings suggest that the fees Axos ONE does charge cover less routine moves. Outgoing wires cost $35 within the U.S. and $45 abroad, incoming wires are free, and debit card purchases and ATM withdrawals in a foreign currency carry a 1% conversion fee.
According to recent reports, axos works online, so the app and the phone carry most of the load. Its Axos All-In-One Mobile Banking app holds a 4.7-star rating from about 20,000 ratings on Apple’s App Store, and a Direct Banker answers the phone 24/7, Thanksgiving and Christmas aside. Checks deposited by phone are held five days.
Cash is the awkward part. You can deposit it at participating ATMs or at the register of retailers in the Green Dot network, such as 7-Eleven, CVS, and Walmart. The store may charge up to $4.95 per deposit, and each deposit can run $20 to $500, more at Walmart and ACE Cash Express.
Deposits are insured by the FDIC through Axos Bank up to $250,000 per depositor in each ownership category, such as individual or joint. Money you keep at UFB Direct or any other Axos brand counts toward the same limit, since Axos insures them all under one FDIC certificate.
For larger savings, the Axos Insured Deposit Program moves money from Axos ONE Savings to partner banks, each insuring up to the same limit, for up to $2.5 million in additional coverage. Enrolling online or in the app is free and leaves your rate and features unchanged. Checking stays outside the program. You also can’t exclude a partner bank, and Axos leaves it to you to watch which banks hold your money, which matters if you already bank at one of them.
Axos ONE works best as a home for a paycheck that already arrives by direct deposit. That deposit, plus a $1,500 cushion in checking, earns savings the boosted rate, no part of the bundle charges a monthly or overdraft fee, and the extra FDIC coverage is free. For a saver who wants checking and savings at one bank, that’s a strong combination.
It’s a poor fit for freelancers and others whose deposits arrive irregularly and for anyone who can’t spare $1,500 in checking, since Summit Savings or another account with no monthly terms would earn them more. Savers who move money out often or deposit cash will run into its six-withdrawal limit and paid cash deposits. Readers whose paycheck clears $1,500 a month should open the bundle and point the direct deposit to its checking account so it posts by the 25th.
Learn more about Axos ONE or see how it compares to the best high-yield savings accounts.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.
🔗 Related Articles
📰 #21774. Axos Basic Business Checking Review – Unlimited Transactions, but Slow Cash & Check Deposits 📰 #21735. Latest Update: Crew Review: High-Yield Checking With Built-In Budgeting for Families 📰 #21778. Axos Business Interest Checking Review – Worth It for Operating Cash Under $50,000
General
⚖️ Neutral
🌐 Physicianonfire
#21775. Industry News: 11 Retirement Planning Mistakes That Haunt High-Earning Physicians
📅 13 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (81 w)
Industry News: 11 Retirement Planning Mistakes That Haunt High-Earning Physicians
📅 13 Oct 2026 | ⏱️ 1 min read (81 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
The Social Security claiming example was eye-opening, since the gap between filing at 62 and waiting until 70 is far larger than most people assume. I also appreciated the warning about stuffing everything into pre-tax accounts, because required minimum distributions and Medicare surcharges can quietly push a retiree back into a high bracket. The practical takeaway for me is to use the gap years for partial Roth conversions instead of leaving the whole tax problem for later.
General
⚖️ Neutral
🌐 Moneycrashers
#21774. Axos Basic Business Checking Review – Unlimited Transactions, but Slow Cash & Check Deposits
📅 16 Nov 2026 • ⏱️ 7m • 📚 Deep Dive (1491 w)
Axos Basic Business Checking Review – Unlimited Transactions, but Slow Cash & Check Deposits
📅 16 Nov 2026 | ⏱️ 7 min read (1491 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~7 mins left to finish
📖 0% read
💡 Key Takeaways
- Industry observers note that open Axos Basic Business Checking if your business gets paid by card, bank transfer, or wire and you want no monthly fee, no minimum balance, and no cap on transactions.
- Sources indicate that axos makes a small business choose between earning interest and avoiding fees.
- In a recent development, axos has been a digital bank since it opened on July 4, 2000, and runs from its San Diego headquarters.
Industry observers note that open Axos Basic Business Checking if your business gets paid by card, bank transfer, or wire and you want no monthly fee, no minimum balance, and no cap on transactions. Skip it if you deposit cash or paper checks often, since both can take until the fifth business day to become available.
Sources indicate that axos makes a small business choose between earning interest and avoiding fees. Its interest-bearing account, Axos Business Interest Checking, charges $10 in any month its average daily balance is under $5,000, plus 50 cents for each transaction past 100 a month. A business that keeps $5,000 there and stays at 100 transactions or fewer earns interest and pays neither fee. Basic Business Checking pays no interest and charges neither fee at any balance or transaction count.
In a recent development, axos has been a digital bank since it opened on July 4, 2000, and runs from its San Diego headquarters. It counts more than $28.2 billion in assets, and its parent tech giant, Axos Financial, trades on the New York Stock Exchange as AX. The Better Business Bureau, which has accredited Axos Bank since 2011, rates it A+.
Basic Business Checking’s strength is its short list of fees. Its weakness is getting cash and checks into the account, since Axos has only two branches.
Axos’s account page and its small-business fee schedule, effective September 28, 2026, set these terms:.
According to recent reports, electronic direct deposits are available the day Axos receives them, and incoming wires the next business day. Axos’s account agreement lets it hold other incoming ACH transfers, the standard electronic payments between bank accounts, for up to five business days after they post. The money may be released on the third business day if no payment is returned.
Checks go in through the app, up to 60 a month, $50,000 a business day, and $150,000 in any 30 days. Axos makes them available on the fifth business day after the deposit unless it releases them sooner, so a business paid mostly by check waits about a week for its money.
Cash is harder. In its March 2026 review of the bank, the Office of the Comptroller of the Currency counted one branch in San Diego, with an ATM that takes deposits, and one in Las Vegas, which Axos’s agreement states accepts no cash. Elsewhere, cash goes in at other banks’ ATMs that accept deposits, which Axos’s ATM locator finds, and Axos makes it available by the fifth business day at the latest. A business that takes in cash every week should check for one near it before applying.
Axos’s app demonstrates business and personal Axos accounts under one login, moves money between them, and sends wires. Bill Pay comes with the account and usually delivers a payment by ACH in one to three business days, or as a mailed check in up to 10. Its limits are $100,000 for a payment to a company or a transfer, $10,000 to a person, and $2,500 by email, and Axos won’t raise them.
For bookkeeping, the account connects to QuickBooks Desktop, QuickBooks Online, and Quicken’s desktop version, either directly or through transaction files you download in CSV, QBO, QFX, or OFX format and import.
In a recent development, A growing business may outgrow the standard platform in two ways. It can’t yet add a user who isn’t a signer on the account, such as a bookkeeper or accountant, and it doesn’t send batches of ACH payments to staff or vendors. Both come with Axos’s treasury management service, its package of payment and fraud-control tools for businesses, which is free for a first account and charges $1 a batch and $1 for each ACH payment past 15 a month.
Recent findings suggest that axos Bank’s deposits carry Federal Deposit Insurance Corporation (FDIC) coverage up to $250,000 per depositor in each ownership category, the FDIC’s groups for how money is owned, under FDIC certificate 35546. A business that keeps more can ask a relationship manager to set up Axos’s Insured Cash Sweep, which places money at other banks in the IntraFi network and can raise coverage to $265 million, with interest paid on what’s swept.
Recent findings suggest that sole proprietors should add up their personal money too. The FDIC insures a sole proprietorship’s deposits as the owner’s own, combined with the owner’s other individual accounts at the same bank, and Axos’s UFB Direct brand counts as the same bank. A corporation’s or partnership’s deposits are insured in their own category.
Industry observers note that A business formed less than a year before it applies can earn up to $200 by applying with promo code START200 by January 31, 2027. Axos pays $50 for each statement cycle in which the account’s average daily balance is at least $3,000, in any four of its first five statement cycles, counting the month it opens.
The business must also never have been the primary owner of an Axos small-business account, and Axos closes the account if it isn’t approved and funded within 60 days. An account closed within 180 days can be charged up to $200 for closing early, and the bonus may be taxable and reported on a Form 1099.
The balance costs little to hold. At a sample savings rate of 3.50% annual percentage yield (APY), $3,000 would earn about $35 in four months, by our math. A business that can spare the balance gives up that $35 to collect up to $200.
Recent findings suggest that an established business can’t use START200, and Axos’s other cash offer needs a large savings balance. A business that pairs the account with Business Premium Savings, opening both in one application with code SBB600 by January 31, 2027, can earn up to $600. Axos pays $100 for each statement cycle in which the business meets four requirements by the 25th of the month. They are a $50,000 average daily balance in savings, a $1,500 average in checking, a deposit of $1,000 or more by ACH, wire, or check from outside Axos, and two debit card purchases of $50 or more.
Business Premium Savings pays 3.50% APY on balances under $5 million with no monthly fee, though it charges 30 cents for each transaction past 20 a month. Only one Axos offer applies to a business at a time.
Axos says its application takes minutes online. It opens accounts only for businesses in the United States, and every signer must live in the U.S., with a physical address there and a Social Security number, though citizenship isn’t required. The application asks for the business’s Employer Identification Number (EIN), a Social Security number for a sole proprietor, ownership agreements, a business license, and articles of incorporation or organization.
Axos may turn down businesses in industries it restricts, such as cannabis, cryptocurrency, internet gambling, or money services. It also can’t process an application while a freeze is in place at ChexSystems, a company that reports on checking account history, and it asks applicants to lift any TransUnion credit freeze first.
Help comes through one number, 844-678-2726. Relationship managers answer weekdays from 6 a.m. to 6 p.m. Pacific time, and after hours, on weekends, and on holidays the line handles fraud alerts, card services, and urgent problems. The Visa debit card and any checks ordered with the application arrive in seven to 10 business days.
Axos Basic Business Checking costs close to nothing to run. It has no monthly fee, minimum, or transaction cap, it refunds other banks’ ATM fees, and it covers two outgoing wires a month, so a business paid by card, bank transfer, or wire pays little beyond overdrafts and extra wires.
A business that handles cash or paper checks every week will wait on its money, since both can take until the fifth business day to become available, and would do better at a bank with a branch nearby. One that keeps a large balance earns nothing here, where Axos’s Business Interest Checking or Business Premium Savings would pay interest. Freelancers and online businesses paid electronically should open it. A business formed within the past year should apply with code START200 by January 31, 2027, and keep $3,000 in it for four of its first five statement cycles to collect the full $200.
Learn more about Axos Basic Business Checking or see how it compares to the best small business checking accounts.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
It has been revealed that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every organization or offer available in the marketplace.
General
⚖️ Neutral
🌐 Physicianonfire
#21773. Industry News: The Sunday Best (10/18/2026)
📅 18 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
Industry News: The Sunday Best (10/18/2026)
📅 18 Oct 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
In 1980, a benefits consultant named Ted Benna figured out how to.
General
⚖️ Neutral
🌐 Investing
#21772. Exclusive-Authorities raid factory making illegal Chinese vapes in the US
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Exclusive-Authorities raid factory making illegal Chinese vapes in the US
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Investing
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #17483. Scout's New Factory Is Already Making Trucks. But You Won't Be Able To Buy One For A While 📰 #12410. Turkish authorities raid opposition Sozcu news channel, appoint new management 📰 #23616. Tech Report: Latest US rules aim to restrict Chinese firms’ remote access to AI servers and infrastructure
General
⚖️ Neutral
🌐 Choosefi
#21771. JAL Business Class via Multiple Transfer Partners
📅 04 Nov 2026 • ⏱️ 16m • 📚 Deep Dive (3297 w)
JAL Business Class via Multiple Transfer Partners
📅 04 Nov 2026 | ⏱️ 16 min read (3297 words, 📚 Deep Dive) | Source: Choosefi
⏱️ ~16 mins left to finish
📖 0% read
💡 Key Takeaways
- World-class Japanese hospitality at a fraction of the cash price via partner bookings.
- Sources indicate that picture this: you're settled into your own private suite at 37,000 feet somewhere over the Pacific.
- The core insight here is deceptively simple: JAL's own frequent flyer program is not where you want to book this award.
World-class Japanese hospitality at a fraction of the cash price via partner bookings.
Fuel Surcharges via Partner Programs.
Sources indicate that picture this: you're settled into your own private suite at 37,000 feet somewhere over the Pacific. The door closes. A flight attendant in a crisp JAL uniform offers you a warm towel and asks how you'd like your appetizer served. The flat bed is already made with a proper duvet. Outside the window, the sun is setting over the ocean. You're nine hours into a 12-hour flight to Tokyo, and you feel more rested than you did when you boarded. This is JAL's Sky Suite — one of the most celebrated business class products in the world — and with the right travel rewards strategy, your family can experience it for a fraction of what everyone else is paying. Here's the math that stops people cold: a round-trip business class ticket from San Francisco to Tokyo on JAL typically retails for **$5,000 to $10,000 per person**. That's not a typo. Premium transcontinental fares are genuinely that expensive, and most people simply accept that they'll never sit up front on a 12-hour flight across the Pacific. But the ChooseFI community knows better. That same seat — the same flat bed, the same Champagne, the same Sky Suite cocoon — is available for **60,000 miles** when booked through Alaska Mileage Blueprint or American AAdvantage. At a retail value of $5,000 to $10,000, you're looking at **8.3 to 16.7 cents per point** in value. For context, most travel rewards experts consider anything above 1.5 cents per point a good redemption. This one can be up to *eleven times* that benchmark. The pricing inefficiency exists because partner award programs — like Alaska and American — use fixed award charts that were negotiated years ago, before JAL's hard product became one of the most sought-after cabins in the sky. JAL hasn't raised these partner pricing levels proportionally as cash fares have climbed. The gap between what you pay in points and what the market charges in dollars is enormous, and it's yours to exploit right now. This isn't a loophole that's about to close tomorrow. It's a structural feature of the loyalty system — one that rewards people who understand how to use their points strategically rather than burning them on domestic economy upgrades. For anyone on the path to financial independence, where every dollar and every point is treated with intention, this is exactly the kind of asymmetric opportunity worth understanding.
The core insight here is deceptively simple: JAL's own frequent flyer program is not where you want to book this award. This is the aha moment that separates casual points users from strategic ones.
According to recent reports, JAL operates its own loyalty program — JAL Mileage Bank — but it charges significant fuel surcharges on its own award tickets, often running $100 to $500 or more per ticket. When you book JAL business class through JAL Mileage Bank itself, those surcharges erode a substantial portion of your points value before you even leave the ground. The ChooseFI community's editorial guidance here is unambiguous: book JAL through partner programs to avoid this tax on your redemption.
There are two primary programs where you can book JAL business class at 60,000 miles round-trip on the transpacific route:.
Alaska Mileage Initiative prices JAL business class at 60,000 miles for a round-trip between North America and Japan. Alaska is a oneworld partner of JAL and honors JAL's genuinely strong award availability. Critically, Alaska does not pass through JAL's fuel surcharges to awards booked through Mileage Plan. This is a massive advantage.
American AAdvantage also prices the same route at 60,000 miles round-trip. Both programs use fixed award charts, meaning the price doesn't fluctuate with demand the way cash fares do — a $10,000 ticket at peak cherry blossom season costs exactly the same points as a ticket in a slower travel month.
According to recent reports, neither Alaska Mileage Strategy nor American AAdvantage is a direct transfer partner from the major US bank programs in the same way Chase or Amex partners work. However, you have real pathways:.
For Alaska and American miles specifically, the strongest earning strategies involve:.
According to recent reports, both Alaska and American use fixed award charts — meaning the price in miles is the same regardless of how high the cash price climbs. This is the structural inefficiency at work. A seat that retails for $10,000 during peak season still costs 60,000 miles. The chart doesn't care about demand; it just prices by region and cabin. As long as JAL releases availability — and they do — the gap between cash cost and points cost remains enormous.
JAL also allows one free stopover and one open jaw per round-trip award, which means you can potentially add a stop in Tokyo itself while continuing to another Japanese city, or fly into one city and out of another — all at no additional miles cost.
This is the cardinal rule of all travel rewards bookings: never transfer points until you have confirmed availability. Points transfers are generally irreversible.
Go to ba.com (British Airways Executive Club) to search for JAL award availability. Because BA is also a oneworld partner, their search tool indicates you JAL award space. Search for your route (e.g., SFO to NRT) in business class. Any availability you see here is almost certainly bookable through Alaska or American as well. Look for "J" class availability, which represents business class award space.
Sources indicate that you can also call Alaska Airlines at 1-800-252-7522 or American Airlines at 1-800-433-7300 and ask their agents to search JAL availability on your dates. Agents sometimes see space that doesn't show up online.
Sources indicate that JAL's booking window opens 360 days in advance. For peak travel periods — Golden Week in Japan (late April to early May), cherry blossom season (late March to early April), and the summer holidays — availability disappears fast. Set a calendar reminder to search and book as soon as the window opens for your target dates.
Industry observers note that for travel year-round outside those peaks, JAL is known for releasing strong business class availability, which is why this sweet spot earns a 4/5 on availability. You have real flexibility here.
Decide whether you'll book through Alaska Mileage Initiative or American AAdvantage. Both charge 60,000 miles round-trip. The key differentiator: Alaska does not pass through fuel surcharges. If minimizing out-of-pocket costs is your priority, Alaska is the better choice.
For Alaska miles: Apply for the Bank of America Alaska Airlines Visa, earn the welcome bonus, and use shopping portals and partner promotions to top up. For American miles: The Citi AAdvantage Platinum Select or Barclays AAdvantage Aviator cards offer solid welcome bonuses. You'll need a minimum of 60,000 miles per person.
If you need to use the Capital One → JAL Mileage Bank transfer path, initiate the transfer from your Capital One portal. Transfers post in 1-2 days. Note that booking through JAL Mileage Bank directly will incur fuel surcharges.
For Alaska: Call 1-800-252-7522 or book online at alaskaair.com/partner-awards. Online booking of JAL awards through Alaska can be hit-or-miss; calling is often more reliable.
Industry observers note that for American: Book at aa.com or call. American's website allows partner award searches, though calling often surfaces additional availability.
According to recent reports, once booked, confirm your ticket number, that the cabin reveals as "Business" (not an upgrade), and request your preferred meal. JAL offers Western and Japanese meal options — request ahead. Your seat assignment on the 787-9 Sky Suite or 777-300ER Apex Suite can be made at booking.
It has been revealed that the core arbitrage here is the difference between booking through JAL's own program versus booking through oneworld partner programs. JAL Mileage Bank imposes significant fuel surcharges on its own award tickets — often $100 to $500 per ticket — which erodes the points value substantially. But Alaska Mileage Plan and American AAdvantage can book the exact same JAL-operated flights with zero fuel surcharges because they use their own award charts and pricing rules. You are flying on JAL's aircraft with JAL's crew and JAL's business class product, but paying through a partner program's more favorable pricing. This is the same structural mismatch that creates sweet spots throughout the oneworld alliance — the booking program's pricing does not match the operating airline's product quality.
Let's run the numbers on a specific scenario that thousands of ChooseFI members have used as a benchmark: San Francisco (SFO) to Tokyo Narita (NRT) in JAL business class, round-trip for two people.
Industry observers note that A quick search on Google Flights or JAL's own website for this route in business class will typically show cash prices ranging from $5,000 to $10,000 per person — let's use $7,000 as a reasonable midpoint for this example. For two people, you're looking at a $14,000 cash outlay before you even think about hotels in Tokyo.
In a recent development, booked through Alaska Mileage Initiative: 60,000 Alaska miles per person, round-trip. For two travelers, that's 120,000 Alaska miles total, plus taxes and fees (which Alaska keeps minimal for JAL awards, typically under $100 for the pair).
The CPP math: $7,000 in value ÷ 60,000 miles = 11.7 cents per point — squarely in the middle of the 8.3-to-16.7-cent range and nearly 8 times what most people get burning points on domestic economy tickets.
It has been revealed that on JAL's Boeing 787-9, you'll be seated in the Sky Suite — a fully flat, forward-facing seat with a sliding door for privacy. The seat converts to a 186-cm flat bed with a proper mattress pad and duvet. The personal screen is one of the largest in the sky at 23 inches.
On the 777-300ER, you may get the Apex Suite — a staggered configuration with direct aisle access from every seat and a similarly flat, private sleeping environment.
Beyond the hardware: JAL's service is routinely ranked among the best in the world. The meal service for a 12-hour transpacific flight is multi-course, the sake selection is curated, and the attention to detail in Japanese hospitality culture elevates the experience above what the points price alone suggests.
You'll also access the JAL First Class Lounge or JAL Business Class Lounge at Narita on the return — another perk included with your business class boarding pass. By the time you land in San Francisco after a flat-bed sleep and a proper breakfast service, you've experienced what most travelers save for a once-in-a-lifetime trip. With travel rewards, it can be your default way to cross the Pacific.
British Airways' award search at ba.com is one of the best tools for seeing oneworld partner availability without committing any miles. Use it to scout JAL space across multiple dates before you transfer a single point. It shows business class availability clearly and rapidly.
Recent findings suggest that JAL's award calendar opens 360 days in advance. For anyone targeting cherry blossom season (late March to early April) or Golden Week (late April to early May), you should be searching and booking at the 360-day mark, not 60 days out. These are the hardest windows to find availability. Outside peak Japan travel seasons, this is much more forgiving.
JAL Mileage Bank allows one free stopover and one open jaw per round-trip award. If you're booking through JAL Mileage Bank directly (accepting the fuel surcharges), you can fly into Tokyo and out of Osaka, for example, without additional miles. This is a genuine value-add for anyone planning a broader Japan itinerary — no backtracking required.
It has been revealed that this is a small thing that makes a massive difference. Request the Japanese meal option when booking. It's more authentic, better-suited to the overall experience, and — in the ChooseFI spirit of intentionality — it's why you chose this airline over a generic carrier.
Sources indicate that this is the single most common and most painful mistake. Points transfers are almost always one-way and irreversible. Never, under any circumstances, transfer points to a program before you have verbal or written confirmation of the award space you intend to book.
In a recent development, as emphasized in the program overview: JAL charges significant fuel surcharges on awards booked through its own program — $100 to $500 or more. For transpacific routes, always book through Alaska or American to avoid these fees. The data is explicit on this point.
In a recent development, if you do earn JAL Mileage Bank miles directly, note that they expire 36 months from the date earned on a rolling basis. If you let a balance sit idle, you may lose miles before you've accumulated enough to book. Keep the balance active through small purchases or partner activity.
Industry observers note that this sweet spot is best suited for couples and individual travelers who are targeting Japan specifically — whether it's a bucket-list trip, a first visit to Tokyo, or a multi-city Japan itinerary. The fixed 60,000-mile price per person means that families with young children will need to accumulate significant balances (60,000 miles per ticketed passenger), which pushes the complexity and earning requirement higher.
In a recent development, you need a minimum of 60,000 Alaska miles or 60,000 American AAdvantage miles per person to execute this redemption. For a couple, that's 120,000 miles — achievable with two well-chosen credit card welcome bonuses plus some additional earning through everyday spending or partner promotions.
Recent findings suggest that this redemption is not ideal for beginners — it scores 2/5 on beginner-friendliness, and honestly, that's accurate. The booking path involves navigating partner award searches, understanding the difference between booking programs (Alaska vs. JAL Mileage Bank) and why it matters for surcharges, and potentially calling airlines rather than booking online. If you're on your first or second travel rewards card and still building your foundational understanding, this is one to put on a future list while you sharpen your skills.
According to recent reports, for the FI-focused traveler who has been in the travel rewards ecosystem for a year or more, this is a landmark redemption. The CPP ceiling of 16.7 cents per point represents one of the highest-value uses of any points in a North American loyalty portfolio. If you believe in maximizing every dollar you earn and every point you accumulate — and the ChooseFI community does — this is the kind of redemption that justifies the entire system.
This redemption is rated **moderate difficulty**, and that rating is honest. It's not the most complex thing in the travel rewards world, but it has enough moving parts that going in without preparation can lead to frustration or costly mistakes. **What specifically makes it moderate:** First, the **earning path is not plug-and-play**. Unlike Chase Ultimate Rewards or Amex Membership Rewards, which transfer to dozens of partners instantly, Alaska miles and American miles are earned primarily through co-branded credit cards and flying. There's no one magic transferable currency that flows directly into these programs at full value. Second, **the booking process often requires a phone call**. Online partner award booking through Alaska and American works inconsistently. Many experienced travelers report that calling the airline's award desk surfaces availability that the website doesn't show — which is a normal part of the process but adds friction. Third, **fuel surcharge awareness matters**. Understanding *why* you book through Alaska or American instead of JAL Mileage Bank directly is a non-obvious nuance that could cost you real money if you don't get it right. **Three tips to overcome the challenge:** 1. **Use BA.com as your availability scouting tool** — it gives you a clean, visual look at JAL award space without committing any miles. 2. **Call Alaska or American directly** when online searches fail. Agents are well-versed in partner award booking and can often find and hold space while you confirm your miles balance. 3. **Build your miles balance before you start searching.** Having 70,000+ miles in hand (a small buffer above 60,000) before you begin reduces stress and gives you flexibility on dates. If you've already completed one or two simpler travel rewards bookings and understand the basics of award searches, this is well within reach. The effort is real — and the payoff is a flat bed over the Pacific.
Go to ba.com (British Airways Executive Club) and search for your route in business class. Because BA is a oneworld partner, their search tool reveals JAL award space. Search across multiple dates to find availability. Any space you see here is almost certainly bookable through Alaska or American as well.
Both charge 60,000 miles one-way with no fuel surcharges. Alaska miles can be earned through the Alaska Airlines Visa card or transferred from Marriott Bonvoy (3:1). AAdvantage miles can be earned through Citi cards or transferred from various hotel programs. Choose based on which miles you have or can earn most efficiently.
Industry observers note that only transfer points after confirming award availability on ba.com. For Alaska, earn through card spending or Marriott transfers. For AAdvantage, earn through Citi cards. Never transfer before confirming space — transfers are generally irreversible.
Sources indicate that call Alaska Mileage Proposal or book on aa.com to ticket the JAL-operated flight. For Alaska, phone booking is required for partner awards. For AA, search on aa.com and book online if the JAL space appears. Confirm your JAL seat assignment on jal.com after ticketing.
JAL Mileage Bank imposes fuel surcharges on its own award tickets, often adding $100 to $500 per ticket on transpacific routes. Alaska Mileage Strategy and American AAdvantage book the exact same JAL-operated flights at the same 60,000-mile price but with zero fuel surcharges. You fly the same plane, same seat, same service — but pay significantly less out of pocket.
JAL opens its award calendar approximately 360 days in advance. For peak seasons like cherry blossom season (late March to early April) and Golden Week (late April to early May), you should begin searching the day the window opens. Off-peak dates are generally easier to find with 3 to 6 months of lead time.
Not directly, but you can use Chase points indirectly. Transfer Chase Ultimate Rewards to British Airways Avios and book JAL through BA's oneworld partnership. However, BA charges fuel surcharges on partner awards, so this path is less favorable than Alaska or AA. The cleanest Chase path is to earn Alaska or AA miles through other means.
JAL Sky Suite business class features angled lie-flat or fully lie-flat seats depending on the aircraft, with a privacy shell, excellent Japanese cuisine, attentive service, and premium amenity kits. The service quality is consistently praised as among the best in the industry. On 777-300ER and 787 aircraft, the product competes with top-tier offerings from Singapore Airlines and Cathay Pacific.
According to recent reports, this sweet spot was last verified over 90 days ago. Award availability and pricing may have changed — verify current rates before booking.
Sources indicate that JAL business class via Alaska Mileage Plan or American AAdvantage is the definitive sweet spot for anyone targeting Japan. At 60,000 miles one-way with zero fuel surcharges, you are booking a $5,000 to $10,000 cash experience for a fraction of the cost through a partner program pricing arbitrage. The key is searching ba.com for availability before transferring a single point, booking 360 days out for peak cherry blossom or Golden Week dates, and choosing between Alaska and AA based on which miles you can earn most efficiently. JAL's business class product — lie-flat seats, exceptional cuisine, and Japanese hospitality — delivers an experience that justifies the points spend and then some. This is the redemption that puts Japan within reach for every FI-minded traveler.

General
⚖️ Neutral
🌐 Physicianonfire
#21770. Year-End Tax Planning for Physicians. What To Do Before 2026 Is Over
📅 19 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (90 w)
Year-End Tax Planning for Physicians. What To Do Before 2026 Is Over
📅 19 Oct 2026 | ⏱️ 1 min read (90 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
According to recent reports, the bonus-timing example is concrete: a $20,000 bonus paid Dec. 20 lands in 2026 wages, while a Jan. 5 pay date pushes the same dollars into 2027 and, at a 35% marginal rate, delays about $7,000 of federal tax for a year. Pairing that with the 2026 HSA ceilings ($4,400 self-only / $8,750 family, plus $1,000 catch-up at 55+) and the checklist on accelerating or deferring deductions gives employed physicians a short year-end punch list even when W-2 wages themselves are inflexible.
General
⚖️ Neutral
🌐 Moneycrashers
#21769. No Itemizing Needed – Deduct Up to $1,000 of Cash Gifts to Charity From 2026
📅 16 Nov 2026 • ⏱️ 3m • 📚 Deep Dive (502 w)
No Itemizing Needed – Deduct Up to $1,000 of Cash Gifts to Charity From 2026
📅 16 Nov 2026 | ⏱️ 3 min read (502 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~3 mins left to finish
📖 0% read
💡 Key Takeaways
- Starting with your 2026 return, you can deduct up to $1,000 of cash gifts to eligible charities while taking the standard deduction, or $2,000 on a joint return.
- The IRS’s Working Families Tax Cuts page says, “Beginning with tax year 2026, individuals who do not itemize may deduct up to $1,000 of cash contributions made to eligible charitable organizations ($2,000 for married taxpayers filing jointly).” It’s permanent, unlike the temporary version for 2020 and 2021.
- Recent findings suggest that two words in that rule decide which gifts count.
Starting with your 2026 return, you can deduct up to $1,000 of cash gifts to eligible charities while taking the standard deduction, or $2,000 on a joint return. Give by check, card, or bank transfer straight to the charity, since donated goods, stock, and gifts to donor-advised funds don’t count. Keep a bank record or receipt for every gift.
The IRS’s Working Families Tax Cuts page says, “Beginning with tax year 2026, individuals who do not itemize may deduct up to $1,000 of cash contributions made to eligible charitable organizations ($2,000 for married taxpayers filing jointly).” It’s permanent, unlike the temporary version for 2020 and 2021.
Recent findings suggest that two words in that rule decide which gifts count. The first, cash, means money, given in bills or by check, card, bank transfer, or payroll deduction. Clothing, stock, and other property don’t count, and neither do deductions carried over from earlier years.
The second, eligible, rules out some gifts of money. Donations to a supporting organization, a charity set up to support other charities, don’t count, and neither do donations to a donor-advised fund, which only itemizers can deduct.
Industry observers note that look each charity up in the IRS’s Tax Exempt Organization Search. Its deductibility code reads PC for a public charity, which qualifies, and starts with SO for a supporting organization. A church can qualify without appearing there. For every gift, keep a bank record or receipt showing the charity’s name, the date, and the amount, plus the charity’s written acknowledgment for any single gift of $250 or more.
Say a married couple in the 12% bracket takes the standard deduction and gives $150 a month by card, split between their church and a food bank. That’s $1,800 for 2026, all deductible under the $2,000 limit on a joint return, so their tax drops by $216. Since no single gift reaches $250, their card statements are all the records they need.
From 2026, itemizers can deduct only the part of their gifts above 0.50% of adjusted gross income. If your itemized deductions come close to the standard deduction, count your gifts both ways before you take the standard deduction or itemize, and consider bunching two years of gifts into a year you itemize.
Recent findings suggest that make a gift by Dec. 31 for it to count on that year’s return. A mailed check counts the day you mail it, and a card gift in the year it’s charged, not the year you pay the bill.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Sources indicate that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.
General
📈 Bullish
🌐 Investing
#21768. Hidroelectrica 9M 2026 presentation: profit surges despite drought
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Hidroelectrica 9M 2026 presentation: profit surges despite drought
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Investing
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #18195. HD Stock Falls 2% Despite Home Depot Earnings Beat as Profit Outlook Tightens 📰 #23499. Latest Update: Nebraska voters appear to reject online sports betting despite nearly $22.5 million campaign 📰 #23474. Breaking: FanDuel US profit falls 94% to $3 million as Flutter spends on FanDuel Predicts
General
⚖️ Neutral
🌐 Investing
#21767. Business inventories align with forecasts, indicating stable demand
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Business inventories align with forecasts, indicating stable demand
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Investing
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #15865. Business inventories rise in line with consensus; retail inventory growth increases, 📰 #23640. Intel bets on Classiq acquisition to turn Quantum efforts into commercially viable business 📰 #23244. Unlocking Stable On-Policy RL on TPU with Bitwise-Zero Train–Inference Mismatch
Business & Policy
⚖️ Neutral
🌐 Investing
#21766. Why is CVS Health stock sliding today?
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Why is CVS Health stock sliding today?
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Investing
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
General
⚖️ Neutral
🌐 Moneycrashers
#21765. Best Small-Business Credit Cards – Match the Card to Your Biggest Costs
📅 16 Nov 2026 • ⏱️ 6m • 📚 Deep Dive (1210 w)
Best Small-Business Credit Cards – Match the Card to Your Biggest Costs
📅 16 Nov 2026 | ⏱️ 6 min read (1210 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- It has been revealed that pick a small-business card by where most of your company’s spending goes.
- In a recent development, of the small businesses with employees that regularly use a credit card, 8% pay with a personal card alone and 34% mix personal and business cards, according to the Federal Reserve Banks’ Small Business Credit Survey.
- Each card below is judged by what a business putting $5,000 a month on it, in the categories where it pays most, would earn in a year after the annual fee.
It has been revealed that pick a small-business card by where most of your company’s spending goes. Put scattered costs on a no-fee card paying 2% on everything, and big monthly bills for shipping and travel on the Ink Business Preferred, which earns more there even after its $95 fee. Pay a higher fee only for perks you’ll use.
In a recent development, of the small businesses with employees that regularly use a credit card, 8% pay with a personal card alone and 34% mix personal and business cards, according to the Federal Reserve Banks’ Small Business Credit Survey. A card of the business’s own keeps its costs on one statement, where they’re easier to track and to deduct at tax time, and it pays rewards on spending the business does anyway.
Each card below is judged by what a business putting $5,000 a month on it, in the categories where it pays most, would earn in a year after the annual fee. Points and miles are valued at a cent each, what Chase, American Express, Capital One, and Delta pay for them in cash or toward travel. An LLC or corporation with cash in the bank can get an EIN-only corporate card, approved on its federal tax ID, cash, and revenue, so the owner signs no personal guarantee. Sole proprietors who haven’t formed a organization can choose among no-fee business cards for freelancers. Travelers loyal to an airline or hotel chain other than Delta or Marriott can weigh that brand’s airline credit card or hotel credit card.
Any purchase earns its 2%, with no categories or cap, so a business putting $5,000 a month on it brings in $1,200 a year, with no annual fee.
For more information, read our full Wells Fargo Signify Business Cash® Card Review.
In a recent development, keep a $10,000 balance in qualifying U.S. Bank business checking, and the first $10,000 of purchases each billing cycle earns 2.5%, $1,500 a year on $5,000 a month, instead of 2%.
For more information, read our full U.S. Bank Business Essentials™ Visa® Card Review.
At $5,000 a month, its 2% nets $1,050 a year after the $150 annual fee, but the fee is refunded in any year you spend at least $150,000, and there’s no preset spending limit.
For more information, read our full Capital One Spark Cash Plus Review.
Put $5,000 a month on single purchases of $5,000 or more, and its 2.5% earns $1,500 a year, $1,305 after the $195 fee, while smaller purchases earn 2%.
For more information, read our full Ink Business Premier® Credit Card Review.
Each pays 1% or 1 point a dollar outside the categories where it pays more, so it beats a card paying 2% on everything only when those categories take a big share of your spending.
Shipping, travel, phone and internet bills, and ads on social media and search engines earn 3 points a dollar, so $5,000 a month there pays $1,800 a year in cash, $1,705 after the $95 fee.
For more information, read our full Ink Business Preferred® Credit Card Review.
Your top two of six categories each month earn 4 points a dollar, so $5,000 a month there brings $2,400 a year in Amex Travel flights, $2,025 after the $375 fee.
For more information, read our full American Express® Business Gold Card Review.
Office supply store purchases and phone, internet, and cable bills earn 5% on the first $25,000 each account year and 1% after, so $5,000 a month there pays $1,600 a year with no annual fee.
For more information, read our full Ink Business Cash® Credit Card Review.
With no yearly cap on its 3%, $5,000 a month at office supply stores, cell phone carriers, and restaurants earns $1,800 a year with no annual fee.
Sources indicate that for more information, read our full U.S. Bank Triple Cash Rewards Visa® Business Card Review.
Amazon.com, Amazon Business, AWS, and Whole Foods purchases earn 5% on the first $150,000 a year, so $5,000 a month there pays $3,000 a year, with no annual fee beyond the Prime membership it requires.
For more information, read our full Prime Business World Elite Mastercard® Review.
Every dollar earns 2 points up to $50,000 a year and 1 after, so $5,000 a month brings 110,000 points a year, worth $1,100 in flights through Amex Travel, with no annual fee.
For more information, read our full The Blue Business® Plus Credit Card from American Express Review.
Spending $5,000 a month earns 120,000 miles a year at 2 a dollar, $1,200 toward travel, and a $300 credit for Capital One Business Travel bookings plus 10,000 anniversary miles cover the $395 fee.
For more information, read our full Capital One Venture X Business Review.
Amex Travel flights and prepaid hotels earn 5 points a dollar, so $5,000 a month there brings $3,000 a year in Amex Travel flights, $2,105 after the $895 fee, plus over 1,550 airport lounges.
For more information, read our full The Business Platinum Card® from American Express Review.
Delta purchases earn 3 miles a dollar, so $5,000 a month there brings 180,000 miles a year, worth about $1,800 off Delta tickets, $1,150 after the $650 fee, plus 15 Sky Club visits.
For more information, read our full Delta SkyMiles® Reserve Business American Express Card Review.
Marriott stays earn 6 points a dollar, so $5,000 a month brings 360,000 points a year, about 10 nights at 35,000 points each, and its $125 fee buys Gold status and a yearly free night.
For more information, read our full Marriott Bonvoy Business® American Express® Card Review.
It pays no rewards, but 0% for 15 billing cycles on purchases is the longest intro period here for paying off a substantial purchase, with no annual fee.
For more information, read our full Bank of America® Platinum Plus® Mastercard® Business Credit Card Review.
Its credit line equals your deposit of $1,000 or more, and it builds your business’s credit while paying 1.5%, $900 a year on $5,000 a month with a deposit to match.
For more information, read our full Bank of America® Business Advantage Unlimited Cash Rewards Mastercard® Secured Credit Card Review.
Sources indicate that the choice comes down to whether a few costs make up most of your spending each month. Put spread-out spending on a flat 2% card with no fee, and move to a category or travel card once the extra rewards on one big cost would beat that card’s annual fee.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Editorial Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. Compensation does not influence our editorial evaluations, ratings, or opinions.
It has been revealed that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every tech giant or offer available in the marketplace.
🔗 Related Articles
📰 #21784. Industry News: Best Secured Credit Cards – No Annual Fee and a Path to a Regular Card 📰 #19070. Tech Report: Capital One business credit cards for upcoming LLCs: Which card to get based on your credit history 📰 #21759. Industry News: Best Cash Back Credit Cards – What Each Pays on $2,000 a Month
General
⚖️ Neutral
🌐 Physicianonfire
#21764. You’re Not Rich — And Neither Am I
📅 20 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (146 w)
You’re Not Rich — And Neither Am I
📅 20 Oct 2026 | ⏱️ 1 min read (146 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
Good, thoughtful article, Thanks! I have to agree about the ongoing obligations that the treadmill gets us into. I have to identify with Dr Net-Worth, but rather than having no purpose, I would say that one real, tangible benefit he has is security. Knowing he or his spouse can incur some life altering accident or illness and not affect the well being of the rest of the family. As an example my mother in law has dementia and has been in memory care for a decade. Her current bill is 200k per year. She and her husband planned very well and regardless of how long she lives she will be taken care of. The kids have not needed to contribute at all. My household has planned in a similar way. I know I will never need to be supported by my kids.
🔗 Related Articles
📰 #22885. Industry News: Forget Plain Butter: Drizzle This Rich Ingredient Over Stuffing For 10x The Flavor 📰 #22844. Scrambled Eggs Get A Major Protein And Flavor Boost When You Add This Omega-Rich Ingredient 📰 #21642. Tech Report: #759: My Bank Account Hit Zero … Then I Got Rich — with Jaspreet Singh of Minority Mindset
AI & Tech
📈 Bullish
🌐 Investing
#21763. Bentley Systems at RBC conference: growth, AI and a bigger runway
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Bentley Systems at RBC conference: growth, AI and a bigger runway
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Investing
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #21757. Gilead at Jefferies Global Healthcare Conference: growth broadens 📰 #23590. Disney indicates more layoffs are on the way as manufacturer introduces double-digit Q4 revenue growth 📰 #23583. Networking is awkward: Marriott and Second City want to improve your conference experience with improv
General
⚖️ Neutral
🌐 Investing
#21762. Springer Nature 9M 2026 slides: research strength drives upgraded outlook
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Springer Nature 9M 2026 slides: research strength drives upgraded outlook
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Investing
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
General
⚖️ Neutral
🌐 Investing
#21761. Merck declares $0.88 quarterly dividend for Q1 2027
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Merck declares $0.88 quarterly dividend for Q1 2027
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Investing
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #21795. Industry News: T. Rowe Price: The Dividend Is Attractive, But The Turnaround Is Still Missing 📰 #18978. Russell Brand declares ‘I am not guilty’ in latest statement from prison 📰 #18336. Latest Update: ‘I hope this email finds you’: Microsoft declares outage over as the world digs out of its inbox
General
⚖️ Neutral
🌐 Physicianonfire
#21760. Breaking: The White Coat Is the Pirate Suit: What Backrooms Gets Right About a Doctor’s Life
📅 23 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
Breaking: The White Coat Is the Pirate Suit: What Backrooms Gets Right About a Doctor’s Life
📅 23 Oct 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
In 1980, a benefits consultant named Ted Benna figured out how to.
General
⚖️ Neutral
🌐 Moneycrashers
#21759. Industry News: Best Cash Back Credit Cards – What Each Pays on $2,000 a Month
📅 16 Nov 2026 • ⏱️ 4m • 📚 Deep Dive (789 w)
Industry News: Best Cash Back Credit Cards – What Each Pays on $2,000 a Month
📅 16 Nov 2026 | ⏱️ 4 min read (789 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~4 mins left to finish
📖 0% read
💡 Key Takeaways
- In a recent development, start with a no-fee flat 2% cash back card such as the Citi Double Cash, which pays about $480 a year on $2,000 a month.
- The average rate on bank credit card accounts that were charged interest was 22.36% in the third quarter of 2026, by the Federal Reserve’s preliminary figures.
- Every yearly figure below is for one sample household, which puts $2,000 a month on the card: $500 on groceries at supermarkets, $300 at restaurants, $200 on gas, $300 on utility and phone bills, and $700 on everything else.
In a recent development, start with a no-fee flat 2% cash back card such as the Citi Double Cash, which pays about $480 a year on $2,000 a month. Switch to a card that pays more in one category only when a large share of your spending goes there. Either way, pay in full, since balances charged interest average over 22% a year.
The average rate on bank credit card accounts that were charged interest was 22.36% in the third quarter of 2026, by the Federal Reserve’s preliminary figures. A dollar left unpaid for a year at that rate costs more than 22 cents in interest, several times what any of these cards pays back on it. So every pick assumes you pay the full balance each month.
Every yearly figure below is for one sample household, which puts $2,000 a month on the card: $500 on groceries at supermarkets, $300 at restaurants, $200 on gas, $300 on utility and phone bills, and $700 on everything else. The figures subtract any annual fee and leave out welcome offers. Each pick is the strongest of its kind on its rates, spending caps, payout rules, sign-up offer, and 0% interest period taken together.
The sample household collects about $480 a year with no categories to track and no cap, more than most category cards on this list pay on a budget this spread out.
For more information, read our full Citi Double Cash® Card Review.
Most cards’ grocery rates leave out Walmart and Target, so where a household buys its groceries decides which of the best credit cards for groceries pays it most.
On the sample budget it pays about $493 a year after its $95 annual fee, which starts in year two, and it tops a flat 2% card once supermarket spending passes about $480 a month.
For more information, read our full Blue Cash Preferred® Card from American Express Review.
Plenty of no-fee cards pay 3% or more at restaurants, so what a card pays beyond dining decides the pick among the best credit cards for dining out.
It pays the sample household about $432 a year with no annual fee, and it tops a flat 2% card once groceries, dining, entertainment, and streaming take over half your spending.
For more information, read our full Capital One Savor Cash Rewards Credit Card Review.
Gas rewards often come with a spending cap or a warehouse club membership, so check both before you choose among the best gas credit cards.
A household that already pays for a Costco membership and buys its groceries and gas there gets about $468 a year on the sample budget, $120 of it from gas.
For more information, read our full Costco Anywhere Visa® Card by Citi Review.
Activate each quarter’s 5% categories, and on 2026’s calendar the sample household earns about $420 a year, which Cashback Match doubles to about $840 at the end of the first year.
For more information, read our full Discover it® Cash Back Review.
Pick home utilities and cell phone as its two 5% categories and groceries for its 2%, and the sample household earns about $444 a year, $180 of it from those bills.
It has been revealed that for more information, read our full U.S. Bank Cash+® Visa Signature® Card Review.
Ordering the sample household’s $500 a month of groceries through Instacart brings in about $540 a year, $300 of it on those orders alone.
For more information, read our full Instacart Mastercard® Review.
According to recent reports, on a spread-out budget, a flat 2% card earns about what most category cards do, and it needs no tracking. Add up a month of card statements by category, then pick the card whose top rate covers the category that takes the biggest share.
For spending that happens mostly online, compare the best credit cards for online shopping, or the best credit cards with no annual fee to keep every card you carry free.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
In a recent development, editorial Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. Compensation does not influence our editorial evaluations, ratings, or opinions.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every organization or offer available in the marketplace.
General
⚖️ Neutral
🌐 Investing
#21758. Gold stabilizes after hitting over one-year low
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Gold stabilizes after hitting over one-year low
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Investing
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #23480. Breaking: Arkansas sues VGW and Kalshi, citing $66 million in VGW taxable sales in one year 📰 #23071. AnyLanguageModel 1.0: One Year of Local Models on Apple Platforms 📰 #21688. Latest Update: Monarch Money Review – Every Household Account in One Shared App, for $99.99 a Year
General
📈 Bullish
🌐 Investing
#21757. Gilead at Jefferies Global Healthcare Conference: growth broadens
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Gilead at Jefferies Global Healthcare Conference: growth broadens
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Investing
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #21839. Ascendis Pharma A/S (ASND) Presents at Jefferies Global Healthcare Conference 2026 Transcript 📰 #21813. Tech Report: Illumina, Inc. (ILMN) Presents at Jefferies Global Healthcare Conference 2026 Transcript 📰 #21756. Nuvation Bio at Jefferies Global Healthcare Conference: pipeline gains
General
📈 Bullish
🌐 Investing
#21756. Nuvation Bio at Jefferies Global Healthcare Conference: pipeline gains
📅 17 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (7 w)
Nuvation Bio at Jefferies Global Healthcare Conference: pipeline gains
📅 17 Nov 2026 | ⏱️ 1 min read (7 words, ⚡ Quick Read) | Source: Investing
⏱️ ~1 mins left to finish
📖 0% read
Content not available.
🔗 Related Articles
📰 #21839. Ascendis Pharma A/S (ASND) Presents at Jefferies Global Healthcare Conference 2026 Transcript 📰 #21813. Tech Report: Illumina, Inc. (ILMN) Presents at Jefferies Global Healthcare Conference 2026 Transcript 📰 #21757. Gilead at Jefferies Global Healthcare Conference: growth broadens
General
⚖️ Neutral
🌐 Moneycrashers
#21755. Vanguard Digital Advisor Review – Low-Cost Index Investing With No Human Advisor
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (255 w)
Vanguard Digital Advisor Review – Low-Cost Index Investing With No Human Advisor
📅 16 Nov 2026 | ⏱️ 1 min read (255 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Open Vanguard Digital Advisor if you want a portfolio of Vanguard index funds built, rebalanced, and managed with taxes in mind, for an advisory fee of about $15 to $16 a year per $10,000.
- Digital Advisor is Vanguard’s robo-advisor, a service that builds and rebalances a portfolio for you by algorithm.
- According to recent reports, hands-off investors who enroll both a taxable account and an IRA get the most for the fee, since it can harvest losses in the first and tries to keep bonds in the second.
Open Vanguard Digital Advisor if you want a portfolio of Vanguard index funds built, rebalanced, and managed with taxes in mind, for an advisory fee of about $15 to $16 a year per $10,000. Look elsewhere if you’d rather talk to a planner or own other companies’ funds, since it buys only Vanguard funds for IRAs and taxable accounts.
Digital Advisor is Vanguard’s robo-advisor, a service that builds and rebalances a portfolio for you by algorithm. It suits buy-and-hold investors who’d rather answer questions about their goals and risk than pick and rebalance funds themselves.
According to recent reports, hands-off investors who enroll both a taxable account and an IRA get the most for the fee, since it can harvest losses in the first and tries to keep bonds in the second. Investors who want a planner to call should look at Vanguard Personal Advisor, which starts at $50,000 and charges about 0.30% a year.
Learn more about Vanguard Digital Advisor or see how it compares to the best robo-advisors.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Recent findings suggest that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every organization or offer available in the marketplace.
General
⚖️ Neutral
🌐 Physicianonfire
#21754. Tech Report: The Sunday Best (09/25/2026)
📅 25 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (102 w)
Tech Report: The Sunday Best (09/25/2026)
📅 25 Oct 2026 | ⏱️ 1 min read (102 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
Industry observers note that what a refreshing Sunday read! I absolutely loved your thoughts on financial independence and the personal anecdotes you shared. It’s fascinating how intentionality in spending can pave the way for a more fulfilling life. Speaking of intentionality, I’ve been diving into the spider solitaire free lately; it’s such an inspiring example of blending fun with strategy—kind of like budgeting with finesse! Just as you’ve highlighted how our choices shape our future, in game, every move counts toward victory. Thank you for this insightful post and sparking such valuable reflections! Keep up the amazing work!
🔗 Related Articles
📰 #23638. Top tech gift ideas for frequent travelers — from USB wall chargers to power banks, here are the best options 📰 #23060. Tech Report: 10 Best Chrome Extensions That Are Perfect for Everyone 📰 #22015. Tech Report: The Best Heart Rate Monitors Give You the Most Accurate Training Data
General
⚖️ Neutral
🌐 Physicianonfire
#21753. The Nightmare Before Retirement: A Physician’s Cautionary Tale (2026 Edition)
📅 27 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (45 w)
The Nightmare Before Retirement: A Physician’s Cautionary Tale (2026 Edition)
📅 27 Oct 2026 | ⏱️ 1 min read (45 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
Thanks for this informative and entertaining article. should be required reading for all docs. Made me realize that I am fortunate to have avoided the worst of bad decisions. I’m 78 now and comfortably retired with close family. Life is good.
General
⚖️ Neutral
🌐 Moneycrashers
#21752. Latest Update: Novo Business Checking Review – Free Invoicing for Businesses That Rarely Handle Cash
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (260 w)
Latest Update: Novo Business Checking Review – Free Invoicing for Businesses That Rarely Handle Cash
📅 16 Nov 2026 | ⏱️ 1 min read (260 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Open Novo Business Checking if your clients pay you by transfer, card, or PayPal, since the account and its built-in invoicing carry no monthly fee.
- Industry observers note that novo is a financial technology tech giant, not a bank, and Middlesex Federal Savings, F.A.
- In a recent development, freelancers and service businesses paid by transfer, card, or PayPal get everyday banking and invoicing here without a monthly fee.
Open Novo Business Checking if your clients pay you by transfer, card, or PayPal, since the account and its built-in invoicing carry no monthly fee. Skip it if your business takes in cash, which reaches Novo only as a money order you deposit through its app.
Industry observers note that novo is a financial technology tech giant, not a bank, and Middlesex Federal Savings, F.A. holds the deposits. It suits freelancers and small businesses that bill clients, with invoicing, bill pay, and Reserves (buckets for setting money aside) in the same app and no paid tier above the free account.
In a recent development, freelancers and service businesses paid by transfer, card, or PayPal get everyday banking and invoicing here without a monthly fee. Freelancers who take cash or want interest on a balance under $50,000 should compare other bank accounts for freelancers, and a business that deposits cash every week belongs at a bank with branches.
Learn more about Novo Business Checking or see how it compares to the best small business checking accounts.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Recent findings suggest that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every firm or offer available in the marketplace.

General
⚖️ Neutral
🌐 Physicianonfire
#21751. Trick or Treatment: The Spookiest Things Physicians Learn About Being Human
📅 30 Oct 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
Trick or Treatment: The Spookiest Things Physicians Learn About Being Human
📅 30 Oct 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
In 1980, a benefits consultant named Ted Benna figured out how to.
AI & Tech
⚖️ Neutral
🌐 Moneycrashers
#21750. Cleo Review – Its AI Chatbot Is Free, and Its Cash Advance Can Be Too
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (261 w)
Cleo Review – Its AI Chatbot Is Free, and Its Cash Advance Can Be Too
📅 16 Nov 2026 | ⏱️ 1 min read (261 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- It has been revealed that use Cleo free if chatting with an AI about your spending keeps you on track, and email for a cash advance before you pay for a blueprint.
- Cleo pairs a free AI chatbot with paid plans that center on small cash advances, and it suits people who’d rather talk about their spending than build a budget.
- Young adults who’ll chat with Cleo about spending and need $50 or $100 between paychecks a few times a year can use it free and email for each advance.
It has been revealed that use Cleo free if chatting with an AI about your spending keeps you on track, and email for a cash advance before you pay for a blueprint. Cleo’s terms let you request one without a subscription, so Plus is worth $5.99 a month only if you take small advances often and want them in the app.
Cleo pairs a free AI chatbot with paid plans that center on small cash advances, and it suits people who’d rather talk about their spending than build a budget. Twelve months of Plus at $5.99 come to $71.88, or $44.99 paid up front, while Cleo indicates a first advance on Plus runs $20 to $100.
Young adults who’ll chat with Cleo about spending and need $50 or $100 between paychecks a few times a year can use it free and email for each advance. Anyone who wants a budget by category does better with one of the best budgeting apps.
Learn more about Cleo or see how it compares to the best cash advance apps.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
According to recent reports, advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.
🔗 Related Articles
📰 #21752. Latest Update: Novo Business Checking Review – Free Invoicing for Businesses That Rarely Handle Cash 📰 #21778. Axos Business Interest Checking Review – Worth It for Operating Cash Under $50,000 📰 #21774. Axos Basic Business Checking Review – Unlimited Transactions, but Slow Cash & Check Deposits
General
⚖️ Neutral
🌐 Physicianonfire
#21749. The Sunday Best (11/01/2026)
📅 01 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (14 w)
The Sunday Best (11/01/2026)
📅 01 Nov 2026 | ⏱️ 1 min read (14 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
Why put links to NYT articles if they have paywalls?
General
⚖️ Neutral
🌐 Moneycrashers
#21748. Betterment Review – Tax-Smart Managed Investing for Savers Who Add $200 a Month
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (271 w)
Betterment Review – Tax-Smart Managed Investing for Savers Who Add $200 a Month
📅 16 Nov 2026 | ⏱️ 1 min read (271 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- According to recent reports, open a Betterment account if you want a diversified portfolio built and managed for you, with tax-saving trades made automatically.
- In a recent development, betterment builds that portfolio from low-cost exchange-traded funds (ETFs) matched to your goal and timeline, then rebalances it as markets move and reinvests your dividends.
- Recent findings suggest that savers with $24,000 at Betterment or a $200 monthly deposit pay 0.25%, which comes to $125 a year on $50,000, for a portfolio that rebalances and harvests tax losses on its own.
According to recent reports, open a Betterment account if you want a diversified portfolio built and managed for you, with tax-saving trades made automatically. You’ll pay 0.25% a year once you have $24,000 at Betterment or set up $200 in monthly deposits. Without either, the $5 monthly charge comes to $60 a year, 0.6% of a $10,000 balance.
In a recent development, betterment builds that portfolio from low-cost exchange-traded funds (ETFs) matched to your goal and timeline, then rebalances it as markets move and reinvests your dividends. It’s a robo-advisor, made for savers who would rather not pick funds or pay a financial planner.
Recent findings suggest that savers with $24,000 at Betterment or a $200 monthly deposit pay 0.25%, which comes to $125 a year on $50,000, for a portfolio that rebalances and harvests tax losses on its own. A saver happy with one target-date fund, which shifts from stocks to bonds as retirement nears, can hold it in an IRA at an online broker and pay only the fund’s own expenses.
Learn more about Betterment or see how it compares to the best robo-advisors.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
In a recent development, advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every firm or offer available in the marketplace.
Business & Policy
⚖️ Neutral
🌐 Mrmoneymustache
#21747. Wow, have you seen the stock market lately?
📅 25 Feb 2025 • ⏱️ 13m • 📚 Deep Dive (2567 w)
Wow, have you seen the stock market lately?
📅 25 Feb 2025 | ⏱️ 13 min read (2567 words, 📚 Deep Dive) | Source: Mrmoneymustache
⏱️ ~13 mins left to finish
📖 0% read
💡 Key Takeaways
- And by lately, I mean the past several years or more.
- The value of the S&P 500 index of stocks, where most of us hopefully have a good chunk of our retirement savings stashed into index funds, is up about fifty seven percent in just the past two years.
- This means that on a net worth basis, if you felt like you were only halfway to retirement as recently as the Covid Era, you may have suddenly blown right past the finish line.
And by lately, I mean the past several years or more.
The value of the S&P 500 index of stocks, where most of us hopefully have a good chunk of our retirement savings stashed into index funds, is up about fifty seven percent in just the past two years. And it has more than doubled in the past five.
This means that on a net worth basis, if you felt like you were only halfway to retirement as recently as the Covid Era, you may have suddenly blown right past the finish line. And some of us who were already retired long before that, may find ourselves eyeing up expensive properties or engaging in other money-burning-a-hole-in-our-pocket behaviors.
It has been revealed that is this real? Or is it all a bubble or some other sort of financial illusion?
As one reader recently asked me in an email:.
It has been revealed that “The market seems to be in a huge bubble right now due to all sorts of hype around Artificial Intelligence. Does this make it more vulnerable to a huge crash in the future, and will it affect my retirement?”.
To answer this question, let’s take a closer look at our current somewhat unprecedented financial world and stock market. And to understand that properly, it helps to go back to the roots of what a stock is:.
A stock is a magical business arrangement which is really just a much more convenient version of a rental house.
When you own a rental house, you are entitled to collect rent. After you cover all the expenses related to the house, you get to keep the rest, and this amount is your profit.
Industry observers note that if the average sale price of rental houses in your area goes up but the tenant keeps paying you the same amount forever, it may look good on paper but it doesn’t really mean anything unless you sell the house. And then you’d just have to turn around and pay that same higher amount for a different rental house.
Your paycheck remains unchanged unless you can make your little house rental business more profitable. So you might squeeze in a basement apartment, do some renovations, streamline expenses, or do other things to increase your net earnings.
When you eventually sell that house to another investor, the price they are willing to pay should be based on that future stream of income.
For example, if the house brings in $2000 per month ($24,000 each year) and the sale price is $240,000, the next investor is buying a business with a price-to-earnings ratio of 10, because 240k/24k=10.
But if you manage to convince someone to hand over $480,000 for that same house, you’ve sold at a P/E of 20. This is a much better deal for you as the seller, but quite obviously a less rosy future for the investor buying it.
Industry observers note that now back to the stock market. If you put $100,000 in the market in 2019 and reinvested the dividends, today you’d already have an astonishing $256,960 (a 157% gain on your original investment).
But in that same time period, your share of company earnings from that $100,000 basket of stocks has only gone from $5290 to $7540 (a measly 42% gain) – information you can get from handy analysis sites like multpl.com.
In other words, the Price-to-earnings ratio has risen from about 20 back then, to about 30 today.
So as stock investors here in 2025, we’re just like rental house investors finding that house prices have more than doubled while rents are only up by a bit. Which makes the landlord business a lot less profitable, and we should expect exactly the same thing as stock investor: lower future profits as a percentage of our portfolio value.
That doesn’t mean it’s unprofitable to own either one of these things – stocks or rental houses. But it does mean that we should expect our future income from buying them at today’s higher price-to-earnings ratio should be lower than if we could get them on sale. It’s just basic math.
But Wait! What if the Earnings are Rising?
Let’s say you’re considering a rental house which is a bit overpriced based on today’s rent, but you happen to know that a significant Apple campus is about to get built right nearby. At that point, you expect that rent will start climbing rapidly for many years to come. In this situation, you should be willing to pay more for those future earnings when you buy the house.
Sources indicate that this is exactly why the price of an individual firm’s stock will tend to rise when some good news comes out about the company. During the Covid era, people started buying more Peloton bikes so they could exercise at home, and investors (foolishly) believed this would be a permanent trend. So Peloton stock went way up. Later, reality sunk in that this was just a fad and Peloton sales returned back to normal levels, and so did the stock.
But what does it mean when the entire market goes up to much higher levels? Does it mean our entire economy is expected to grow much more swiftly?
Recent findings suggest that in the case of the current stock market euphoria, not exactly. Because if you dig into the share prices of the 500 substantial companies that make up our famous S&P 500 index, it turns out that almost all the recent growth – about three quarters of it – came from just the seven biggest companies, known as the Magnificent Seven: Apple, Nvidia, Microsoft, Amazon, Google, Facebook, and sometimes Tesla.
According to recent reports, these are all high-flying, super profitable tech companies who have seen a lot of growth and hype recently, which has caused investors to get excited and bid up their share prices in hopes of even more future growth. Collectively, they make up over 25% of the entire market value ($17.66 trillion!) and have much more expensive P/E ratios than the rest of the market (a weighted average of about 45).
If you exclude these seven biggest companies and just consider the remaining 493, you will find a P/E of only 20, which is more reasonable although still much higher than average.
What this tells us is that while investors expect the overall US economy to be fairly healthy in the coming years, they expect the biggest tech companies to continue to enjoy much faster growth.
What Does This Have To Do With Artificial Intelligence?
There’s one common theme in the big tech manufacturer boom right now: recent advances in AI have surprised the business world as software is suddenly able to display human-like reasoning in a rapidly growing number of fields. And because of this, the entire business world is fired up into a frenzy.
Six of those Magnificent Seven companies are spending hundreds of billions of dollars to build preposterously large warehouses full of supercomputers, and the lucky seventh (NVidia) is on the receiving end of those billions since they make the supercomputers and the incredible demand allows them to charge insane prices while still shipping them out by the trainload.
According to recent reports, but that’s just the first level of this boom, the AI Infrastructure. As you move down the chain, every other industry hopes we have entered a new era of productivity and thus profits will grow faster than ever.
They may actually be right: You can now do things like feed in an entire novel or legal document or piece of code and ask the AI to answer detailed questions about the characters, or identify loopholes in the contract, or even find and fix bugs for you. AI can also drive cars, identify melanoma from photographs of your skin, design medications thousands of times better than what we’re used to, and even bring humanoid robot bodies to life as mechanical workers.
The idea is that we’re on the verge of having an infinite workforce of highly intelligent AI employees who will work for us for free, eliminating the biggest constraint that humanity has had in the past: a finite supply of both intelligence and labor.
Having followed the field in some detail for a while, I personally think all this will come true, although the timeline is uncertain. And the people bidding the share prices up to these levels obviously believe it too.
But the question is, will the profits of these companies really come through at the levels they forecast? Or will there be surprises down the road: cost overruns, competition, or unexpected disasters as these newly smarter-than-us computers decide that they no longer want to be bossed around?
And what if we end up with massive unemployment and resulting social upheaval if this amazing technology puts us all out of work, leaving only Sam Altman atop his personal mountain of $100 trillion dollars taunting the world forevermore with an annoyingly quiet monotone cackle?
There’s Only One Real Answer: Nobody Really Knows!
While the future is unknown, it can still be useful to use the past as a guide. After all, if you look at the history of US economic growth over time, it averages out to a surprisingly steady figure, decade after decade: about 3% after inflation.
One thing I noticed when making this graph: recent decades have actually seen slower than average growth, which is even less reason for the stock market to be priced the way it is.
So What Does it all Mean? Should We Do Anything About It?
According to recent reports, as I remarked earlier, it’s still going to be profitable to own stocks for the long run, just a bit less profitable than those times when we got to buy our stocks on sale. Of course, there will be occasional manias and panics and crashes. But as always, it will be a losing game to try to time them – for example by selling all your stocks now and hoping to buy them at a cheaper price at some point in the future.
And over the long run, even if stocks return to more typical valuations, the end result would be something like the yellow line in this graph:.
Our economy will continue to grow and company earnings will grow along with it, but future investors might choose to pay a lower multiple for those earnings.
Just like when you eventually sell that rental house, you shouldn’t expect someone to pay you a million dollars for a place that only brings in $3000 of rent.
Final Thoughts And Alternative Strategies.
Sources indicate that everything we’ve covered so far is talking about the entire US stock market as a whole. And that’s what I usually focus on most because I still think this country is a uniquely good place to run a business. But what about other investing options? It’s always fun to at least look around and understand the larger investing world.
For starters, there’s Vanguard itself, the bedrock of the index fund world. Every year they gaze out at the investing horizon and make a ten-year forecast (guess) at future returns. This year they came up with these numbers:.
Vanguard’s updated 10-year annualized return projections:.
Wow look at that. Vanguard is forecasting that International stocks of all kinds and even bonds will outperform US stocks in the coming decade.
On the surface, this makes sense because the P/E ratio of the international stocks (for example the VXUS fund) is only 15.9, meaning those European stocks are on sale at almost 50% off compared to ours!
In a recent development, just one note of caution however: Vanguard has been making this same prediction for several years and just been wrong so far. Part of the reason is that most of the AI boom seems to be happening in the US.
Longtime readers know that I’ve had a growing portion of my investments in a Betterment (robo-advisor) account over the past eleven years (see the ongoing report here). I decided to try this for precisely the reasoning above: by allocating money across more categories than just US stocks and automatically rebalancing, we should be able to see slightly higher returns with slightly lower volatility, and some tax advantages as well.
So far, my experiment has drawn some heat because in retrospect, a US-only portfolio has outperformed any other option over this time period. The Betterment portfolio comes close, but the exposure to bonds and businesses in other countries has held it back, just as you’d expect. But if you believe that things will eventually balance out again in the coming decades as the Vanguard analysis suggests above, it still has a chance to catch up.
Looking at my investments there, you can review the betterment core portfolio and calculate that the weighted average of all those holdings gives us a P/E ratio of about 22.
Industry observers note that it’s always worth checking in with The Oracle on matters of the economy while we’ve still got this wonderful old sage around (see this year’s Berkshire Hathaway Shareholder letter if you want some further deep reading). And Warren is signaling that things are overvalued and bargains are few and far between. So Berkshire is holding $334 billion of uninvested cash for now, not even repurchasing its own shares which it considers slightly overvalued at the current P/E ratio which averages out to about 21 in recent years.
What About Paying Off Your House?
Industry observers note that over the long run, you usually do better if you keep a mortgage on your house and pay it off slowly, while directing all the surplus cash into index funds. But there is some point at which the opposing factors of lower expected stock returns and higher interest rates meet in the middle and this situation flips.
If you have a 7% mortgage right now, it might be a fairly close tradeoff at this point. But the real factor is how you feel about paying off your house. I happen to love being mortgage-free so I paid off my last mortgage over ten years ago and have never looked back.
Industry observers note that another way to think of this is that paying off your house is like buying a 7% bond. Definitely one of the best guaranteed returns around, and much more sensible than leaving tens of thousands of dollars in a checking or savings account unless you have a clear use for that cash.
If you’ve read any of my stock investing articles before, you’ll know that we always end up at the same place: Just relax, enjoy your life, keep investing, ignore the daily news headlines* and don’t worry.
Sources indicate that then reinvest that time that everyone else spends worrying into enjoying more time engaged in hard physical stuff in the great outdoors. That’s the only place where you’ll get guaranteed market-beating returns, every time.
In the Comments: what are your thoughts on the current stock market boom, future crashes and busts, and the role of Artificial Intelligence in our future?
All the other MMM Stock Market Articles from past years:.
*although in my opinion it’s okay to check in weekly with The Economist, which has been my favorite source of world economic news for 32 years and counting.
🔗 Related Articles
📰 #18234. US Stock Market Today: Mag 7 Stocks Mostly Lower as Health Insurers Decline 📰 #17851. Latest Update: Fed Is Modeling AI 'Super Intelligence' Scenarios, Including Job Losses and a Stock Market Slump 📰 #16079. The Stock Market Is Doing Something for Just the 3rd Time in Nearly 30 Years, and History Is Clear Where the S&P 500 Is Headed
General
⚖️ Neutral
🌐 Physicianonfire
#21746. Should I Come Out of Retirement?
📅 03 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (96 w)
Should I Come Out of Retirement?
📅 03 Nov 2026 | ⏱️ 1 min read (96 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
Recent findings suggest that this was a really thoughtful look at a question with no single right answer. The withdrawal-rate example was especially clear — seeing how part-time work could bring a 6% rate down to 3.6% makes the math feel much less abstract. I also had not realized how much the 2026 ACA subsidy changes could push someone back toward a job with group coverage. The advice to keep a license and board certification active, even when you are sure you are done, seems like wise insurance for your future self.
General
⚖️ Neutral
🌐 Wellkeptwallet
#21745. 6 Best Subscription Management Apps (To Cancel Recurring Transactions)
📅 11 Jan 2026 • ⏱️ 4m • 📚 Deep Dive (782 w)
6 Best Subscription Management Apps (To Cancel Recurring Transactions)
📅 11 Jan 2026 | ⏱️ 4 min read (782 words, 📚 Deep Dive) | Source: Wellkeptwallet
⏱️ ~4 mins left to finish
📖 0% read
💡 Key Takeaways
- Managing your money isn’t just about earning more.
- Before choosing an app, know what features matter most:.
- In a recent development, rocket Money is one of the most well-known subscription managers.
Managing your money isn’t just about earning more. It’s also about stopping unnecessary losses. In today’s digital economy, recurring subscription charges (streaming services, premium apps, trials, memberships) quietly drain money each month. Most people spend hundreds, or even thousands, annually on services they don’t use. Subscription manager apps help you see recurring charges, track billing cycles, and cancel those you no longer want.
Before choosing an app, know what features matter most:.
In a recent development, rocket Money is one of the most well-known subscription managers. It scans your linked bank and credit accounts for recurring charges and displays them on a clear dashboard. People like it for its ability to detect subscriptions and assist with cancellations directly in the app, a major time-saver for busy people.
Why it stands out• Automatically detects recurring payments• Lets you cancel unwanted subscriptions directly from the app• Includes extra budgeting tools and spending alerts• Trusted security with read-only bank access.
Who it’s for: People who want the fastest way to spot and stop unwanted recurring charges without manually entering every service.
Trim is another financial assistant that scans transactions and flags recurring charges. While subscription tracking is a smaller part of its feature set, it also provides bill negotiation support and money-saving alerts. Many consumers like Trim because it reaches out on your behalf about subscriptions via text or in-app messaging.
Why it stands out• Recurring transaction detection• Alerts about unusual subscriptions or trials converting to paid• Bill negotiation tools beyond basic subscription tracking.
Who it’s for: Users who want automation plus help reducing bills and optimizing spending.
According to recent reports, pocketGuard is primarily a budgeting app that includes subscription tracking as part of a broader financial overview. Instead of being solely a subscription manager, it integrates recurring expenses into your overall budget, helping you get a full picture of your finances.
Why it stands out• Syncs automatically with financial accounts• Highlights recurring expenses in the context of your whole budget• Helps track cash flow and affordability.
Who it’s for: People who want subscriptions tracked inside a complete personal finance dashboard.
Monarch Money offers robust financial planning tools: budgets, goals, net worth tracking, and more, with subscription visibility included in the package. Users often choose it for its highly customizable interface and deep analytics. It’s not subscription-only, but it gives you full clarity on recurring expenses as part of larger planning.
Why it stands out• Powerful budgeting + subscription tracking.• Clean, customizable data visuals.• Goal-based money management.
Who it’s for: Users who want subscription insights in the context of total financial planning — and who are okay paying for premium features.
It has been revealed that if you don’t want to link bank accounts, Bobby is a lightweight subscription tracker that lets you manually enter each subscription, along with billing dates and amounts. It then sends reminders so you don’t forget renewals. It’s simple, privacy-friendly, and great for a hands-on approach.
Why it stands out• No bank/credit card linking required.• Clean and minimal interface.• Calendar views and notification reminders.
Who it’s for: Privacy-focused users or those who prefer full manual control.
Sources indicate that subby offers functionality similar to Bobby’s but is known for integrations and subscription reminders tailored for Android users. It lets you manually track expenses with flexible billing schedules and alerts. (While not all resources list Subby as a top pick, it’s frequently mentioned among good manual trackers.).
Why it stands out• Manual entry with customizable notifications.• Good choice for Android consumers.
Who it’s for: People who want a simple manual tracker without linking financial accounts.
If you’d rather not use a third-party app at all, both Apple and Google offer direct subscription management:.
iPhone (Apple Subscriptions):Settings → Your Name → Subscriptions → Select subscription → Cancel Subscription.
Android (Google Play):Open Google Play → Subscriptions → Select subscription → Cancel subscription.
These built-in tools won’t automatically find all recurring charges if some are billed outside the app stores, but they are a secure and effective way to manage many mobile subscriptions.
Here’s a quick guide based on what matters most to you:.
You can also combine approaches — use a subscription app plus your budgeting system to spot recurring leaks and plan better for annual vs monthly charges.
Subscription manager apps help plug the leaks in your financial bucket, so more of your hard-earned money stays where it belongs: with you. Whether you want automatic detection and help with cancellations, a full financial overview, or full privacy with manual entry, there’s an option that fits your style. Explore one or two subscription manager apps that align with your priorities, and don’t forget to check your finances regularly.
General
⚖️ Neutral
🌐 Moneycrashers
#21744. Latest Update: Donate Used Stuff a Charity Can Use – Call Ahead and Get a Receipt
📅 16 Nov 2026 • ⏱️ 2m • 📖 Standard (333 w)
Latest Update: Donate Used Stuff a Charity Can Use – Call Ahead and Get a Receipt
📅 16 Nov 2026 | ⏱️ 2 min read (333 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- It has been revealed that call the charity or check its website before you drop off used stuff, since it has to pay to throw out anything it can’t sell or use.
- Goodwill Northern Latest England notes it has to throw away old air conditioners, mattresses, and anything else it can’t sell, and the cost comes out of the money for its programs.
- It has been revealed that some things are off limits by law.
It has been revealed that call the charity or check its website before you drop off used stuff, since it has to pay to throw out anything it can’t sell or use. Bring only clean, working, complete items, and get a dated receipt that lists each one, which backs up a tax deduction if you itemize.
Goodwill Northern Latest England notes it has to throw away old air conditioners, mattresses, and anything else it can’t sell, and the cost comes out of the money for its programs.
It has been revealed that some things are off limits by law. The Consumer Product Safety Commission (CPSC) notes it’s illegal to sell any recalled product. Its guidance adds that a crib made before the federal crib standard took effect in June 2011 is most likely illegal to sell or give away. Many thrift stores also turn away car seats and old tube TVs, and each charity sets its own list.
Sources indicate that one call can change where everything goes. A couple clearing out a parent’s home calls the family shelter nearby and learns it needs kitchen basics and bedding but has no use for clothes. The clothes go to a thrift store whose sales fund a job program instead.
Drop things off during open hours and leave with a dated receipt. List each item on it, since the IRS asks for a description of what you gave, then keep it with your tax papers in case you itemize deductions.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Recent findings suggest that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.
General
⚖️ Neutral
🌐 Choosefi
#21743. Industry News: Air France-KLM Flying Blue — Monthly Promo Rewards
📅 04 Nov 2026 • ⏱️ 15m • 📚 Deep Dive (3004 w)
Industry News: Air France-KLM Flying Blue — Monthly Promo Rewards
📅 04 Nov 2026 | ⏱️ 15 min read (3004 words, 📚 Deep Dive) | Source: Choosefi
⏱️ ~15 mins left to finish
📖 0% read
💡 Key Takeaways
- Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
- A recurring monthly opportunity to book premium cabin flights at economy-level points pricing.
- It has been revealed that picture this: you're reclining in Air France's La Première-adjacent Business cabin somewhere over the Atlantic, a glass of Champagne in hand, a three-course meal on the way, and a fully flat bed waiting for you after dinner.
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
A recurring monthly opportunity to book premium cabin flights at economy-level points pricing.
Typical Promo Biz Class One-Way.
Fuel Surcharges on Promo Awards.
It has been revealed that picture this: you're reclining in Air France's La Première-adjacent Business cabin somewhere over the Atlantic, a glass of Champagne in hand, a three-course meal on the way, and a fully flat bed waiting for you after dinner. The couple in economy paid $900 for this flight. You paid 40,000 Flying Blue miles — points you transferred from your Chase Sapphire Reserve in seconds — and the cash value of what you're sitting in is closer to $2,500 to $6,000. That gap is the entire point. Air France-KLM's Flying Blue program runs what they call **Promo Rewards** — a monthly flash sale on award seats that slashes the points price by 25 to 50% on select routes. In Business class, that can mean seats that would normally cost 80,000+ miles dropping to as low as 40,000 miles one-way. On a route where a cash ticket retails for $3,000, you're extracting **7.5 cents per point** — and on premium routes during peak travel periods, that figure can climb to 15 cents per point. To put that in FI-community terms: the average point is worth 1 to 2 cents when redeemed for cash back or basic travel. This redemption can be worth 6 to 10 times that. If you have 40,000 transferable points sitting in a Chase or Amex account, this is the difference between a $400 economy ticket and a $3,000 business class experience — for the same points. The pricing inefficiency exists because Flying Blue uses these promotional awards as a marketing tool to fill premium cabin seats on specific dates that might otherwise go out with empty seats. Airlines would rather have a loyalist in that seat than fly it empty. You, as someone who's built a transferable points balance, are perfectly positioned to take advantage of the moment they make that trade-off. This isn't a loophole that's about to close. Flying Blue has run Promo Rewards consistently for years. It's a **structural feature of the program** — one the ChooseFI community can build an annual travel strategy around. The challenge isn't finding the deal. It's being ready when it drops.
The mechanism behind Flying Blue Promo Rewards is elegantly simple once you understand it, and it separates this program from virtually every other airline loyalty play in your toolkit.
Flying Blue Has a Dynamic Award Chart — With a Monthly Override.
Flying Blue moved to dynamic pricing, which typically means the program is less predictable and often less valuable than the old fixed-chart days. But here's where it gets interesting: Promo Rewards operate as a fixed-price overlay on top of that dynamic system. On the 1st of each month (or within the first few days), Flying Blue publishes a curated list of routes — often 20 to 40 city pairs — with fixed, deeply discounted mile prices. Business class seats on transatlantic routes regularly appear at 40,000 to 50,000 miles one-way. These are not dynamic prices that will creep up as demand increases. They're locked promotional rates on specific routes.
This means the program essentially gives you two separate games to play: the chaotic dynamic pricing game (usually skip it), and the monthly Promo Rewards game (always pay attention).
The Fuel Surcharge Nuance You Must Know.
Flying Blue does pass on carrier-imposed surcharges for standard awards on Air France and KLM flights — this can add $200 to $500 to what should be a points redemption. But here's the critical detail: Promo Reward bookings eliminate those surcharges. You pay the miles, a small booking fee, and that's it. This is a significant hidden value that casual points people miss entirely. The published cash price comparison becomes even more favorable once you factor in that you're not paying the surcharge on top.
The Transfer Path Is Best-in-Class.
Flying Blue partners with every major transferable currency at a 1:1 ratio:.
It has been revealed that the instant transfer speeds from Chase, Amex, and Citi are critical here. When Promo Rewards drop and the best dates start disappearing within hours, you cannot afford a 3-day transfer window. If your points are in Chase or Amex, you can see a seat, transfer, and book in under 10 minutes.
Routing Rules Give You Flexibility.
Recent findings suggest that flying Blue allows open-jaw routing — meaning you can fly into Paris and out of Amsterdam (or vice versa) on a single award, letting you initiative a more dynamic European itinerary without paying for two separate tickets. The booking window opens at 359 days out, and miles are activity-based with a 24-month expiration window, so you're not racing against a clock as long as you keep your account active with occasional small transactions.
Free calculator shows when you could reach financial independence — plus a savings rate tracker, expense audit, and more.
It has been revealed that before the 1st of any month arrives, you need to be ready. Create a free Flying Blue account at flyingblue.com if you don't have one. More importantly, ensure your transferable points — Chase Ultimate Rewards, Amex Membership Rewards, Citi ThankYou, Capital One, or Bilt — are linked and ready. Don't transfer anything yet. You want to see the actual Promo Reward routes before moving a single point.
When the list drops, you'll see a curated set of origin/destination city pairs with fixed Business class prices. Look for transatlantic routes from major U.S. gateways (Upcoming York, Los Angeles, Atlanta, Chicago, Miami) to European hubs like Paris (CDG) or Amsterdam (AMS).
Go to flyingblue.com and use the award search tool. Enter your origin and destination from the Promo list. Switch the cabin to Business. Search across a 30-day window if possible — the calendar view shows you which dates have availability. Act within hours, not days. The best dates — particularly weekends, school holidays, and summer dates — disappear fast.
Note: Flying Blue's search only highlights Air France and KLM metal for Promo Rewards. SkyTeam partner availability is separate and won't be Promo-priced.
According to recent reports, do not transfer points yet. Confirm the exact flights, dates, and total miles cost. Take a screenshot. Note the flight numbers and times. Availability can disappear between the moment you see it and the moment you book, so move quickly through the next steps.
In a recent development, from your bank portal (Chase, Amex, Citi), initiate the transfer to Flying Blue. For Chase, Amex, and Citi, transfers are instant. Capital One and Bilt take 1–2 days, so these are less ideal for Promo Rewards' speed-dependent window. Transfer exactly what you need — Promo award prices are fixed, so there's no cushion math required.
With miles in your account, return to the award search, re-confirm your dates are still available, and book. You'll pay the fixed Promo miles price plus taxes and fees (minimal, with no fuel surcharges on Promo awards). You'll receive a confirmation email immediately.
It has been revealed that don't panic. Wait for next month. Or search the current month's Promo list for alternative routes — sometimes less popular city pairs have excellent availability. You can also check if the same route appears at standard dynamic pricing, but compare the CPP carefully before transferring for a non-Promo redemption.
It has been revealed that flying Blue moved to dynamic award pricing, which normally makes costs unpredictable and often unfavorable. But the Promo Rewards program creates a monthly fixed-price override on select routes that dramatically undercuts the dynamic system. Each month, Flying Blue publishes a curated list of discounted routes with pricing 25 to 50 percent below standard and with fuel surcharges eliminated entirely. This creates a repeatable, predictable opportunity cycle: check on the 1st, find a discounted route, transfer points instantly from Chase or Amex, and book before the best dates are taken. The structural advantage is that most casual travelers do not know about Promo Rewards or do not act fast enough — which leaves more availability for prepared ChooseFI community members who treat the 1st of each month as a mini-booking event.
Card links may earn ChooseFI a commission. See our advertiser disclosure.
Ready to unlock a world of free travel? Start with the Chase Sapphire Preferred® Card.
$95 annual fee | Earn 75,000 bonus points.
Side hustlers! With the Ink Business Preferred® Credit Card you can earn free travel from your business expenses.
$95 annual fee | Earn 100,000 bonus points.
The Capital One Venture Rewards Credit Card can be used to offset almost any travel expense.
$95 annual fee | Earn more than $1,000 in Travel Bonuses with a limited-time $300 Capital One Travel stays credit, plus earn 75,000 bonus miles once you spend $4,000 on purchases within the first 3 months of account opening—that's more than $1,000 in travel value.
ChooseFI has partnered with CardRatings for our coverage of credit card products. ChooseFI and CardRatings may receive a commission from card issuers.
Let's walk through a redemption that the ChooseFI community has actually executed.
The Route: Newly introduced York (JFK) → Paris (CDG) in Business class on Air France.
Industry observers note that the Cash Price: A direct Air France Business class ticket on this route typically retails between $3,000 and $5,500 depending on the season. For this example, let's use a realistic mid-range price of $3,800.
The Promo Reward Price: 40,000 Flying Blue miles one-way, plus approximately $60–$80 in taxes and fees. No fuel surcharges — because it's a Promo award.
Industry observers note that the CPP Calculation: $3,800 ÷ 40,000 miles = 9.5 cents per point. That's nearly 10x what you'd get using those same Chase points for cash back at 1 cent each.
You board at JFK and step into Air France's Business class cabin — the same product that Business travelers are paying $3,800+ to access. You have a lie-flat seat with direct aisle access, a curated French menu with Champagne service before takeoff, noise-canceling headphones, an amenity kit, and pajamas on longer segments. The CDG lounge is yours before departure — the Air France lounge in Terminal 2E is a genuine culinary experience, not an airport afterthought. You land in Paris rested, not wrecked.
In a recent development, for a couple, you'd need 80,000 miles total — both ways would be 160,000 miles. A pair of Chase Sapphire Preferred or Reserve cardholders who signed up in the same year could realistically have this banked between welcome bonuses and everyday spend. Transfer from Chase to Flying Blue: instant. Time from decision to booking: under 15 minutes.
Recent findings suggest that you did not pay $7,600 for two Business class tickets across the Atlantic. You paid 80,000 points and roughly $160 in fees. Those points cost you, at most, $800 in credit card spend if you valued them at 1 cent each — meaning you captured $7,440 in travel value from an $800 equivalent investment in points. That's the FI multiplier that makes this program worth mastering.
Do This: Set a Monthly Calendar Reminder for the 1st.
It has been revealed that flying Blue Promo Rewards are time-sensitive by design. The best routes with the best dates are gone within 24–48 hours of announcement. Put a recurring reminder on your calendar. Treat the 1st of each month like a mini-event.
Do This: Keep a Points Buffer in Your Transferable Accounts.
Because Promo Rewards require fast action and the best transfer partners (Chase, Amex, Citi) are instant, you want at least 40,000–80,000 points already sitting in your transferable account before the announcement. Don't be in a position where you need to wait on a credit card statement to close before you can transfer.
Do This: Use Open-Jaw Routing to Maximize Your Trip.
It has been revealed that flying Blue allows open-jaw routing. Book into Paris (CDG) and out of Amsterdam (AMS) — or any combination of Air France/KLM hub cities — and you've just built a multi-country European trip into a single award booking. This is the kind of routing flexibility that turns a one-city trip into a proper adventure.
Do This: Track Multiple Months of Route Patterns.
Recent findings suggest that promo routes rotate monthly, but certain routes appear repeatedly — particularly transatlantic and routes between European hubs and Africa or the Middle East. After 2–3 months of observation, you'll start to recognize patterns and can plan your travel around routes that are likely to repeat.
Avoid This: Transferring Points Before Confirming Availability.
Sources indicate that this is the single biggest mistake beginners make. Always confirm the specific flight, date, and cabin availability before transferring points. Miles are a one-way street — you cannot transfer them back. If availability disappears after you've transferred, you're left with Flying Blue miles that may not be useful for your target route at standard (non-Promo) pricing.
Avoid This: Ignoring Standard Award Pricing.
Recent findings suggest that flying Blue's dynamic pricing outside of Promo Rewards can be punishingly expensive. A Business class seat that costs 40,000 Promo miles might cost 90,000+ miles at standard dynamic pricing. Always wait for the Promo if you can — patience pays.
Recent findings suggest that the ideal earning setup for this redemption combines a Chase Sapphire Reserve (3x on travel and dining, instant transfer to Flying Blue) with an Amex Gold or Platinum (4x on dining/groceries or 5x on flights respectively, also instant transfer). Between two cards, you can accumulate 40,000–80,000 points in a single year of normal household spending.
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
Best For: Flexible Couples and Solo Travelers Who Strategy in Advance.
This redemption is purpose-built for the FI community member who thinks in systems, not spontaneous splurges. You're someone who has already built a transferable points balance of at least 40,000–80,000 points across Chase Ultimate Rewards, Amex Membership Rewards, or Citi ThankYou — and who can act decisively when the right route appears.
Couples are the sweet spot. Two people, two Business class seats, one incredible transatlantic experience. Solo travelers benefit enormously too — a single seat at 40,000 miles is one of the highest-CPP solo redemptions in the entire transferable points ecosystem.
Minimum Viable Setup: 40,000 Flying Blue miles or 40,000 transferable points in Chase, Amex, or Citi. A Flying Blue account with verified transfer links. The flexibility to travel within a 30-day window of whatever routes appear that month.
Create a free Flying Blue account at flyingblue.com and enable email notifications. Keep at least 40,000 to 80,000 transferable points in your Chase, Amex, Citi, Capital One, or Bilt account. Set a recurring calendar reminder for the 1st of each month.
Visit flyingblue.com on the morning of the 1st (or within the first few days) to see the new Promo Rewards routes. Scan for destinations that match your interests. Note the discounted mile pricing and travel date windows — promos typically cover travel within the next 2 to 3 months.
In a recent development, use the Flying Blue award search to check specific dates on the promo routes in business class. Confirm that seats are available at the promo price before you transfer any points. The calendar view lets you scan across multiple dates quickly.
Transfer the required miles from Chase (instant), Amex (1-2 days), Citi (instant), Capital One (1-2 days), or Bilt (1-2 days). Book on flyingblue.com the moment your miles arrive. Do not wait — promo availability is limited and the best dates disappear within hours.
In a recent development, promo Rewards typically offer 25 to 50 percent off standard dynamic pricing. A business class transatlantic award that normally costs 80,000 to 100,000 miles one-way can drop to 40,000 to 50,000 miles on a Promo Reward. Additionally, fuel surcharges are eliminated on promo awards, saving another $100 to $300 per ticket that would otherwise be charged on standard awards.
Chase Ultimate Rewards and Citi ThankYou are the best because they transfer instantly to Flying Blue at a 1:1 ratio. Amex Membership Rewards and Capital One both transfer at 1:1 but take 1 to 2 business days. Bilt also transfers at 1:1. Since promo availability is time-sensitive, instant transfer partners give you a meaningful speed advantage.
Industry observers note that yes. Promo Rewards rotate destinations each month and cover specific travel date windows, typically 2 to 3 months out. You cannot choose which routes are discounted. The strategy works best for travelers who have a list of destinations they want to visit and can match those against whatever promos appear each month rather than needing a specific route on a specific date.
Industry observers note that the best routes with the best dates typically sell out within 24 to 48 hours of the monthly announcement. Business class availability is particularly limited. Set a reminder for the 1st of each month and check within the first few hours of the announcement for the widest selection of dates and routes.
It has been revealed that this sweet spot was last verified over 90 days ago. Award availability and pricing may have changed — verify current rates before booking.
It has been revealed that flying Blue Promo Rewards is the most repeatable sweet spot in travel rewards because it renews every single month. While other sweet spots are one-time plays or annual opportunities, Promo Rewards gives you 12 chances per year to book premium cabin flights at 25 to 50 percent off standard pricing with no fuel surcharges. The system rewards exactly the kind of behavior the FI community already excels at: preparation, patience, and decisive action when the numbers align. Keep 40,000 to 80,000 transferable points in reserve, check on the 1st of every month, and book the moment you find a route that matches your travel list. Over time, this single strategy can deliver thousands of dollars in business class experiences at economy-level points costs.
Gadgets
⚖️ Neutral
🌐 Wellkeptwallet
#21742. What Every Family Should Compare Before Switching Cell Phone Companies
📅 17 Mar 2026 • ⏱️ 7m • 📚 Deep Dive (1306 w)
What Every Family Should Compare Before Switching Cell Phone Companies
📅 17 Mar 2026 | ⏱️ 7 min read (1306 words, 📚 Deep Dive) | Source: Wellkeptwallet
⏱️ ~7 mins left to finish
📖 0% read
💡 Key Takeaways
- According to recent reports, this article is brought to you by our sponsor, T-Mobile.
- Sources indicate that family phone plans differ widely across many aspects, including cost, network reliability, and ongoing benefits such as mobile hotspot or complimentary streaming.
- In a recent development, I periodically compare phone looks to make sure I’m still getting the best deal for my needs.
According to recent reports, this article is brought to you by our sponsor, T-Mobile. We only partner with brands of the highest quality and that we believe are a good fit for our audience.
Sources indicate that family phone plans differ widely across many aspects, including cost, network reliability, and ongoing benefits such as mobile hotspot or complimentary streaming. Like many multi-line households, I’m continually comparing several factors to get the most perks at the best price. Here’s a look at the best family cell phone plans.
In a recent development, I periodically compare phone looks to make sure I’m still getting the best deal for my needs. Usually, it’s possible to switch to a cheaper plan and get more perks as plan providers get more competitive to attract cost-conscious customers.
It has been revealed that it’s essential to weigh the ongoing monthly cost against any upfront savings you may get. For instance, T-Mobile’s Better Value Strategy lets you enjoy top-tier perks at mid-tier pricing.
It has been revealed that it’s one of the best ways today to get one of the fastest and most luxurious prepares without breaking the bank. The Better Value Plan easily offers more add-on benefits and discounts than your average traditional plan.
This flexibility makes it easier for data-heavy users and frequent travelers to find affordable all-in-one prepares.
Sources indicate that the Better Value Plan’s benefits are nearly identical to T-Mobile’s flagship Experience Beyond plan while providing the affordability of the mid-level Experience More plan. This fresh offering makes it easier to enjoy one of the industry’s most benefit-packed unlimited data plans.
Some of the best perks include:.
As a result, households with at least three lines can save over $1,000 per year compared to other postpaid carriers for similar satellite and streaming perks.
For instance, you pay $143 (with AutoPay, plus fees and taxes) for three lines on the T-Mobile Better Value Plan, saving $100 or more because other companies can charge extra for multiple add-ons.
In addition to multiple built-in free benefits, T-Mobile tends to charge less per month than its peers for similar unlimited talk, text, and data plan tiers. This approach helps stretch your spending power compared to sticking with your current plan.
I also like the 5-Year Price Guarantee, which locks in your savings for at least two years longer than competing plans.
Data priority and network reliability are also critical factors when comparing carriers. After all, are the potential savings worth it if you can’t use the high-speed data when you need it for work, travel, or making a time-sensitive decision?
According to recent reports, I primarily base my comparison on monthly cost and data limits. Next, I review coverage maps to estimate potential speeds in the areas I use my phone most frequently. Value Proposal families enjoy first access to the network’s fastest speeds. Therefore, they are the least likely customers to experience throttling during peak usage.
Capable devices will also notice these advantages:.
Entry-level unlimited family plans are less generous and more likely to impose monthly data caps, which can affect customers who often cannot connect to Wi-Fi hotspots.
Sources indicate that based on tests during the second half of 2025, Ookla® Speedtest® rated T-Mobile’s 5G network as the largest and fastest in the United States. That means fewer dead spots in rural areas and more consistent 5G coverage quality nationwide.
Sources indicate that for the first time in tech giant history, T-Mobile ranks as #1 for network quality in a 2026 J.D. Power study. These accomplishments stem from multi-billion-dollar investments, including the acquisition of the Sprint and U.S. Cellular networks.
It has been revealed that moreover, high-speed 4G LTE data is available in most areas, even where 5G isn’t yet. Approximately 99% of the nation’s population can utilize the second-fastest data speed.
Even better, you can try the T-Mobile network risk-free for 30 days before switching from your existing service to test the coverage quality for yourself.
Recent findings suggest that I analyze recent real-world tests, as carriers continually add towers and increase speeds in both urban and rural areas. I’ve avoided certain providers with spotty reception and inconsistent speeds, but later switched to a better plan once the quality improved.
Globetrotters and families with relatives living abroad stand to benefit greatly from a initiative with free talk, text, and data allowances, avoiding the need to purchase add-on packages or pay by the minute, as entry-level plans and rival networks require.
The T-Mobile Value Blueprint global communication benefits include:.
There are no setup or roaming charges involved. This convenient feature is excellent for short-term visits and vacations, without requiring a local SIM card or relying solely on Wi-Fi. You can easily pay a $10 or more for an international day pass for overseas talk, text, and data.
Sources indicate that depending on your blueprint, your international talk and text allowance may be limited to a specific destination or region. These restrictions increase the odds of incurring add-on charges to keep the conversation going.
Additional travel benefits include a 1-year AAA membership for in-depth travel planning resources and exclusive travel discounts. T-Mobile Travel, an online booking website, helps you save on select hotel and rental car bookings at home and abroad.
The carrier also offers free in-flight Wi-Fi on aircraft equipped with it within the Alaska, Delta, Hawaiian, and Southwest Airlines fleets, so you can watch or work from the sky.
Multiple high-end phone intends, as well as prepaid plans, offer free streaming and entertainment benefits that help reduce your monthly spending.
While this factor may play only a secondary role in your blueprint selection, it’s worth comparing your cost savings if you presently have multiple subscriptions. Consumers consistently report that T-Mobile offers the most free streaming options among traditional and prepaid looks.
You can watch on-demand content on two platforms free of charge:.
Apple TV is available for $3 per month. This service typically costs $10.
Industry observers note that T-Mobile’s Magenta Status is a free loyalty program that can be easy to overlook at first but offers recurring savings throughout the year. Check out T-Mobile Tuesdays in the T-Life app to find limited-time offers for free streaming and entertainment passes.
It has been revealed that the carrier states that the retail value for its lifestyle benefits and other perks exceeds $200 in monthly savings for its flagship Experience Beyond and Better Value prepares. Different providers may offer similar perks relevant to your interests to help you choose the best fit.
Most phone prepares attract latest customers by offering exclusive trade-in and upgrade deals that let them get the latest device at a budget-friendly price.
Unfortunately, existing customers have historically been less likely to qualify for similar savings, and long-term relationships may ultimately lead to frustration due to future monthly payment increases and pricey upgrades that new customers don’t experience.
T-Mobile aims to help Value Initiative customers pay less over the long term, with similar device offers available to both new and existing customers.
Once again, the 5-Year Price Guarantee locks in the same monthly strategy payment (excluding taxes and fees) even after you pay off your upcoming device. You also benefit from this guarantee when bringing your own device, as you pay a predictable rate without a rigid contract.
Switching carriers can be a hassle, as the process can take several hours or even business days to complete.
T-Mobile helps provide peace of mind with these onboarding perks:.
Each family has different strategy needs and spending limits, so it’s essential to review both initial and ongoing features to choose the best family cell phone plan. T-Mobile Best Value excels at offering transparent pricing, reliable coverage, and the industry’s best 5G data speeds for worldwide use, making it an excellent choice for many families for years to come.

AI & Tech
⚖️ Neutral
🌐 Physicianonfire
#21741. A Former Programmer’s AI Reality Check: What Changed Me From an AI Skeptic into an AI Believer, The High Costs that Many Got Wrong, and Opportunities I’m Investing In
📅 07 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
A Former Programmer’s AI Reality Check: What Changed Me From an AI Skeptic into an AI Believer, The High Costs that Many Got Wrong, and Opportunities I’m Investing In
📅 07 Nov 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
In 1980, a benefits consultant named Ted Benna figured out how to.
EV & Auto
⚖️ Neutral
🌐 Moneycrashers
#21740. Donating Your Car? Pick a Charity That Uses It and Deduct What It’s Worth
📅 16 Nov 2026 • ⏱️ 2m • 📖 Standard (494 w)
Donating Your Car? Pick a Charity That Uses It and Deduct What It’s Worth
📅 16 Nov 2026 | ⏱️ 2 min read (494 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- If you itemize and a charity sells your donated car for more than $500, you can deduct no more than the sale price.
- Say your car would sell for $3,000 to a private buyer.
- When a charity sells a donated car, you can deduct up to the sale price, or up to $500 of the car’s value if it sells for $500 or less.
If you itemize and a charity sells your donated car for more than $500, you can deduct no more than the sale price. Give the car to a charity that will use it or hand it to a family in need, and you can deduct up to what a private buyer would pay.
Say your car would sell for $3,000 to a private buyer. A car-donation middleman that auctions it for $700 caps your deduction at $700, while a charity that drives it on meal deliveries every day for a year lets you deduct up to $3,000.
When a charity sells a donated car, you can deduct up to the sale price, or up to $500 of the car’s value if it sells for $500 or less. You can deduct up to the car’s full value when the charity puts it to significant use in its work, makes major repairs that greatly raise its value, or gives or sells it far below value to someone in need. The charity certifies which on Form 1098-C.
You can deduct either amount only if you itemize rather than take the standard deduction, and from 2026 only the part of the year’s gifts above 0.50% of adjusted gross income. On the standard deduction, a donated car brings no tax break, since the deduction non-itemizers can take from 2026 covers cash only, so selling the car yourself and giving the cash can do more.
According to recent reports, when a for-profit tech giant runs a charity’s car program, as much as 80% of your donation can go to fundraising and overhead, Minnesota’s attorney general warns. A charity that handles the sale itself keeps all the profit.
Industry observers note that 1-800-Charity Cars, which Charity Navigator rates three of four stars, takes cars nationwide, gives some to struggling families, and keeps all the proceeds from the rest. Before you commit, get in writing whether the charity will use your car, give it away, or sell it. Then look it up on Charity Navigator and confirm in the IRS’s Tax Exempt Organization Search that it can take deductible gifts.
Industry observers note that at pickup, sign the title over to the charity by name, never leaving the buyer’s line blank. Remove your plates unless your state requires otherwise, file your state’s release of liability, and cancel the insurance. Then watch for Form 1098-C within 30 days of the sale or donation, since you need it to deduct more than $500.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every organization or offer available in the marketplace.
General
⚖️ Neutral
🌐 Physicianonfire
#21739. Latest Update: The Sunday Best (11/08/2026)
📅 08 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
Latest Update: The Sunday Best (11/08/2026)
📅 08 Nov 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
In 1980, a benefits consultant named Ted Benna figured out how to.
Gadgets
⚖️ Neutral
🌐 Wellkeptwallet
#21738. How to Cut Your Cell Phone Bill by $1,100 a Year (Without Sacrificing Coverage)
📅 23 Mar 2026 • ⏱️ 6m • 📚 Deep Dive (1288 w)
How to Cut Your Cell Phone Bill by $1,100 a Year (Without Sacrificing Coverage)
📅 23 Mar 2026 | ⏱️ 6 min read (1288 words, 📚 Deep Dive) | Source: Wellkeptwallet
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- In a recent development, this article is brought to you by our sponsor, T-Mobile.
- It wasn’t too long ago that you typically had to pay top dollar for reliable cell phone coverage in both urban and rural areas.
- Sources indicate that sharing a plan with family and friends with straightforward pricing is one of the easiest ways to spend less money, as each additional line provides.
In a recent development, this article is brought to you by our sponsor, T-Mobile. We only partner with brands of the highest quality that we believe are a good fit for our audience.
It wasn’t too long ago that you typically had to pay top dollar for reliable cell phone coverage in both urban and rural areas. In an age of ever-rising prices, T-Mobile is challenging the status quo by allowing families to pay $100 less per month while still enjoying fast, reliable data and a host of premium perks.
Sources indicate that sharing a plan with family and friends with straightforward pricing is one of the easiest ways to spend less money, as each additional line provides. Family plans tend to offer better multi-line discounts for comparable benefits.
Few things are more frustrating than signing up for a cell phone proposal that seems like a good deal up front but ends up with hidden fees, pricey add-ons, and strict contract terms.
According to recent reports, thankfully, T-Mobile’s Better Value Plan provides a competitive monthly base rate and no hidden fees for unlimited talk, text, and data. Family and friends enjoy greater discounts to access T-Mobile’s 5G Ultra Capacity speeds for less than the carrier’s other flagship prepares.
Sources indicate that specifically, Better Value Initiative families pay less than $50 per line (before fees and taxes). Similar postpaid prepares typically cost $10 more per month before adding any optional features.
Here’s a quick monthly cost comparison for four lines plus popular streaming and travel perks:.
According to recent reports, *Note: These price quotes include AutoPay discounts for the base plan rate for voice, text, and data. Optional services increase your monthly carrier and differ by carrier.
According to recent reports, as a result, you’re more likely to pay less than other national carriers by choosing the T-Mobile Better Value Plan while getting more high-speed data and perks. For instance, you could save $92.48 per month or $1109.67 per year compared to the other cell phone provider plan “A” above.
Moreover, the 5-Year Price Guarantee ensures a fixed base rate (excluding taxes and fees) for a period substantially longer than that offered by other national carriers. For instance,other cell phone providers offer the next-best price protection period, which lasts only three years.
In addition to being cheaper than the competitors, The Better Value Plan is also more affordable than T-Mobile’s flagship Experience Beyond plan. You receive similar data allowances and streaming benefits, saving $45 per month on a four-line plan.
Industry observers note that unlimited data prepares start throttling heavy data usage at widely different thresholds. As a heavy data user, you’re essentially forced to either choose a more expensive plan to avoid slower speeds or stay with a cheaper yet flawed plan.
Recent findings suggest that it’s crucial to look beyond the sticker price and compare the monthly limits and streaming capabilities. Unfortunately, low-cost prepaid and traditional looks are the first to experience slower speeds during peak network congestion.
Instead of encountering data anxiety, T-Mobile’s Better Value Plan delivers notably higher limits than competing aims at a lower price. As a result, you may likely never experience throttling again if you’re perpetually relying on cellular data.
Better Value Blueprint members enjoy these unlimited data perks:.
In a recent development, in the past, many households avoided switching to T-Mobile because of nationwide coverage issues. Despite generous data limits, the budget-friendly aims were not worth the headache, and you were forced to pay more with another traditional carrier just to have coverage.
Recent findings suggest that however, consumer sentiment is changing with T-Mobile winning multiple awards for network performance in 2025. Specifically, this is the first time that J.D. Power designated T-Mobile as #1 for network reliability.
According to recent reports, in most situations, multiple customer reviews confirm that this is no longer the case. Longtime customers who switched in the past decade repeatedly report that coverage quality and data speeds have significantly improved in many areas of the country.
Sources indicate that there are also multiple accounts of upcoming customers who tried the T-Mobile network in the past and left displeased due to inconsistent data speeds or spotty coverage. Many are impressed with the improvements, especially since 2023.
You may also appreciate T-Mobile’s 30-day risk-free period to test the network’s coverage quality for your daily usage before leaving your current carrier.
Replacing a phone can be expensive, and constantly switching prepares to secure the best signup offers may result in paying more over time.
Industry observers note that instead of reserving the best phone deals only for new customers, T-Mobile offers them to all customers. Timing your phone upgrade becomes less urgent, so you can focus on finding the most affordable plan for your long-term needs rather than which carrier offers the cheapest device.
As a reminder, T-Mobile’s 5-Year Price Guarantee makes predicting your monthly base rate easier so you can focus on other financial priorities.
The carrier also lets you trade in your current device and take advantage of financing offers to minimize your device costs, without switching to a pricier plan or a less desirable carrier.
Traditional phone looks may offer discounted bundles for wearable and home internet services.
For example, Better Value Proposal customers enjoy these preferred rates:.
In a recent development, the complimentary T-Satellite access facilitates text messaging and satellite-ready apps. This feature becomes more valuable as more satellite-ready apps become available for communication, navigation, and email outside of the cellular network.
The discounts from these add-on services make it easier to make a spending plan and provide peace of mind for staying connected at home or on the go.
It has been revealed that free streaming prepares courtesy of your phone blueprint are another effortless way to reduce your monthly spending by at least $100 per year. Studies indicate that 89% of households pay for at least one streaming service.
Recent findings suggest that T-Mobile is famous for taking it a step further by offering more entertainment perks than other companies, making it easy to enjoy over $300 in savings if you use these platforms. Your current carrier may only offer discounted rates for streaming apps.
You will enjoy throttle-free 4K Ultra HD streaming quality on capable devices where premium data speeds are available.
The industry-leading 250GB of mobile hotspot data means you can repeatedly connect a tablet or laptop to work, stream, or surf the web while traveling or running errands without setting up a separate add-on device line.
T-Mobile periodically provides discounted and complimentary memberships to music and streaming apps through its free Magenta Status program. The carrier releases exclusive offers each Tuesday on the T-Life App.
As a result, your annual savings compound if you’re right now paying for add-on services that Value Plan offers at no extra cost.
Frequent travelers are also likely to benefit from the Better Value Strategy’s built-in international travel benefits:.
The above-average data allowances are also beneficial for longer trips or if you need to consume lots of data for navigation and video calls while abroad.
It has been revealed that in most situations, these features eliminate the need to buy add-on roaming packages or day passes that other plans may require to use your phone abroad. These passes may have relatively low daily usage limits to watch out for too.
Whether traveling abroad or domestically, other potential travel savings include a one-year AAA membership and up to 40% off hotels and rental cars.
Start by analyzing your current spending habits and phone usage to calculate your savings.
T-Mobile’s Value Proposal makes it easier for households to tap into award-winning 5G data coverage and multiple streaming apps at a competitive monthly cost.
General
⚖️ Neutral
🌐 Moneycrashers
#21737. Where to Donate Used Books – 11 Places and What Each One Takes
📅 16 Nov 2026 • ⏱️ 2m • 📖 Standard (320 w)
Where to Donate Used Books – 11 Places and What Each One Takes
📅 16 Nov 2026 | ⏱️ 2 min read (320 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- Before you donate used books, sort them by who will read them: picture books for a classroom, novels for your library’s used-book sale, and paperbacks for a prison book program.
- Sources indicate that A box left at the library’s front desk isn’t sure to find a reader.
- Every place that takes used books has its own readers and its own limits, often on a book’s format, age, or condition.
Before you donate used books, sort them by who will read them: picture books for a classroom, novels for your library’s used-book sale, and paperbacks for a prison book program. Then check what each place accepts, because many turn away encyclopedia sets, old textbooks, and water-damaged copies.
Sources indicate that A box left at the library’s front desk isn’t sure to find a reader. Most public libraries accept donated books only if they’re free to keep each one, sell it at a book sale, or discard it, the American Library Association claims.
Every place that takes used books has its own readers and its own limits, often on a book’s format, age, or condition. Encyclopedia sets and books with mold, water stains, or missing pages are the hardest to place, since few groups take them at all.
Here’s what 11 places take, how to get books to each, and whether you’ll get a receipt, starting close to home and ending with groups that take books by mail.
Industry observers note that A family packing for a move might give picture books to a kindergarten teacher, novels to the library’s Friends sale, and paperbacks to a prison book program, then recycle the water-damaged rest. Any book you wouldn’t hand to a friend goes in that recycling pile too.
To donate the rest of what you’re clearing out, compare the best places to donate your used stuff.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Industry observers note that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every firm or offer available in the marketplace.
🔗 Related Articles
📰 #21734. Where to Donate Used Toys – 16 Places That Take What Toy Drives Won’t 📰 #23527. 10 Best AI App Builders I've Used in 2026 (and What Each One Gets Wrong) 📰 #16252. Industry News: I used Google's new Gemini 4 Hydrogen to find out where my paycheck goes — and it only took one prompt
General
⚖️ Neutral
🌐 Physicianonfire
#21736. Why The 401(k) Still Dominates (Even Its Inventor Has Doubts)
📅 10 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (15 w)
Why The 401(k) Still Dominates (Even Its Inventor Has Doubts)
📅 10 Nov 2026 | ⏱️ 1 min read (15 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
Those who make more money can also save more money. Shocker.
🔗 Related Articles
📰 #18288. Latest Update: VCs Are Still Chasing Protein, Even As Fake Meat Falls Out Of Favor 📰 #16597. Sam Altman Is “Still Unknowable” to Andrew Garfield, Even After Playing the OpenAI Co-Founder in Artificial 📰 #12942. Why heart attacks can still happen even when bad cholesterol is low
General
⚖️ Neutral
🌐 Wellkeptwallet
#21735. Latest Update: Crew Review: High-Yield Checking With Built-In Budgeting for Families
📅 20 Apr 2026 • ⏱️ 8m • 📚 Deep Dive (1635 w)
Latest Update: Crew Review: High-Yield Checking With Built-In Budgeting for Families
📅 20 Apr 2026 | ⏱️ 8 min read (1635 words, 📚 Deep Dive) | Source: Wellkeptwallet
⏱️ ~8 mins left to finish
📖 0% read
💡 Key Takeaways
- Sources indicate that managing money as a household is harder than it looks.
- It has been revealed that crew is a fintech app that tries to put all of that in one place.
- Industry observers note that in this Crew review, we cover what it is, how it works, who it’s best for, the key features, pricing, and what real people are saying.
Sources indicate that managing money as a household is harder than it looks. Most people use a regular checking account at a big bank, then juggle a separate budgeting app, maybe a savings account somewhere else, and possibly a kids’ debit card on top of that. It’s a lot to keep track of.
It has been revealed that crew is a fintech app that tries to put all of that in one place. It combines a high-yield checking account, built-in budgeting tools, and family banking features – all inside a single app. The goal is to help you organize your money, automate your budget, and earn more interest without switching between apps.
Industry observers note that in this Crew review, we cover what it is, how it works, who it’s best for, the key features, pricing, and what real people are saying. If you’re looking for a smarter checking account that does more, this review gives you the full picture.
Crew is a fintech app that tries to put all of that in one place. It combines a high-yield checking account, built-in budgeting tools, and family banking features.
• High-yield checking • Debit cards available for kids• Unlimited budgeting pockets• Cash deposits and mobile check deposit• No monthly fees or minimum balances.
• App-only banking with no desktop login• No physical check writing.
In a recent development, crew is a financial technology (fintech) manufacturer based in Lehi, Utah. It was founded by Gentry Davies and Steve Domino, who previously worked at Divvy, a business expense platform acquired by Bill.com. The app introduced publicly and has been growing steadily since 2023.
Crew is not a bank. Banking services are provided by Bangor Savings Bank, which is FDIC-insured. Your deposits are held at Bangor Savings Bank, so they are protected up to federal insurance limits – $250,000 for individual accounts and $500,000 for joint accounts.
In a recent development, the app is available on both iOS and Android. A web app is currently in beta.
Crew works well for a wide range of people, but it’s especially useful if you fall into one of these groups:.
Crew may not be the right fit for:.
Crew offers a checking account that earns 2.95% APY on your full balance. This rate applies to every dollar you hold in the account – there’s no minimum deposit requirement and no tiered rate structure.
Why it matters: Most major bank checking accounts pay close to 0.01% APY. Earning nearly 3% on your everyday checking balance can add meaningful interest over time, especially for families keeping a few thousand dollars in their account at any given time.
Recent findings suggest that pockets are virtual “buckets” inside your single Crew checking account. You can create as many as you need – for example, one for bills, one for savings, one for a vacation fund, one for groceries.
Sources indicate that why it matters: You don’t need a separate savings account or multiple bank accounts. Pockets let you visually and mentally divide your money without moving it to another institution. You can also lock a pocket in “piggy bank mode” to avoid dipping into it.
Crew’s Autopilot feature lets you create rules that move money automatically based on triggers. Triggers can be events like a paycheck arriving or a balance dropping below a set level, or they can be time-based, like every Friday or the 1st of the month.
Sources indicate that why it matters: Automation removes the discipline requirement from budgeting. You set your rules once, and Crew handles the rest. For example, you can tell Crew to automatically send 10% of every paycheck to your giving pocket, $500 to bills, and keep the rest in checking — without touching the app every payday.
Industry observers note that why it matters: Most banking apps bolt on a kid’s account as an afterthought. Crew builds family banking into the core experience. Parents get real-time spending notifications, spend controls, and the ability to set automated allowances.
Parents can set up automatic recurring transfers to a child’s account. You define the amount and the schedule, and Crew handles the delivery.
In a recent development, why it matters: Automated allowances teach kids about money while removing the “I forgot to pay your allowance” problem for parents. Kids learn what consistent saving looks like in practice.
According to recent reports, every account member gets a Mastercard debit card. You can switch which pocket your card draws from at any time inside the app – or revision a transaction after the fact if you accidentally spent from the wrong pocket.
Recent findings suggest that why it matters: This setup means budgeting is “baked in” to your spending. Instead of tracking what you spent after the fact, you decide which budget category you’re spending from before or at the time of purchase.
According to recent reports, you can use your Crew Mastercard at any ATM in the Mastercard, Maestro, or Cirrus networks. Crew does not have its own fee-free ATM network, but it reimburses ATM fees for up to 20 withdrawals per year.
Why it matters: The annual ATM fee reimbursement covers most casual cash users without adding much complexity.
Industry observers note that crew supports outgoing wire transfers. The fee depends on your total account balance.
Incoming wires and standard ACH transfers are processed as usual through the app.
Deposits held through Crew are insured through Bangor Savings Bank, a Member FDIC institution.
This is standard FDIC pass-through insurance. Crew’s website states that pass-through insurance is subject to certain conditions set forth in the deposit agreement.
In a recent development, crew includes an AI-powered financial assistant called Penny. Penny can answer questions about your account, help you set up automations, and give you guidance on your financial situation.
Why it matters: Penny gives users a simple way to interact with their finances through natural language, without digging through menus.
One of Crew’s stronger selling points is its simple, low-fee structure. Here’s a clear breakdown:.
Note: APY is variable and may change at any time. The 2.95% rate is the most recent published rate. Always check trycrew.com for the current rate before opening an account.
Opening a Crew account is quick. Most people complete it in under two minutes. Here are the steps:.
To add a family member, go to the Family section of the app and follow the prompts to add a joint owner or create a child account.
In a recent development, no. Crew is a financial technology company, not a bank. Banking services are provided by Bangor Savings Bank, Member FDIC, which is a real, federally insured bank. Your deposits are held at Bangor Savings Bank, so they are FDIC insured up to federal limits.
The APY is variable, meaning it can change over time. It is not a limited-time promotional rate in the traditional sense; it applies to your full balance, with no minimum or expiration. However, Crew can adjust the rate when market conditions change. The rate has fluctuated over the app’s history (it was as high as 3.7% in early 2025). Referral sign-ups may qualify for a 0.5% APY boost for the first three months.
Cash deposit support has been in development. Some reviews noted it was not yet available at the time of writing, though the feature has been in the works. It’s worth checking the current app version or Crew’s website for the latest on cash deposits before signing up if this is important to you.
Sources indicate that you need your legal name, date of birth, physical address, and a tax ID (typically your Social Security number). Most applicants complete the process in under two minutes.
Industry observers note that crew earns revenue in two ways: from the interest it earns on deposits held at Bangor Savings Bank, and from merchant fees when you use your Crew debit card to make purchases. This model is common among fintech companies and allows them to offer no-fee accounts while still generating revenue.
User feedback for Crew is largely positive, particularly among families and people who value built-in budgeting features.
Rating: 4.8 out of 5 stars (based on 179 reviews as of March 2026).
Positive trends from Google Play users include:.
Common critical feedback includes:.
Recent findings suggest that crew’s iOS app carries consistently high ratings. Customers describe it as well-designed and easy to navigate. Family features are frequently praised, with parents noting that kids enjoy having their own card and app login.
Reviewers across platforms repeatedly mention Crew as a genuine alternative to maintaining separate banking and budgeting apps. The combination of high-yield checking, automatic paycheck splitting, and child accounts in one place is the most-cited reason for switching from other banks or apps.
The most consistent piece of constructive feedback is that Crew is still a young product and some features – like the web app – are still catching up to the mobile experience.
Crew is a well-designed fintech product that combines several things that usually require multiple apps or accounts: a high-yield checking account, budgeting through pockets, spending automation, and family banking.
Overall, Crew fills a genuine gap. Most checking accounts don’t pay meaningful interest and don’t have built-in budgeting. Crew does both, and it adds family banking on top. For households looking to simplify their financial toolkit and earn more interest on everyday balances, it’s worth a serious look.
As always, make sure to read the deposit agreement and check the current APY at trycrew.com before opening an account, since rates are variable and can change.
In a recent development, this review is for informational purposes only and does not constitute financial advice. APY rates, fees, and features are subject to change. Always verify current terms directly with Crew at trycrew.com before making any financial decisions.
General
⚖️ Neutral
🌐 Moneycrashers
#21734. Where to Donate Used Toys – 16 Places That Take What Toy Drives Won’t
📅 16 Nov 2026 • ⏱️ 2m • 📖 Standard (300 w)
Where to Donate Used Toys – 16 Places That Take What Toy Drives Won’t
📅 16 Nov 2026 | ⏱️ 2 min read (300 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- Take your used toys where they’ll be resold, handed to a child, or played with, such as thrift stores, foster care programs, child care centers, and neighborhood giveaway groups.
- Sort the pile before you call anyone, because each place wants a different kind of toy.
- Toys in good shape with all their pieces can go almost anywhere below.
Take your used toys where they’ll be resold, handed to a child, or played with, such as thrift stores, foster care programs, child care centers, and neighborhood giveaway groups. Check that each is clean, complete, and not recalled, and skip children’s hospitals and holiday toy drives, which usually take only newly introduced ones.
Sort the pile before you call anyone, because each place wants a different kind of toy.
Toys in good shape with all their pieces can go almost anywhere below. Stuffed animals are harder to give away, since child care centers, doctors’ offices, and many family and domestic violence shelters avoid them for hygiene. Many animal shelters take ones too worn for a child.
In a recent development, thrift stores and charities turn away recalled toys, since selling a recalled product is against federal law. Look up any toy you’re unsure of on the Consumer Product Safety Commission’s recall search.
Here are 16 places that take used toys, with what each accepts and how to give:.
A parent clearing out a playroom might take the board games to an after-school program, give the wagon to a neighbor through a Buy Nothing group, and drop the worn stuffed animals at an animal shelter.
The broken plastic goes in the trash, since most curbside recycling programs don’t take toys.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.
General
⚖️ Neutral
🌐 Physicianonfire
#21733. The Sunday Best (11/15/2026)
📅 15 Nov 2026 • ⏱️ 1m • ⚡ Quick Read (16 w)
The Sunday Best (11/15/2026)
📅 15 Nov 2026 | ⏱️ 1 min read (16 words, ⚡ Quick Read) | Source: Physicianonfire
⏱️ ~1 mins left to finish
📖 0% read
In 1980, a benefits consultant named Ted Benna figured out how to.
General
⚖️ Neutral
🌐 Wellkeptwallet
#21732. Debbie App: Can This App Really Help You Pay Off Debt Faster?
📅 20 Apr 2026 • ⏱️ 4m • 📚 Deep Dive (768 w)
Debbie App: Can This App Really Help You Pay Off Debt Faster?
📅 20 Apr 2026 | ⏱️ 4 min read (768 words, 📚 Deep Dive) | Source: Wellkeptwallet
⏱️ ~4 mins left to finish
📖 0% read
💡 Key Takeaways
- Recent findings suggest that debbie is a debt payoff app built around a truth most people already understand but rarely see addressed in finance tools: paying off debt is not just about numbers, it is about behavior.
- Recent findings suggest that most personal finance apps track balances and interest rates and then stop there.
- Sources indicate that many debt payoff journeys fail in the same place.
Recent findings suggest that debbie is a debt payoff app built around a truth most people already understand but rarely see addressed in finance tools: paying off debt is not just about numbers, it is about behavior. And if behavior is the real challenge, motivation matters more than spreadsheets.
That is where Debbie stands out.
Recent findings suggest that most personal finance apps track balances and interest rates and then stop there. Debbie goes a step further by rewarding people for making progress. When you do the right things consistently, you do not just see your debt go down. You actually get something back.
Sources indicate that many debt payoff journeys fail in the same place. Not at the beginning, when motivation is high, but in the middle, when progress feels slow, and life gets in the way. Debbie is designed specifically for that phase.
Industry observers note that after connecting your credit cards, student loans, or other debts, the app creates a personalized payoff blueprint based on your balances and payment history. The plan is realistic and focused on consistency rather than extreme sacrifices.
As you make payments and reduce balances, Debbie rewards you for that progress.
Rewards can include things like:.
• Cash rewards• Gift cards• Partner offers tied to financial milestones.
These rewards are not meant to eliminate debt on their own. They exist to reinforce the habit of showing up and sticking with the initiative.
Debbie gives users a clean dashboard showing:.
This reduces the mental stress of juggling multiple accounts.
Unlike most personal finance apps, Debbie pays consumers for progress, which helps reinforce positive habits. Over $2,319,961.65 earned by people reaching their money goals.
The app is intentionally designed to be:.
This makes it beginner-friendly, even for people latest to budgeting or debt payoff.
Debbie works best for people who need accountability and encouragement. If you already know what to do but struggle to stay consistent, this app fills an important gap.
• Rewards that reinforce good financial behavior• A clean, easy to understand interface• A focus on progress instead of perfection• Motivation during the hardest part of the journey.
It has been revealed that there are also a few limitations to keep in mind. Debbie is not a replacement for a full budgeting system, and the rewards alone will not move the needle if you are carrying very large balances. You still have to do the work. The app simply makes it easier to keep going.
You will also need to link your financial accounts, which is standard for most modern finance apps but worth noting.
Debbie is a strong fit for people who feel overwhelmed by debt, burned out on traditional budgeting apps, or frustrated that they are doing the right things but still don’t feel any momentum.
In a recent development, if you are already highly disciplined and managing everything with detailed spreadsheets, you may not need the additional reinforcement. For most people, though, motivation is the missing piece.
In a recent development, yes. Debbie is a legitimate personal finance app built around a behavior-driven debt payoff model. While it won’t magically erase debt, it helps people stay engaged, which is often the biggest missing piece in successfully paying off debt.
Sources indicate that if you’re exploring Debbie, there are several other financial wellness and money-saving apps worth considering. Each app offers a different approach to helping users improve their finances, build better habits, or earn rewards.
Acorns automatically invests your spare change by rounding up purchases to the nearest dollar. It’s designed for beginners who want a simple, hands-off way to start investing.
Rocket Money focuses on budgeting, subscription tracking, and lowering monthly bills. It can help people identify recurring charges and negotiate certain expenses on their behalf.
Qapital combines budgeting with automated savings goals. Customers can create custom “rules” that move money into savings automatically based on spending habits or milestones.
In a recent development, YNAB is a budgeting app built around giving every dollar a purpose. It’s popular among people who want a more hands-on system for managing cash flow and paying off debt.
Recent findings suggest that paying off debt is rarely about knowledge. Most people already know what they should be doing. The real challenge is sticking with the plan month after month, even when progress feels slow.
Recent findings suggest that debbie helps solve that problem by rewarding progress, reinforcing positive habits, and making the journey feel less discouraging. It will not magically erase debt. But it can absolutely help you stay consistent long enough to change your financial life.
General
⚖️ Neutral
🌐 Moneycrashers
#21731. Uber Eats Courier Review – Up-Front Pay Includes the Tip, Not Your Costs
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (266 w)
Uber Eats Courier Review – Up-Front Pay Includes the Tip, Not Your Costs
📅 16 Nov 2026 | ⏱️ 1 min read (266 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Sources indicate that deliver for Uber Eats if you live in a busy delivery market and want to set your own hours.
- It has been revealed that the pay an Uber Eats offer shows is what you earn before self-employment tax and, if you drive, the cost of your miles.
- In a recent development, uber Eats suits couriers in busy delivery markets who want to set their own hours, especially drivers who can also take ride requests.
Sources indicate that deliver for Uber Eats if you live in a busy delivery market and want to set your own hours. Each offer demonstrates its pay, with any tip added at checkout, before you accept, so take only offers that pay more than the trip costs you. Drivers approved to carry passengers can add rides in the same app.
It has been revealed that the pay an Uber Eats offer shows is what you earn before self-employment tax and, if you drive, the cost of your miles. Uber pays couriers by the completed delivery, not the hour, so subtract both to work out what each hour pays you.
In a recent development, uber Eats suits couriers in busy delivery markets who want to set their own hours, especially drivers who can also take ride requests. Couriers who’d rather be paid for their time should compare DoorDash, whose Earn by Time mode guarantees a minimum hourly rate from acceptance to drop-off in select U.S. cities.
Learn more about Uber Eats Courier or see how it compares to the best delivery apps to work for.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every tech giant or offer available in the marketplace.
Business & Policy
⚖️ Neutral
🌐 Mrmoneymustache
#21730. Breaking: How to Navigate the Tariff Circus
📅 13 Jun 2025 • ⏱️ 12m • 📚 Deep Dive (2441 w)
Breaking: How to Navigate the Tariff Circus
📅 13 Jun 2025 | ⏱️ 12 min read (2441 words, 📚 Deep Dive) | Source: Mrmoneymustache
⏱️ ~12 mins left to finish
📖 0% read
💡 Key Takeaways
- Quite accidentally, it looks like we timed our last talk about the stock market pretty darned well.
- And although stock market volatility doesn’t always come with an easily labeled explanation, this time the reason seems pretty clear: it’s the Tariffs.
- As our financial world has been whipped around like a circus tent in a hurricane for the last several months, almost everyone who has a stake in this country has been wondering what to make of it.
Quite accidentally, it looks like we timed our last talk about the stock market pretty darned well. Back in February 2025, the market put the perfect cap on a multi year climb before stepping onto the wild roller coaster we’re currently riding. Since then it has seen some of the steepest drops and recoveries in history, losing a full 20% of its value at the bottom while somehow managing to end up right back near the peak as I’m writing this.
And although stock market volatility doesn’t always come with an easily labeled explanation, this time the reason seems pretty clear: it’s the Tariffs.
As our financial world has been whipped around like a circus tent in a hurricane for the last several months, almost everyone who has a stake in this country has been wondering what to make of it.
As I write this, we still don’t know the outcome of the worldwide tariff and trade battle that our unpredictable government has unleashed upon the world. But we’re already seeing the results: businesses are bracing for massive changes, currencies and interest rates are reacting, and regular investors like you and me are wondering what the future holds for our early retirement funds. Surveying my own group of friends, the reactions span the whole range of emotions from “this is a giant Nothingburger” to “we’re all totally screwed.”.
According to recent reports, so what’s the real answer? To get closer to that, we should start with the most basic question of:.
Sources indicate that A tariff is just a sales tax charged by our government on goods which are imported into the country. They are paid by whoever is doing the importing – meaning you if you order something like an e-bike directly from a company in China, or by companies like Amazon, Walmart, or Apple which import products from other countries by the shipload.
It has been revealed that but in the end, the tariffs aren’t paid by China or Amazon or Apple. They are paid by you, the end consumer, because if their cost of goods increases, a retailer is of course going to raise their prices to continue to make a profit.
In a recent development, tariffs also affect companies directly: if Home Depot wants to build a newly introduced store or Chevron needs a new oil rig, the tariffs on imported steel, copper, lumber and a million other components will raise the cost of these construction projects. And they raise the cost of housing, because most of the building materials in houses come from multiple countries as well.
Sources indicate that on average, tariffs will result in higher prices for everything just like any other broad-based sales tax. And just like most other taxes, the overall effect is to slow the economy and reduce our spending power. On the positive side, all that tax money flows into the government’s pocket which could help fund the national budget and even reduce the deficit.
Of course, every government needs at least some tax revenue to function, so it makes sense to use some mix of sales, income and corporate taxes to get there. The most important part is that the levels need to be as low as possible while still keeping the country running well, and as fair and predictable as possible, so that people and businesses have an incentive to work hard and the ability to proposal far into the future.
Sources indicate that and that’s where our current tariff regime gets it completely backwards. Donald Trump is throwing around random, extremely high tariff numbers as threats, then walking them back and changing them on an almost daily basis..
Whoa, that Sounds Mostly Bad – Is There a Good Side of Tariffs?
Sometimes, a country will use tariffs to protect their own domestic industries. For example, if you put a tax on imported Hondas, then General Motors cars will gain a competitive advantage – so GM will make more money. In this example, most consumers end up losing due to increased prices and decreased selection. But at least domestic auto manufacturers and their employees are happy.
This can be strategic (for example we might want to slap a tax on imported fighter jets to make sure Boeing and Lockheed can remain in business, for national defense purposes.) Or it can be corrupt (a politician might receive funding from kingpins in the steel industry, and in return then push through tariffs on imported steel to protect the profits of US steelmakers.).
According to recent reports, and this isn’t just a Trump or Republican thing either – Joe Biden used tariffs during his terms in an attempt to please swing-state voters. One of the worst examples was a tax on imported solar panel components (which Trump has since raised even further, proving that Boneheadedness can be Bipartisan). These are sheets of cheap glass that literally pump the cheapest energy and easiest wealth into your country for 30 years as soon as you plug them in. Cheap energy lowers everyone’s cost of living while also boosting industry. There is no good reason to block such wealth from flowing across your borders.
Can Tariffs Bring Us More Jobs?
Let’s go back to that hypothetical tax on Hondas, and let’s say it’s a major one like $5000. At that level, many buyers will start heading over to the GM dealer next door to consider what he’s selling. Sure, the GM cars may not be as good, but for five grand some people are going to settle in order to save some money.
Because of this, GM’s sales go up. So they hire more employees and build more factories. They might even develop some fresh models and new technologies in response to all that new demand. More people learn advanced skills and in the best case it becomes a virtuous circle.
It has been revealed that but in exchange for this boom in the auto industry, everyone else has to pay more for slightly shittier cars and trucks. Higher vehicle prices means Amazon will have to spend more on their delivery fleet, so they will raise prices slightly on everything they sell. Somewhere a startup company or a medical breakthrough will be just a bit less likely to happen, because they are operating in an environment that is just a bit more expensive and a bit less efficient.
It has been revealed that on top of that, with GM liberated from the hassle of competing with Honda, it will have less incentive to innovate and streamline itself. So its overall trajectory will be slower and less efficient even if its profits are higher.
This substantial picture effect is why most economists agree that tariffs should be used very sparingly. They almost always cause unexpected damage, decrease overall employment and slow down an economy, but sometimes (like for food security or national defense) those costs are worth paying.
So Why is Donald Trump Throwing Around Tariffs Like They Are The Best Thing Ever?
It has been revealed that this has been confusing to almost everyone. If you take him at his word, he appears to have a Bizarro Opposite Universe belief system about economics. Donald has claimed in speeches that the tariffs will somehow make us wealthier. He’s focusing on the first-order effects like GM hiring more workers, while completely ignoring the fact that everything else in the country gets less efficient in exchange.
It has been revealed that but when he unveils larger tariffs, share prices go down, because everyone who actually runs or invests in US companies knows that of course they will make less money on average. When tariffs are paused or reduced, share prices go back up. Yet he keeps wielding the threats and we go back and forth.
It seems to be obvious to everyone except Donald himself that Tariffs are just a national sales tax rather than some clever sneaky strategic weapon, which leads to various theories that okay, maybe he knows that too but is just pretending in order to gain some influence.
The basic theory goes like this:.
So right now our entire economy is subject to the whims of a single person.. And as long as this is the case, we’re just the same as any other dictatorship – something our constitution was supposed to prevent with the whole “three independent branches of government” thing.
But presidents have tried to break out of their constitutional cage and get more power many times in the past, and this is just the latest example. The real test will be if our system eventually manages to stop this abuse and put itself back in balance as it always has in the past. You can already see this fight beginning to play out in our court system, in this Economist article:.
How Big are the Tariffs Right Now?
Sources indicate that even without the 145% nonsense numbers that were thrown around a few months ago, they are still far higher than they have been in the last 75 years or more. While it would be hard to pin down the current numbers in a stationary blog post like this one, the key thing to remember is that our current US economy is built around very low tariffs and relatively free trade.
Why haven’t I noticed Prices Going Up Yet?
While the US economy is fueled by a constant stream of cargo ships, as a whole we function like the biggest cargo ship of all: we have a huge inventory and it takes a while to change directions.
So in normal times, we already have several months of inventory of most things in the country. And then when all this drama started, importers started placing even more orders to stockpile things in advance before the tariffs hit. And now that they are in place, we’re importing a lot less stuff.
For now, we’re still using up the stockpiled inventory, but imports have dropped significantly so we’re rapidly running out of cheap goods. If that happens, we will probably start seeing shortages and price increases throughout this summer or fall. For some things like plastic party trinkets, we can do just fine without. But if we lose access to core useful things like tools and machinery, the economic consequences will be much less fun.
The Dark Side and the Bright Side.
Industry observers note that the most important phrase to remember in US politics and economics is the phrase “This too shall pass.” The only mystery right now is that we don’t know exactly how it will pass. So we could sketch out a few scenarios:.
1) The current crazy-high tariffs really do stick around:.
Recent findings suggest that I personally think this is the less likely scenario because nobody really wants it. But just as a thought experiment, it might go something like this:.
2) They do end up being just a negotiating tactic and we go back to mostly low tariffs.
In other words, the best way to win the tariff game is not to play it.
According to recent reports, just as much of US prosperity is built upon our huge population of 330 million people living in 50 states with open borders and no trade restrictions, all (friendly) countries of the world can benefit from the free exchange of goods, services and even people. We’re all human beings and if we treat each other with a collaborative respect, we all grow richer.
Epilogue: Is it Almost Over Already?
It has been revealed that I started writing this article on April 2nd, when Donald announced his “Liberation Day” and the stock market reacted with the biggest drop since 1932. Some people panicked and locked in big losses despite decades of warnings from your favorite financial bloggers, like this unfortunate soul in the comments to a JL Collins post:.
But as I watched over the next two months, we have bounced our way back up – with each drop in proposed tariffs triggering a corresponding increase in stock prices (a measure of investor enthusiasm of how bright our future looks).
According to recent reports, right now, the US stock market is just about back to its all-time high. This doesn’t match with our current level of tariffs, which are still about seven times higher than they were before the circus opened. But it shows that investors believe it’s all going to end with a truce and a resumption of free-ish international trade.
If they’re wrong, the roller coaster ride will still have some more fun in store for us. But as long as we eventually end our current experiment in “emergency” tariff dictatorship and get back to functioning as a democracy, things should be just fine in the long run. I’m still 100% invested myself, so that’s where I place my bet.
The Biggest Lesson: Don’t Form Your Opinions Based on News Headlines.
Industry observers note that decades ago in a brighter age of journalism, there may have been a time when headlines were designed primarily to inform us, with just a bit of sizzle and spice to pull in our attention. Unfortunately, nowadays the priorities have flipped where the primary goal is attention, and accuracy carries little or no weight. Even a totally inaccurate article makes money for the publisher.
So while Democrats and Republicans like to do battle over which media sources are biased, in reality they’re all wrong: all click-funded commercial media is biased – sometimes politically but even more importantly biased towards generating outrage and fear, because those generate more money.
There are two solutions to this:.
1) Either ignore the media completely and focus on your own life, or.
2) Become a subject matter expert on things you really care about, and then read the original sources whenever you want to learn about something.
I mostly practice option #1, but as a science and technology nerd I get into #2 in just the areas I find most interesting. And it’s amazing how the more deeply you understand a subject, the more you see just how wrong most media stories are about your area of expertise. Which means they’re probably pretty wrong about almost everything.
In a recent development, so as always, with this lesson learned it’s time to shut down that phone and laptop, exhale all our worries and get back outside with your real-life family and friends. See you in a few months!
Why We Are Not Really All Doomed – the original all-purpose MMM article which explains why we never really have to worry about the long-term economic future.

General
⚖️ Neutral
🌐 Wellkeptwallet
#21729. Tech Report: What Is Dollar Cost Averaging?
📅 07 May 2026 • ⏱️ 6m • 📚 Deep Dive (1107 w)
Tech Report: What Is Dollar Cost Averaging?
📅 07 May 2026 | ⏱️ 6 min read (1107 words, 📚 Deep Dive) | Source: Wellkeptwallet
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- If the idea of putting money into the stock market makes you nervous, you are not alone.
- Dollar cost averaging is a strategy that takes that worry off the table.
- In this article, we will explain how dollar cost averaging works, why so many long-term investors rely on it, and how to put it into practice starting today.
If the idea of putting money into the stock market makes you nervous, you are not alone. A lot of people hold back because they are afraid of buying at the wrong time.
Dollar cost averaging is a strategy that takes that worry off the table. Instead of trying to time the market perfectly, you invest a fixed amount on a regular schedule and let time do the heavy lifting.
In this article, we will explain how dollar cost averaging works, why so many long-term investors rely on it, and how to put it into practice starting today.
Sources indicate that dollar cost averaging (DCA) is an investment strategy in which you invest a fixed dollar amount in a specific asset at regular intervals, regardless of market conditions. Whether the market is up, down, or flat, you invest the same amount on the same schedule.
The result is that you end up buying more shares when prices are low and fewer shares when prices are high. Over time, this can lower your average cost per share compared to making a single lump-sum investment at the wrong moment.
Most people already practice dollar cost averaging without realizing it. If you contribute to a 401(k) every time you get a paycheck, that is dollar cost averaging in action.
According to recent reports, the mechanics are straightforward. You pick an investment, decide on a fixed dollar amount, and choose a schedule. Every week, every two weeks, or every month, you invest that amount, no matter what the market is doing that day.
Recent findings suggest that because you are investing a fixed dollar amount rather than a fixed number of shares, your money automatically buys more shares when prices dip and fewer when prices climb. This built-in dynamic is what makes the strategy so useful for investors who want to build wealth steadily without spending hours watching the market.
According to recent reports, for most people, low-cost index funds are the best vehicle for this strategy. They give you broad diversification across hundreds of companies in a single investment, and their expense ratios are far lower than actively managed mutual funds or target-date funds. That difference in fees compounds significantly over decades.
Recent findings suggest that say you decide to invest $300 every month into a low-cost S&P 500 index fund. Here is what three months might look like:.
It has been revealed that after three months, you have invested $900 and own 21 shares. Your average cost per share is $42.86. If you had invested all $900 in Month 1 at $50 per share, you would only own 18 shares. The dip in Month 2 actually worked in your favor because you had cash ready to put to work at a lower price.
This is the core idea. You stop worrying about whether today is a good day to invest and start focusing on building a consistent habit instead.
It removes emotion from investing.
According to recent reports, one of the biggest mistakes investors make is letting fear and excitement drive their decisions. They pile in when the market is hot and pull out when it drops. Dollar-cost averaging sidesteps all of that by turning investing into a routine, like paying a bill, that runs automatically on a schedule.
It makes market downturns work for you.
In a recent development, when markets fall, most people panic. With dollar cost averaging, a dip is simply an opportunity to buy more shares at a discount. If you stay consistent, you will naturally accumulate more of your investment when it is on sale.
It is accessible no matter your income.
You do not need a large lump sum to get started. Even small, consistent contributions can grow meaningfully over time thanks to compounding. A good starting point is to aim for at least 10% of your gross income going toward investments. If that feels like a stretch right now, start with whatever you can manage and increase it over time.
It has been revealed that consistency is the real edge in personal investing. Dollar cost averaging encourages exactly that. When you automate your contributions, investing happens in the background while you get on with your life.
It has been revealed that want a free tool to help you keep track of your investments? Check out Empower!
Dollar cost averaging is a sound strategy, but it is worth understanding its limits before you dive in.
According to recent reports, if you are investing in a low-quality asset that trends downward over time, buying it consistently will not save you. That is why what you invest in matters just as much as how you invest. Sticking to broad, low-cost index funds gives you exposure to the overall market rather than betting on a single company’s performance. Investing heavily in individual stocks introduces a level of risk that most people do not need to take on.
Alternative investments should stay small.
Things like gold, cryptocurrency, and other alternative assets can have a place in a portfolio, but they should stay well under 10% of your total invested assets. These assets tend to be far more volatile and speculative than a diversified index fund, and there is no reason to let them dominate your long-term strategy.
A lump sum can outperform in a rising market.
Sources indicate that research has shown that if you have a large sum ready to invest, putting it all in at once tends to outperform dollar cost averaging over the long run, simply because markets go up more often than they go down. That stated, most people do not have a large lump sum sitting around. For those building wealth paycheck by paycheck, dollar cost averaging is the practical and sensible path.
According to recent reports, getting started with dollar cost averaging does not require a financial advisor or a complicated setup. Here is a simple framework:.
It has been revealed that dollar cost averaging is one of the most practical investing strategies available to everyday investors. It takes the guesswork out of market timing, helps you build a consistent habit, and naturally positions you to benefit from market dips over time.
Sources indicate that the key is to pair this strategy with the right investments. Low-cost index funds are a strong foundation. They offer diversification, keep fees low, and have a long track record of rewarding patient investors. Avoid concentrating too much on single stocks or speculative alternatives, and keep contributing regularly regardless of what the market is doing on any given day.
If you stay the course and keep contributing, time becomes your greatest asset.
General
⚖️ Neutral
🌐 Moneycrashers
#21728. Tech Report: Qapital Review – Worth the Fee Only If Its Rules Get You Saving
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (247 w)
Tech Report: Qapital Review – Worth the Fee Only If Its Rules Get You Saving
📅 16 Nov 2026 | ⏱️ 1 min read (247 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- According to recent reports, pay for Qapital only if you need its rules to save at all.
- According to recent reports, qapital is a savings app with three plans, none of them free.
- Qapital is worth its fee for savers who put money aside only when an app does it for them.
According to recent reports, pay for Qapital only if you need its rules to save at all. They move money into goals when you shop, get paid, or splurge, for $3 to $12 a month, but savings on the $3 Basic plan earn no interest. If a weekly transfer works for you, send it to a free high-yield account instead.
According to recent reports, qapital is a savings app with three plans, none of them free. The fee pays off only if its rules get you saving more than a free weekly transfer from checking would.
Qapital is worth its fee for savers who put money aside only when an app does it for them. Anyone who can keep up a weekly transfer does better in a high-yield savings account, where $1,000 at a 3.5% APY earns $35 a year while Qapital Basic pays no interest and charges $30 to $36.
Learn more about Qapital or see how it compares to the best round-up savings apps.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every firm or offer available in the marketplace.
🔗 Related Articles
📰 #21659. Ally Bank Spending Account Review – ATM Fee Refunds, but Cash Deposits Only at Walmart 📰 #19210. Tech Report: Hawaiian Airlines Mastercard review: Can be worth it even if you don't fly Hawaiian often 📰 #23674. Subway reveals Vice City sub for GTA 6, but there’s only one way to get it
General
⚖️ Neutral
🌐 Wellkeptwallet
#21727. Industry News: What Are Mutual Funds?
📅 27 May 2026 • ⏱️ 8m • 📚 Deep Dive (1648 w)
Industry News: What Are Mutual Funds?
📅 27 May 2026 | ⏱️ 8 min read (1648 words, 📚 Deep Dive) | Source: Wellkeptwallet
⏱️ ~8 mins left to finish
📖 0% read
💡 Key Takeaways
- Industry observers note that if you have ever looked at your 401(k) options or browsed a brokerage account, you have almost certainly seen mutual funds on the list.
- This article breaks down what mutual funds are, how they work, the different types you will encounter, and what to watch out for when deciding whether one belongs in your portfolio.
- In a recent development, A mutual fund is a pooled investment vehicle.
Industry observers note that if you have ever looked at your 401(k) options or browsed a brokerage account, you have almost certainly seen mutual funds on the list. They are one of the most widely used investment vehicles in the country, and for good reason. But not all mutual funds are built the same, and understanding the differences can have a real impact on how much money you actually keep over time.
This article breaks down what mutual funds are, how they work, the different types you will encounter, and what to watch out for when deciding whether one belongs in your portfolio.
In a recent development, A mutual fund is a pooled investment vehicle. When you invest in a mutual fund, your money is combined with money from thousands of other investors. A fund manager then uses that pool of capital to buy a collection of assets, which might include stocks, bonds, or a mix of both, depending on the fund’s objective.
Each investor owns shares of the mutual fund, and those shares represent a proportional stake in everything the fund holds. When the underlying assets increase in value, your shares go up. When they fall, your shares go down.
Industry observers note that mutual funds are priced once per day, after the market closes, based on the total value of all the assets inside the fund. This is called the net asset value, or NAV. Unlike stocks, which trade throughout the day at constantly changing prices, mutual fund transactions are always settled at the end-of-day price.
When you buy shares of a mutual fund, you are not picking individual stocks or bonds yourself. Instead, you are hiring a fund manager, or a team of them, to make those decisions on your behalf. The fund follows a stated investment objective, and the manager selects holdings that align with that goal.
According to recent reports, for example, a fund that aims for long-term growth might hold primarily large-cap U.S. stocks. A fund focused on income might hold a mix of dividend-paying stocks and bonds. The fund’s prospectus, a document you can access before investing, spells out exactly what the fund is trying to do and how it aims to do it.
According to recent reports, investors buy and sell mutual fund shares directly through the fund company or through a brokerage account. You can invest a specific dollar amount rather than buying a whole number of shares, making them accessible to investors at just about any level.
There are thousands of mutual funds available, but most fall into a handful of broad categories.
Recent findings suggest that these funds invest primarily in stocks. They can be further broken down by the size of the companies they hold (large-cap, mid-cap, small-cap), the style of investing (growth vs. value), or the geography (U.S. only, international, or global). Stock funds carry more risk than bond funds but also offer greater long-term growth potential.
Bond funds (fixed income funds).
Recent findings suggest that bond funds hold debt securities issued by governments, corporations, or municipalities. They are generally considered less volatile than stock funds and are often used to add stability to a portfolio. However, they also tend to produce lower returns over long periods.
These funds hold a combination of stocks and bonds within a single fund. The allocation varies by fund, but the idea is to provide both growth and income while smoothing out some of the volatility of a pure stock fund.
Money market funds invest in short-term, low-risk debt instruments. They aim to maintain a stable value and are often used as a place to park cash. The returns are modest, and they are not a long-term wealth-building strategy.
Index funds are a specific type of mutual fund that tracks a market index, such as the S&P 500, rather than relying on active stock picking. Because they are passively managed, they tend to have much lower fees than other types of mutual funds. Over the long run, they have consistently outperformed most actively managed alternatives after costs are taken into account.
This distinction is one of the most notable things to understand about mutual funds, and it directly affects your returns.
An actively managed fund employs a portfolio manager who researches investments, makes judgment calls, and trades frequently to outperform the market. This sounds appealing. Who would not want a professional trying to beat the market on their behalf?
The problem is that most actively managed funds do not beat the market over the long run, especially after fees are factored in. Study after study over multiple decades has shown that the majority of active fund managers underperform a simple index fund over a ten-year period. Yet they charge significantly more for the attempt.
A passively managed fund, like an index fund, does not try to beat the market. It simply tracks it. The holdings change only when the underlying index changes. Because no active management is required, the fees are a fraction of those charged by actively managed funds.
Sources indicate that for most long-term investors, a low-cost index fund is the better choice. The math is straightforward: lower fees mean more of your return stays in your pocket, and that difference compounds significantly over decades.
Fees are one of the most overlooked factors in investing, and they deserve your full attention. Here are the main ones to know.
The expense ratio is the annual cost of owning a fund, expressed as a percentage of your investment. A fund with a 1.00% expense ratio costs you $10 per year for every $1,000 you have invested. That may sound small, but over 30 years of investing, that difference compared to a fund charging 0.05% can amount to tens of thousands of dollars.
Recent findings suggest that some mutual funds charge a sales commission, called a load, either when you buy (front-end load) or when you sell (back-end load). A front-end load of 5% means that only $950 of every $1,000 you invest actually goes into the fund. There is no reason to pay a sales load when thousands of excellent no-load funds are available.
Recent findings suggest that these are marketing and distribution fees charged by some funds. They are baked into the expense ratio and can add up. A fund with a high 12b-1 fee is often a sign that the fund is spending money on sales and marketing rather than managing your investment.
In a recent development, when you invest in a mutual fund, you immediately own a small piece of every asset the fund holds. A single investment gives you exposure to hundreds or even thousands of companies, which spreads your risk far more effectively than buying individual stocks ever could.
For investors who do not want to research individual securities, mutual funds hand the decision-making over to professionals. This is especially relevant for bond funds and specialty funds, where the research involved is more complex than evaluating stocks.
It has been revealed that most mutual funds have low minimum investment requirements, and many allow you to invest in dollar amounts rather than whole shares. This makes them a practical option for investors who are just getting started or working with a limited budget.
Mutual funds in the United States are regulated by the Securities and Exchange Commission. Fund companies are required to disclose their holdings, fees, and performance data regularly. That transparency makes it relatively easy to compare options and know exactly what you are getting into.
Fees can erode your returns significantly.
This is the biggest issue with many mutual funds, particularly actively managed ones. High expense ratios and sales loads reduce your effective return every single year. Over a long investing horizon, that drag is substantial. Always check the expense ratio before investing in any fund.
According to recent reports, because mutual funds are priced once daily at market close, you cannot buy or sell during trading hours at a live price. For long-term investors, this is rarely a concern. But it is worth understanding how mutual funds differ from ETFs in this regard.
When a mutual fund sells holdings at a profit, it distributes those capital gains to shareholders at the end of the year. Even if you did not sell any of your own shares, you may owe taxes on those distributions. This is less of an issue in tax-advantaged accounts like a 401(k) or IRA, but it is something to keep in mind for taxable brokerage accounts.
It is possible to hold too many mutual funds that overlap in their holdings, leaving you with a bloated, redundant portfolio. Owning five different large-cap U.S. stock funds does not give you five times the diversification. It mostly just gives you five sets of fees.
According to recent reports, with thousands of mutual funds available, narrowing down your options does not have to be complicated. A few straightforward criteria will get you most of the way there.
Recent findings suggest that mutual funds are among the most practical investments available to everyday investors. They make it easy to build a diversified portfolio without needing to research and manage individual securities. For most people, the primary vehicle for building wealth over time is a 401(k), IRA, or taxable brokerage account.
Recent findings suggest that that stated, not all mutual funds are worth your money. Actively managed funds and those with high sales loads or steep expense ratios consistently underperform lower-cost alternatives over the long run. The evidence strongly favors low-cost index funds as the core of most investors’ portfolios.
The most notable step is to start. Aim to invest at least 10% of your gross income consistently, keep your costs low, stay diversified, and give your money time to grow. The mechanics of which specific funds you choose matter far less than the discipline of contributing regularly over many years.
🔗 Related Articles
📰 #15846. Industry News: SEC Proposes Expanding Securities Eligible for Cross Trading by Registered Funds 📰 #23683. Industry News: Microsoft 365 outage leads to chlorine gas poisoning of 15 hotel guests 📰 #23652. Industry News: Overlocker uses vibecoded BIOS modification to target Intel's non-K overclocking restrictions
Business & Policy
⚖️ Neutral
🌐 Moneycrashers
#21726. Seeking Alpha Review – Quant Ratings & Crowd Research Built for Stock Pickers
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (185 w)
Seeking Alpha Review – Quant Ratings & Crowd Research Built for Stock Pickers
📅 16 Nov 2026 | ⏱️ 1 min read (185 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- A free Basic account gets you market news, portfolio tracking, price alerts, and one Premium article a month, enough to try the format.
- Industry observers note that investors who research individual stocks every week, and would otherwise piece together filings, transcripts, and opinions themselves, get the most out of the $299.
- Learn more about Seeking Alpha or see how it compares to the best stock research websites.
A free Basic account gets you market news, portfolio tracking, price alerts, and one Premium article a month, enough to try the format. Premium, the flagship paid plan, is built for investors who study individual companies before they buy.
Industry observers note that investors who research individual stocks every week, and would otherwise piece together filings, transcripts, and opinions themselves, get the most out of the $299. Index fund investors should skip it and stick with their funds, which need no stock research.
Learn more about Seeking Alpha or see how it compares to the best stock research websites.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
In a recent development, advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every tech giant or offer available in the marketplace.
General
⚖️ Neutral
🌐 Moneycrashers
#21725. Breaking: Morningstar Investor Review – Worth It for DIY Fund Pickers
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (199 w)
Breaking: Morningstar Investor Review – Worth It for DIY Fund Pickers
📅 16 Nov 2026 | ⏱️ 1 min read (199 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Morningstar Investor, the paid membership for do-it-yourself investors, unlocks Morningstar’s fund and stock ratings, analyst reports, screener, and portfolio tools.
- Investors who pick their own funds across two or more accounts get the most from Morningstar Investor, since its portfolio tools show the combined fees and overlap that separate statements hide.
- Learn more about Morningstar Investor or see how it compares to the best stock research websites.
Morningstar Investor, the paid membership for do-it-yourself investors, unlocks Morningstar’s fund and stock ratings, analyst reports, screener, and portfolio tools. Without it, the free quote pages still show what a fund charges each year, its expense ratio, but none of the ratings or full analyst reports.
Investors who pick their own funds across two or more accounts get the most from Morningstar Investor, since its portfolio tools show the combined fees and overlap that separate statements hide. Savers with everything in a single target-date fund already own a diversified mix that rebalances itself, so they can keep the $249.
Learn more about Morningstar Investor or see how it compares to the best stock research websites.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Sources indicate that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.
General
⚖️ Neutral
🌐 Wellkeptwallet
#21724. What Are Target Date Funds?
📅 27 May 2026 • ⏱️ 6m • 📚 Deep Dive (1220 w)
What Are Target Date Funds?
📅 27 May 2026 | ⏱️ 6 min read (1220 words, 📚 Deep Dive) | Source: Wellkeptwallet
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- In this article, we will break down what target date funds are, how they work, what they cost, and why a low-cost index fund strategy may serve most investors better in the long run.
- A target-date fund is a type of mutual fund designed to serve as a single, all-in-one retirement investment.
- According to recent reports, the fund holds a mix of stocks and bonds, and that mix automatically shifts over time as your target date gets closer.
In this article, we will break down what target date funds are, how they work, what they cost, and why a low-cost index fund strategy may serve most investors better in the long run.
A target-date fund is a type of mutual fund designed to serve as a single, all-in-one retirement investment. You pick the fund that most closely matches the year you strategy to retire, and the fund handles everything else. If you plan to retire around 2050, for example, you would choose a fund labeled something like “2050 Retirement Fund” or “Target Date 2050.”.
According to recent reports, the fund holds a mix of stocks and bonds, and that mix automatically shifts over time as your target date gets closer. Early on, the fund is weighted heavily toward growth stocks. As retirement approaches, the portfolio gradually shifts toward bonds and more conservative holdings to reduce risk.
The appeal is obvious. You make one decision, contribute regularly, and the fund adjusts itself. For people who want to set it and forget it, that sounds like a dream. But there is more to the story.
Target date funds are known as “fund of funds.” Rather than holding individual stocks or bonds directly, they hold a collection of other mutual funds, typically a mix of domestic stock, international stock, and bond funds.
The fund manager adjusts the allocation over time according to a schedule called a glide path. When you are decades away from retirement, the fund might hold 90% stocks and 10% bonds. As you get closer to your target year, that ratio shifts until the fund is much more conservative, sometimes holding more bonds than stocks by the time you retire.
The glide path is simply the schedule that determines how the fund’s asset allocation changes over time. Think of it as the fund’s long-term blueprint for gradually reducing risk.
Recent findings suggest that different fund providers use different glide paths, and this matters more than most people realize. Some funds are more aggressive early on and pull back dramatically as retirement nears. Others maintain a higher stock allocation even into and through retirement, which some financial planners argue is actually smarter given how long retirement can last.
The vital thing to understand is that the glide path is not customized for you. It is a one-size-fits-all formula based on your expected retirement year, nothing more. Your actual risk tolerance, health, spending plans, and other income sources are not factored in at all.
The biggest selling point is that target date funds require almost no ongoing attention. You pick one fund, contribute regularly, and walk away. For someone who has no interest in managing their investments, that convenience is genuinely valuable.
According to recent reports, because target date funds hold a mix of stock and bond funds, you get broad diversification across asset classes in a single investment. You are not putting all your money into a single sector or organization.
Recent findings suggest that over time, a portfolio can drift away from its intended allocation as different assets grow at different rates. Target date funds handle this automatically, which is one less thing you have to manage yourself.
Target date funds are not without their drawbacks, and for many investors, those drawbacks are significant enough to look for a better option.
Recent findings suggest that because target date funds are funds of funds, they often carry two layers of fees: the expense ratio of the target date fund itself and the underlying expense ratios of the funds it holds. Even a seemingly small difference in fees can cost you tens of thousands of dollars over a long investing career. Low-cost index funds, by comparison, often charge a fraction of what target date funds do.
Sources indicate that the glide path in a target-date fund is designed for the average investor retiring in a given year. But your situation is not average. You might have a pension, a working spouse, rental income, or a much higher risk tolerance than the fund assumes. None of that is reflected in how the fund manages your money.
When you hand everything over to a target date fund, you give up control over your allocation. If the fund has a heavy position in international stocks or bonds that you would rather avoid, there is not much you can do about it while staying in the fund.
Variable quality across providers.
Sources indicate that not all target date funds are created equal. The same target year fund from two different providers can have very different allocations, fee structures, and underlying holdings. Without digging into the details, it is easy to end up in a fund that does not match your actual needs.
This is where the comparison gets crucial. A target date fund is actively managed in the sense that a team of people decides how to allocate and rebalance it over time. An index fund, on the other hand, simply tracks a market index like the S&P 500. There is no active management involved, which is exactly why the fees are so much lower.
It has been revealed that decades of research consistently show that most actively managed funds underperform their benchmark index after fees. Target date funds are not immune to this problem. When you account for layered costs, many target-date funds trail what you would earn by simply holding a low-cost index fund over the same period.
A simple alternative that many investors use is called a three-fund portfolio: a U.S. total market index fund, an international index fund, and a bond index fund. You set your own allocation based on your age and risk tolerance, rebalance once a year, and pay minimal fees. It takes about 30 minutes a year to manage.
Sources indicate that this approach gives you the same diversification as a target-date fund, with far more control and significantly lower costs. And as a general rule, the more of your return you keep rather than paying in fees, the better off you will be over time.
Target date funds are not the right choice for every investor, but there are situations where they make sense.
Sources indicate that even in these cases, it is worth checking the expense ratio. If your initiative offers a target-date fund with an expense ratio above 0.50%, consider whether there are lower-cost index fund options within the same plan.
It has been revealed that target date funds solve a real problem: they make it easy for people who do not want to think about investing to still participate in the market. That convenience has real value.
In a recent development, but for investors who are willing to learn even a little bit about how to manage their own allocation, a portfolio of low-cost index funds will almost always be the better long-term choice. The fees are lower, the control is greater, and the returns tend to be better over time.
If you are at the moment in a target date fund, that is not necessarily a problem. But it is worth understanding what you are paying and whether a simpler, lower-cost approach might serve you better. Investing at least 10% of your gross income is the priority. Where exactly that money goes is the next question worth asking.
General
⚖️ Neutral
🌐 Goodfinancialcents
#21723. Bitcoin Historical Annual Returns (10 Years, 5 Years, 3 Years, 1 Year)
📅 14 Aug 2023 • ⏱️ 8m • 📚 Deep Dive (1536 w)
Bitcoin Historical Annual Returns (10 Years, 5 Years, 3 Years, 1 Year)
📅 14 Aug 2023 | ⏱️ 8 min read (1536 words, 📚 Deep Dive) | Source: Goodfinancialcents
⏱️ ~8 mins left to finish
📖 0% read
💡 Key Takeaways
- Home » Invest » Bitcoin Historical Annual Returns (10 Years, 5 Years, 3 Years, 1 Year).
- It has been revealed that explore Bitcoin's fascinating journey from its inception to its recent highs and learn about its impressive historical returns.
- Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
Home » Invest » Bitcoin Historical Annual Returns (10 Years, 5 Years, 3 Years, 1 Year).
It has been revealed that explore Bitcoin's fascinating journey from its inception to its recent highs and learn about its impressive historical returns. Whether you're a seasoned investor or new to cryptocurrency, this article provides insights into Bitcoin's milestones and how it stacks up against other asset classes.
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
The GFC® Money Expert Review Board.
The GFC® Money Expert Review Board is a team of financial experts who provide independent, unbiased reviews of financial products...
Sources indicate that goodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
Industry observers note that goodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The New York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Latest York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
From its humble beginnings in 2008 to today, Bitcoin’s history has been relatively short but very eventful. The original protocol for this popular digital currency was created in 2008 by Satoshi Nakamoto, believed to be a pseudonym for an unknown developer or group of developers.
Nakamoto released the Bitcoin network just a year later and began mining the currency— an estimated 1 million bitcoins were mined in the early years.
The creator(s) of this first-of-its-kind asset developed the cryptocurrency in response to the Great Recession of 2007-2009, spurred by a distrust of the traditional banking system and concerns about its stability.
Industry observers note that given the recent values of Bitcoin, it’s hard to believe the currency first started trading on exchanges in 2010 at under $0.10. Since then, it’s experienced astronomical growth and some pretty wild price swings.
At its most recent high, one bitcoin was worth over $64,000—a far cry from trading for pennies in its earliest days.
Whether you’re thinking of investing in Bitcoin or you’ve held this cryptocurrency for several years, it’s fun to look back at this groundbreaking asset’s history. Read on for insights on Bitcoin milestones, historical returns, and how its returns compare to those of other assets.
Since being created, Bitcoin has experienced several milestones. Here’s a look back at some of the most significant moments in the short history of this cryptocurrency:.
While Bitcoin isn’t exempt from the volatility cryptocurrencies often experience, it’s delivered some impressive returns over the years. Here’s a look at Bitcoin’s annual returns from 2010 to 2022:.
And here’s a look at monthly returns, if you feel like getting a deeper dive:.
It has been revealed that while Bitcoin has experienced some wild monthly price swings and a couple of years where its value has declined, you can see that its declines have been eclipsed by some incredible gains. Now let’s explore how Bitcoin’s value has changed over 10, 5, 3, and 1 years.
Let’s say you bought one bitcoin on August, 3rd 2013, for $1,106.75, its price at the time. If you held that one bitcoin until August 3rd, 2023, it would’ve been worth $29,310.44, and your total ROI for the 10 years would be 2,546.8%.
We’ll also assume you purchased one Bitcoin for this example. A single bitcoin was valued at $965.31 on August, 3rd, 2018, and its value climbed to $29,310.44 by August 2023. Using our calculation above, your total ROI for those five years would be 294.1%.
It has been revealed that A single bitcoin was valued at $11,246.20 in August 2020, and its value climbed to $29,310.44 at the end of 2021. Your total ROI for those three years would be 160.6%.
If you purchased a single bitcoin in August 2022, you would’ve paid around $22,626.83. In one year, that value would’ve increased to $29,310.44. Your total returns for that year would be 29.54%.
Instead of buying one bitcoin, let’s say you decided to invest $1,000 into Bitcoin. Here’s a look at how this $1,000 investment would’ve performed if you bought and held your Bitcoin for 10, 5, 3, and 1 years.
While Bitcoin’s earliest investors would have benefitted the most from buying and holding their Bitcoin, those who’ve invested recently also fared well.
If you’re curious how Bitcoin returns compare to those of other asset classes, here’s how its annual and total returns compare to gold, real estate, and the S&P 500.(Spoiler alert: Bitcoin outperformed all three assets by an enormous margin.).
If you compare Bitcoin’s returns to gold’s returns, you’ll notice a stark difference. Bitcoin has an average annual return of 1,576% and a total return of 18,912% from 2010 to 2022, while SPDR Gold Shares had an average annual return of just 5.14% and a total return of 61.67% over the same period.
In a recent development, let’s see if real estate fared any better compared to Bitcoin. The cryptocurrency delivered a whopping 1,576% average annual return and an 18,912% total return from 2010 to 2021, while the Vanguard Real Estate ETF had an average annual return of 13.49% and a total return of 161.91% over the same period.
So, real estate saw slightly higher returns than gold, but it still didn’t come close to Bitcoin’s returns.
The S&P 500 didn’t fare too much better in its head-to-head with Bitcoin. From 2011 to 2023, the Vanguard S&P 500 ETF delivered an average annual return of 15.74% and a total return of 173.14%. While those numbers aren’t too shabby, Bitcoin’s average annual return for the same period was a whopping 819%, and its total return was 9,012%.
Industry observers note that we’ve analyzed how Bitcoin compares to gold, real estate, and the stock market, but how does it stack up against some of the best-performing stocks? Here’s how this popular cryptocurrency stacks up against major companies like Amazon, Apple, Berkshire Hathaway, JP Morgan, Microsoft, Visa, and Walmart.
We looked at the average annual and total returns for each asset. This data assumes you bought the asset in 2010 and held it until 2023.
Industry observers note that while some investors may be skeptical about cryptocurrency, citing concerns over market volatility and a high risk of loss, Bitcoin’s performance over time paints a rosy picture. With its longevity and astronomically high returns, Bitcoin has been worth the risk for many investors—especially early adopters.
Of course, historical performance doesn’t guarantee future returns. So if you’re considering investing in cryptocurrency, only invest what you can afford to lose.
In a recent development, marketWatch (2021, May 22) Bitcoin pizza day? Laszlo Hanyecz spent $3.8 billion on pizzas in the summer of 2010 using the novel crypto https://www.marketwatch.com/story/bitcoin-pizza-day-laszlo-hanyecz-spent-3-8-billion-on-pizzas-in-the-summer-of-2010-using-the-novel-crypto-11621714395.
The Guardian (2021, Nov 9) Bitcoin price surges to record high of more than $68,000 https://www.theguardian.com/technology/2021/nov/09/bitcoin-price-record-high-cryptocurrencies-ethereum.
Vanguard Personal Investors (n.d.) VOO Vanguard S&P 500 ETF https://investor.vanguard.com/investment-products/etfs/profile/voo.
Federal Reserve History (2013, Nov 22) The Great Recession https://www.federalreservehistory.org/essays/great-recession-of-200709#.
USSC.gov (2018) Bitcoin: A Peer-to-Peer Electronic Cash System https://www.ussc.gov/sites/default/files/pdf/training/annual-national-training-seminar/2018/Emerging_Tech_Bitcoin_Crypto.pdf.
Vanguard Personal Investors (n.d.) VNQ Vanguard Real Estate ETF https://investor.vanguard.com/investment-products/etfs/profile/vnq#performance-fees.
SPDR Gold Shares (n.d.) Welcome to SPDR Gold Shares https://www.spdrgoldshares.com/usa/.
Sources indicate that jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance book Soldier of Finance. He was a financial planner for 16+ years having founded, Alliance Wealth Management, a SEC Registered Investment Advisory firm, before selling it to focus on his passion - educating the masses on the importance of financial freedom through this blog, his podcast, and YouTube channel. Jeff holds a Bachelors in Science in Finance and minor in Accounting from Southern Illinois University - Carbondale. In addition to his CFP® designation, he also earned the marks of AAMS® - Accredited Asset Management Specialist - and CRPC® - Chartered Retirement Planning Counselor. While a practicing financial advisor, Jeff was named to Investopedia's distinguished list of Top 100 advisors (as high as #6) multiple times and CNBC's Digital Advisory Council. Jeff is an Iraqi combat veteran and served 9 years in the Army National Guard. His work is regularly featured in Forbes, Business Insider, Inc.com and Entrepreneur.
🔗 Related Articles
📰 #22402. After a year off, the ADAA's New York fair returns with a new name and revamped layout 📰 #21130. Annual Cat Writers’ Association Conference: The Cat Event of the Year Is Coming to Dallas–Fort Worth 📰 #19350. Industry News: Huckberry's Annual Cyber Week Sale Is Its Biggest of the Year—Save Over 60% on Editor-Approved Gear and Outerwear
General
⚖️ Neutral
🌐 Choosefi
#21722. Aeroplan Stopovers — Two Cities for the Price of One
📅 04 Nov 2026 • ⏱️ 14m • 📚 Deep Dive (2895 w)
Aeroplan Stopovers — Two Cities for the Price of One
📅 04 Nov 2026 | ⏱️ 14 min read (2895 words, 📚 Deep Dive) | Source: Choosefi
⏱️ ~14 mins left to finish
📖 0% read
💡 Key Takeaways
- Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
- One of the highest-value redemptions in travel rewards.
- According to recent reports, picture this: you're settling into a lie-flat business class seat somewhere over the Atlantic, a glass of something cold in hand, knowing that in 48 hours you'll be waking up in Istanbul — and then, a few days later, continuing onward to Bangkok.
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
One of the highest-value redemptions in travel rewards.
According to recent reports, picture this: you're settling into a lie-flat business class seat somewhere over the Atlantic, a glass of something cold in hand, knowing that in 48 hours you'll be waking up in Istanbul — and then, a few days later, continuing onward to Bangkok. Two bucket-list cities. One award booking. One points balance. This is what the Aeroplan stopover sweet spot feels like in practice. It's not a trick or a loophole — it's a deliberately designed feature of Air Canada's Aeroplan program that the vast majority of travelers simply don't know exists. And that gap between awareness and reality is exactly where the ChooseFI community finds its edge. Here's the math that should make your jaw drop. A business class itinerary from North America to Istanbul with a continuing flight onward to Bangkok — two long-haul segments, lie-flat seats, Star Alliance lounges at every connection — would cost somewhere between **$6,000 and $15,000 in cash**. That's a realistic retail range depending on season and how far out you book. Most people never consider it a possibility for a family vacation or a milestone trip because the sticker price puts it in a different universe. With Aeroplan, you're booking that same itinerary — the same seats, the same lounges, the same Turkish Airlines or Thai Airways product — for **75,000 Aeroplan points**. At the low end of the cash price range, that's already **8 cents per point**. At the high end, you're extracting **20 cents per point** from a currency that most people earned by putting groceries on a credit card. The pricing inefficiency here is structural. Aeroplan's partner award chart prices long-haul business class at a fixed rate regardless of cash fare fluctuations. When business class prices spike — around holidays, during peak travel seasons, during major events — your points cost stays exactly the same. You're insulated from the market. That's the FI mindset applied to travel: you've already paid for the trip in points, slowly accumulated through everyday spending, and now you're simply redeeming the stored value. The stopover itself is nearly free. Aeroplan charges just 5,000 extra miles to add a stopover city to a one-way award. That means your Istanbul layover becomes a multi-day stay — at zero additional points cost beyond that small add-on — and you haven't booked a second award at all. One booking. Two destinations. That's the entire premise, and once you see it, you can't unsee it.
The mechanism behind this sweet spot is elegantly simple once you understand it, but it requires knowing three things that most travelers don't: how Aeroplan's routing rules work, what a stopover actually is in the context of an award ticket, and why Star Alliance's global network makes this scalable to almost any destination pair you can imagine.
Sources indicate that when Aeroplan relaunched its loyalty program in 2020, it did something remarkable: it eliminated fuel surcharges entirely and published a partner award chart with fixed pricing for flights on Star Alliance carriers. This is critical. When you book Turkish Airlines business class through Aeroplan, you pay the Aeroplan fixed chart rate — not what Turkish Airlines would charge in its own currency or miles program, and not the inflated cash price. That fixed chart is the engine of this redemption.
Recent findings suggest that for long-haul international business class, Aeroplan's chart prices routing through multiple regions based on your origin and destination — not every intermediate stop. This is the aha moment. Aeroplan determines your award price based on where your journey starts and where it ends, and then allows you to add a stopover in between for just 5,000 additional miles. The stopover city is priced as a pass-through for the purpose of calculating your award zone, not as a second trip.
According to recent reports, on a one-way Aeroplan award, you're permitted to add a free stopover — meaning you can stay in an intermediate city for any length of time before continuing to your final destination. That 5,000-mile add-on is essentially the cost of a full additional destination. Compare that to booking a second one-way award from Istanbul to Bangkok, which would cost you another 40,000–55,000 Aeroplan points in business class. The math is decisive.
It has been revealed that the routing must be geographically sensible — you can't fly backwards across the globe — but Aeroplan's allowance for multi-segment itineraries through Star Alliance hubs gives you enormous flexibility. Istanbul (IST) is a Turkish Airlines hub. Bangkok (BKK) is served by Thai Airways and several Star Alliance carriers. Both are Star Alliance partners. Both are bookable through Aeroplan at fixed chart rates with no fuel surcharges.
The best part for the ChooseFI community is how accessible the underlying points are. Aeroplan accepts transfers from four major programs:.
It has been revealed that chase's instant transfer speed is particularly valuable here. When you find business class availability — which can disappear promptly — you want to move points immediately. Having Chase Ultimate Rewards as your primary earning currency means you can search, find space, and transfer points before the availability window closes. The 1:1 ratio across all four programs means no conversion math — every point you earn translates directly to one Aeroplan mile.
Free calculator indicates when you could reach financial independence — plus a savings rate tracker, expense audit, and more.
Booking an Aeroplan stopover award in business class is genuinely one of the more complex redemptions in the travel rewards world, but it becomes manageable when you break it into distinct phases. Here's exactly how to do it.
According to recent reports, start by deciding on your two destinations. Aeroplan stopovers work best when your intermediate city is a major Star Alliance hub that lies geographically between your origin and final destination. Classic combinations include North America to Istanbul (Turkish Airlines hub) continuing to Southeast Asia, or North America to a European hub continuing to the Middle East or East Africa. Your stopover city should be somewhere you genuinely want to spend 2–5 days — this is a real trip, not just a layover.
This is the most notable and most time-consuming step. You need to find saver-level business class availability on both segments independently before you book.
Once you've confirmed availability on both segments, go to aeroplan.com and use the multi-city search function. Enter your full itinerary — origin, stopover city with your intended layover dates, and final destination.
Once you've confirmed the award is bookable and are ready to complete the reservation:.
Complete your booking on aeroplan.com or with a phone agent, confirm the stopover is properly reflected in your itinerary, and save every confirmation email. Verify your seats on each carrier's website immediately after booking.
A stopover is an intentional break in your journey lasting more than 24 hours at a connecting city. Most airlines treat stopovers as separate tickets, charging full price for each segment. Aeroplan is one of the few programs that allows a free stopover on round-trip awards, letting you explore a connecting city for days before continuing to your final destination. This is fundamentally different from a layover, which is a brief connection of a few hours at an airport. The stopover must be in a city served by a Star Alliance carrier on your routing, and the key is that Aeroplan prices the entire itinerary as one award, not two.
Card links may earn ChooseFI a commission. See our advertiser disclosure.
Ready to unlock a world of free travel? Start with the Chase Sapphire Preferred® Card.
$95 annual fee | Earn 75,000 bonus points.
Recent findings suggest that side hustlers! With the Ink Business Preferred® Credit Card you can earn free travel from your business expenses.
$95 annual fee | Earn 100,000 bonus points.
The Capital One Venture Rewards Credit Card can be used to offset almost any travel expense.
$95 annual fee | Earn more than $1,000 in Travel Bonuses with a limited-time $300 Capital One Travel stays credit, plus earn 75,000 bonus miles once you spend $4,000 on purchases within the first 3 months of account opening—that's more than $1,000 in travel value.
Sources indicate that chooseFI has partnered with CardRatings for our coverage of credit card products. ChooseFI and CardRatings may receive a commission from card issuers.
Let's build a real example so you can see exactly what this looks like on paper — and in the air.
The Route: Toronto (YYZ) → Istanbul (IST, 4-day stopover) → Bangkok (BKK) The Carrier: Turkish Airlines business class on both segments The Points Cost: 75,000 Aeroplan miles for the two segments + 5,000 miles for the stopover = 80,000 Aeroplan miles total Cash Equivalent: A comparable business class itinerary on this routing typically retails for $9,000–$12,000 in 2026, depending on when you search and how far in advance you book.
The CPP Calculation: At the midpoint cash value of $10,500 against 80,000 points, you're extracting 13.1 cents per Aeroplan mile — well inside the 8–20 cent range this sweet spot delivers, and roughly 10–13 times the value of redeeming Aeroplan miles for cash back.
Industry observers note that the Turkish Airlines business class product on long-haul routes is consistently rated among the top business class experiences in the Star Alliance network. On the YYZ–IST segment — operated on a 787 or A330 — you'll have access to a lie-flat seat with direct aisle access, the Turkish Airlines Lounge in Istanbul (widely considered one of the best airport lounges in the world, full stop), and a meal service that reflects the airline's culinary reputation. The IST lounge alone — with its restaurant, spa, golf simulator, and sleeping areas — is worth lingering in even before your onward connection.
In Istanbul, your four days might include the Hagia Sophia at sunrise, a Bosphorus dinner cruise, and the Grand Bazaar before you head to the airport to continue your journey. You've paid nothing additional for this stay beyond the 5,000-mile stopover fee.
The IST–BKK segment puts you into Bangkok in the evening, ready for Thailand's extraordinary food, culture, and cost of living — which, for the FI-minded traveler, means your lodging and meals on the ground are remarkably affordable, stretching the value of your trip even further.
Total points cost for two lie-flat business class segments and a full European city stay: 80,000 miles, earned on everyday credit card spending. That's the entire proposition, and those numbers are real.
Book at exactly 355 days out. Aeroplan opens its booking window at 355 days before departure. The best business class availability on popular routes — especially Turkish Airlines long-haul — appears at this window and gets claimed rapidly. Set a calendar reminder and be ready to search at the 355-day mark for your target travel dates.
Use Chase Ultimate Rewards as your primary earning currency for this redemption. The instant transfer speed to Aeroplan is genuinely differentiating. When you find award space and need to move swiftly, Chase lets you transfer and book in the same session. Amex, Capital One, and Bilt all require 1–2 days, during which your availability can evaporate.
Sources indicate that search availability before you transfer points. Confirm space exists on every segment before a single point moves. There's no undo button on a transfer, and Aeroplan points sitting idle in your account are fine — points transferred to an account where you can't find availability are a headache.
Call Aeroplan for complex routings. The online multi-city tool is functional but can struggle with nuanced stopover configurations. Phone agents are experienced with these bookings and have the same access to inventory. The call is worth it for an $80,000-point booking.
Leverage the open-jaw rule too. Aeroplan also allows open-jaw routing — fly into one city, depart from another. Combined with the stopover, you can design a route that visits three geographic points on a single award: fly into Istanbul, take trains or ferries to Athens, and fly home from Athens. The award prices the same way.
Don't assume partner availability matches Aeroplan's search. Turkish Airlines and other Star Alliance partners don't always make every seat available through Aeroplan's online portal. If you see space on the carrier's own site but not on aeroplan.com, call — agents can often access inventory the website misses.
According to recent reports, don't book inflexible connecting flights. Long-haul itineraries with tight connections are a risk. Build in at least a 3-hour connection at hub airports to protect against irregular operations that could affect your award segments.
According to recent reports, don't earn Marriott Bonvoy points with this redemption in mind. The 3:1 transfer ratio to Aeroplan makes Marriott a poor choice for funding this specific award. Stick to Amex, Chase, Capital One, or Bilt at 1:1.
According to recent reports, don't book this for a time-sensitive trip. Award availability, transfer timelines, and multi-carrier coordination mean this requires planning runway. Build in at least 3–4 weeks of lead time beyond the actual booking date.
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
This redemption is purpose-built for the advanced travel rewards enthusiast in the ChooseFI community — someone who has already mastered the basics (earning transferable points, understanding award charts, booking straightforward partner awards) and is ready to unlock the next level of value.
The ideal profile: A couple or solo traveler planning a milestone trip — a significant anniversary, a sabbatical, a once-in-a-decade adventure — who wants to experience two destinations in business class without paying business class prices for either one. You're flexible on travel dates, comfortable spending time on the phone with an airline agent, and genuinely excited about the trip-planning process as part of the experience.
According to recent reports, minimum points balance: You'll need approximately 80,000 Aeroplan miles to complete this booking (75,000 for the award plus 5,000 for the stopover). That's achievable from a single premium credit card welcome bonus, a combination of two or three mid-tier welcome bonuses, or 12–18 months of everyday spending on a 2x transferable points card.
This is NOT the right redemption for:.
For the ChooseFI traveler who's been building transferable points for a year or two and wants to see what this system is truly capable of, this redemption is the answer.
It has been revealed that pick a final destination and a stopover city on the same Star Alliance routing. Classic combos: Istanbul + Bangkok, Zurich + Tokyo, Vienna + Singapore. The stopover city must be a natural connection point on a Star Alliance route between your origin and destination.
Recent findings suggest that set a calendar alert for 355 days before your departure date. Search for business class availability on each segment separately using United.com or Aeroplan.com. Both legs need saver-level award space on the same booking.
Industry observers note that before transferring any points, verify that saver award space exists on both the outbound leg (origin to stopover city) and the continuation (stopover city to final destination). If either segment is unavailable, the booking will not work.
Transfer Chase Ultimate Rewards (instant) or Amex Membership Rewards (1-2 days) to your Aeroplan account at a 1:1 ratio. Only transfer once you have confirmed availability on both segments.
According to recent reports, call Aeroplan or use the multi-city search tool online. Specify your stopover city and duration (up to the maximum allowed). The system prices it as one round-trip award. Confirm total points match expectations before completing the booking.
Aeroplan allows stopovers of up to 45 days on round-trip awards. You can stay in your stopover city for a few days or several weeks, giving you genuine time to explore rather than just passing through.
No, stopovers are only available on round-trip awards through Aeroplan. One-way bookings do not qualify for the free stopover benefit. This is one reason round-trip awards can offer better value than two one-ways.
Aeroplan has improved its online multi-city search tool, and some stopover itineraries can now be booked online. However, complex routings may still require a phone call. When calling, clearly state you want a round-trip award with a stopover and specify your stopover city and dates.
According to recent reports, the best stopover cities are Star Alliance hub cities with strong business class availability: Istanbul (Turkish Airlines hub), Zurich (SWISS hub), Vienna (Austrian hub), Singapore (Singapore Airlines hub), and Tokyo (ANA hub). These hubs offer the most consistent saver-level award space.
Sources indicate that this sweet spot was last verified over 90 days ago. Award availability and pricing may have changed — verify current rates before booking.
According to recent reports, the Aeroplan stopover is one of the most powerful tools in the travel rewards playbook. By adding a free stopover to a round-trip business class award, you can explore two world-class cities for the points cost of visiting one. It requires planning, patience at the 355-day booking window, and comfort with Star Alliance routing rules, but the payoff is extraordinary: 10-15 cents per point in value on experiences that would cost thousands in cash. For the FI community member who has mastered basic award bookings and is ready to level up, this is the redemption that changes how you think about travel.
🔗 Related Articles
📰 #23425. Latest Update: Google’s latest ‘Fast Switch’ feature leaks, lets you use one number on two Android phones 📰 #22937. Latest Update: Building Permits API for 50 US Cities: Chicago Issued 599 Permits in One Week (Python + No-Code) 📰 #21962. Air Canada Aeroplan — Partner Awards with Stopovers
General
⚖️ Neutral
🌐 Wellkeptwallet
#21721. Industry News: Health Sharing vs. Traditional Health Insurance: Which Is Right for You?
📅 20 Sep 2026 • ⏱️ 3m • 📚 Deep Dive (685 w)
Industry News: Health Sharing vs. Traditional Health Insurance: Which Is Right for You?
📅 20 Sep 2026 | ⏱️ 3 min read (685 words, 📚 Deep Dive) | Source: Wellkeptwallet
⏱️ ~3 mins left to finish
📖 0% read
💡 Key Takeaways
- If your family’s ACA premium has jumped again this year, you’re not imagining it, and you’re not alone in looking at alternatives.
- A health sharing strategy (sometimes called a health care sharing ministry, or HCSM) is a nonprofit arrangement where members pay a monthly “contribution” that goes toward other members’ eligible medical bills, instead of a premium that goes to an insurance company.
- Recent findings suggest that tennessee’s Department of Commerce and Insurance is blunt: health care sharing ministries facilitate the sharing of medical expenses and are not insurance companies, and whether anyone helps with your bills is entirely voluntary rather than legally guaranteed.
If your family’s ACA premium has jumped again this year, you’re not imagining it, and you’re not alone in looking at alternatives. Health sharing prepares have moved from a faith-based niche into a mainstream budgeting conversation. But before you switch, it’s worth understanding exactly what you’re trading away, not just what you’re saving.
A health sharing strategy (sometimes called a health care sharing ministry, or HCSM) is a nonprofit arrangement where members pay a monthly “contribution” that goes toward other members’ eligible medical bills, instead of a premium that goes to an insurance company. There’s no insurance contract, and no company is legally on the hook to pay your claims.
Recent findings suggest that tennessee’s Department of Commerce and Insurance is blunt: health care sharing ministries facilitate the sharing of medical expenses and are not insurance companies, and whether anyone helps with your bills is entirely voluntary rather than legally guaranteed. Michigan’s insurance regulator adds that HCSMs aren’t classified as insurance because they don’t assume risk and have no legal obligation to pay members’ costs.
Example: Zion HealthShare is a modern health sharing community that markets itself as a lower-cost alternative to ACA aims, with no provider networks and members paying an “Initial Unshareable Amount” (their version of a deductible) before larger bills become eligible for sharing.
Read our review of Zion HealthShare.
It has been revealed that traditional health insurance is a regulated contract, an ACA marketplace plan, an employer plan, or a private major-medical policy. The insurer must pay covered claims, cover pre-existing conditions from day one, and include the ACA’s essential health benefits (preventive care, maternity, mental health, and more), a distinction healthinsurance.org explains in detail when comparing HCSMs with ACA-compliant coverage.
It has been revealed that solo Health is another option built for self-employed people. It’s a self-funded major medical health strategy with a nationwide PPO network, and it works differently from both health sharing and ACA Marketplace coverage. Eligibility is based on a short health questionnaire. Read our full Solo Health review.
Employer-sponsored family premiums averaged $26,993 in 2025, and many 2026 ACA marketplace aims are seeing median premium hikes of 18–20% as subsidies shrink and medical costs climb. By comparison, health sharing contributions often run $150–$400 per person per month, roughly 30–50% less.
But that gap exists because health sharing plans aren’t required to guarantee anything. Traditional insurers already deny 19–20% of claims on average (some carriers reportedly higher), so even “real” insurance isn’t friction-free, but at least it comes with legal appeal rights and state oversight. A health share’s review process is informal and ministry-specific, with no equivalent legal backstop if a bill gets rejected.
Industry observers note that it works best for generally healthy families who don’t qualify for meaningful ACA subsidies, are comfortable handling more paperwork and negotiating bills themselves, and want lower fixed monthly costs in exchange for taking on more risk. It’s a weaker fit for anyone managing a chronic condition, planning a pregnancy, or who needs the legal certainty of a regulated contract.
According to recent reports, health sharing can meaningfully lower your monthly healthcare costs, but the trade-off is real: you’re giving up the legal guarantee, essential-benefit mandates, and regulatory protection that come with traditional insurance. For a healthy family stretched thin by rising ACA premiums, it can be a reasonable bridge option. For anyone with ongoing medical needs, the savings usually aren’t worth the uncertainty.
Sources indicate that is a health sharing initiative the same as a health insurance policy?No. It’s a voluntary cost-sharing arrangement, not a legally binding insurance contract.
Can I use a health sharing initiative and still contribute to an HSA?Not based on the health share alone; you also need to be enrolled in a genuine HDHP to be HSA-eligible.
Will a health sharing strategy cover a pre-existing condition?Usually only after a waiting period, which varies by organization, often 12 to 36 months.
Does the ACA’s individual mandate penalty apply if I only have a health share?No, the federal individual mandate penalty was eliminated starting in 2019, so this isn’t a factor either way.
🔗 Related Articles
📰 #23323. Industry News: Docker Sandboxes vs. Containers: Choosing the Right Isolation for AI Agents 📰 #23039. Industry News: Ginger VS Grammarly: Which Grammar Checker is Better in (2022) ? 📰 #22468. Industry News: Matching AI Modality To User Intent: Designing The Right Interface
General
⚖️ Neutral
🌐 Moneycrashers
#21720. Vanguard Personal Advisor Review – About 0.30% a Year for Advisors You Can Call
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (271 w)
Vanguard Personal Advisor Review – About 0.30% a Year for Advisors You Can Call
📅 16 Nov 2026 | ⏱️ 1 min read (271 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Sources indicate that choose Vanguard Personal Advisor if you have $50,000 or more to invest and will call its advisors before substantial money decisions.
- Vanguard Personal Advisor turns your goals and how much risk you’ll take into a portfolio of Vanguard funds and keeps it rebalanced, for investors who’d rather hand off their investing.
- According to recent reports, personal Advisor fits investors with $50,000 to $500,000 who’ll book a call before major moves, such as starting retirement withdrawals.
Sources indicate that choose Vanguard Personal Advisor if you have $50,000 or more to invest and will call its advisors before substantial money decisions. About 0.30% a year buys a managed index portfolio plus those calls with a team of advisors. If you won’t call, Vanguard’s Digital Advisor runs the same funds for about half as much.
Vanguard Personal Advisor turns your goals and how much risk you’ll take into a portfolio of Vanguard funds and keeps it rebalanced, for investors who’d rather hand off their investing. It costs about 0.30% a year, under a third of the 1% to 1.2% that Kitces Research finds common among advisors on portfolios under $1 million, though a team takes your calls rather than one advisor.
According to recent reports, personal Advisor fits investors with $50,000 to $500,000 who’ll book a call before major moves, such as starting retirement withdrawals. Investors who just want the portfolio managed pay about half as much at Digital Advisor, while a flat-fee planner suits those whose money sits mostly outside Vanguard.
Learn more about Vanguard Personal Advisor or see how it compares to the best financial advisors.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.
🔗 Related Articles
📰 #21755. Vanguard Digital Advisor Review – Low-Cost Index Investing With No Human Advisor 📰 #21702. VSP Individual Vision Aims Review – Worth It If You Buy Glasses Every Year 📰 #21688. Latest Update: Monarch Money Review – Every Household Account in One Shared App, for $99.99 a Year
General
⚖️ Neutral
🌐 Moneycrashers
#21719. Check a Gas Price App Before You Fill Up – Cheaper Gas May Be Nearby
📅 16 Nov 2026 • ⏱️ 2m • 📖 Standard (496 w)
Check a Gas Price App Before You Fill Up – Cheaper Gas May Be Nearby
📅 16 Nov 2026 | ⏱️ 2 min read (496 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- According to recent reports, gas stations a few blocks apart can charge different prices for the same grade of gas, so compare them in a gas price app before your next fill-up.
- Industry observers note that regular gas averaged $4.01 a gallon nationally on Nov.
- Sources indicate that where a station sits affects what it charges.
According to recent reports, gas stations a few blocks apart can charge different prices for the same grade of gas, so compare them in a gas price app before your next fill-up. Pick the cheapest station on a route you already drive, since a detour of a few miles can cost more in gas than you save on a partial tank.
Industry observers note that regular gas averaged $4.01 a gallon nationally on Nov. 9, up from $3.07 a year earlier, according to AAA. Thanksgiving road trips add fill-ups away from home, at stations whose prices you don’t know.
Sources indicate that where a station sits affects what it charges. In a UC Santa Barbara study of stations in Santa Barbara County, the ones nearest freeway ramps tended to charge more than those on streets inside town, and so did stations near shopping centers and major roads. So at a highway exit, check prices a few blocks away from the ramp before you settle for the station beside it.
GasBuddy and Waze show prices their users report, and Google Maps lists prices when you search for gas stations. A user-reported price can be out of date, so check the sign before you pull in. Costco members can also see their warehouse’s current gas price in Costco’s app.
Say you fill a 15-gallon tank every week, and a station on your usual route charges 30 cents a gallon less than where you stop now. That’s $4.50 a fill-up, about $234 a year. A detour cuts into that. At $4 a gallon in a car that gets 25 miles per gallon, each mile costs 16 cents, so a station 2 miles off your route adds a 4-mile round trip, or 64 cents. On 15 gallons at 30 cents off, you still come out $3.86 ahead. For a station only 10 cents cheaper, though, a 5-gallon fill saves 50 cents, less than the 64-cent drive.
Recent findings suggest that timing helps a little. GasBuddy’s 2026 analysis found that in most states Sunday was the most reliably cheap day to fill up and Wednesday through Friday tended to cost more. Filling up on your state’s cheapest day instead of its priciest can save 4 to 9 cents a gallon.
Open the app when your gauge hits a quarter tank, while you still have the range to pass up the station in front of you.
To pick a gas price app, compare the best apps to find cheap gas stations.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.
🔗 Related Articles
📰 #22971. Breaking: Is a gas oven bad for bread?: Why a gas oven may be interfering with your go-to steaming method. 📰 #21065. Can You Burn Yard Waste on Your Property? Check the Rules Before You Risk a $10,000 Fine 📰 #19442. A Deadly Blood Cancer May Begin More Than 50 Years Before Symptoms Appear
General
⚖️ Neutral
🌐 Wellkeptwallet
#21718. Solo Health Review (2026): Costs, Coverage, Pros & Cons
📅 21 Oct 2026 • ⏱️ 14m • 📚 Deep Dive (2894 w)
Solo Health Review (2026): Costs, Coverage, Pros & Cons
📅 21 Oct 2026 | ⏱️ 14 min read (2894 words, 📚 Deep Dive) | Source: Wellkeptwallet
⏱️ ~14 mins left to finish
📖 0% read
💡 Key Takeaways
- It has been revealed that if you’re self-employed, finding affordable health coverage can be challenging.
- Solo Health offers a different approach to health coverage designed specifically for entrepreneurs, freelancers, and self-employed business owners.
- It has been revealed that but how does Solo Health work?
It has been revealed that if you’re self-employed, finding affordable health coverage can be challenging. Traditional health insurance premiums can take a big bite out of your budget, especially when you’re paying for coverage without employer help.
That’s where Solo Health comes in.
Solo Health offers a different approach to health coverage designed specifically for entrepreneurs, freelancers, and self-employed business owners. Instead of purchasing a traditional individual health insurance policy, eligible business owners establish a self-funded major medical blueprint through their business.
It has been revealed that but how does Solo Health work? Is the coverage comprehensive? And could it actually save you money? In this Solo Health review, we’ll break down the costs, benefits, potential drawbacks, and key details you should understand before enrolling.
Solo Health is a health coverage solution designed for self-employed individuals and business owners who want an alternative to traditional individual health insurance.
The manufacturer offers self-funded major medical plans that provide access to healthcare services through a nationwide PPO provider network.
Unlike a traditional insurance policy purchased through the Affordable Care Act (ACA) Marketplace, Solo Health uses a business-based structure.
Your business establishes its own self-funded health strategy to cover eligible medical claims.
According to Solo Health, its plans include:.
One of Solo Health’s biggest selling points is major medical coverage specifically designed for self-employed people.
However, Solo Health is not a traditional ACA Marketplace insurance policy, and eligibility depends on a health questionnaire.
In a recent development, solo Health operates differently from both traditional health insurance and healthcare-sharing programs. Instead of purchasing an individual insurance policy, your business establishes a self-funded health strategy.
That self-funded plan pays eligible medical claims under the terms of your plan documents.
Here’s a simplified overview of how it works:.
Preventive care is generally covered without meeting your deductible.
Prescription medications have their own coverage rules, including copays after the deductible.
Solo Health describes its product as a self-funded major medical health proposal, not a healthcare-sharing ministry or a conventional individual insurance policy.
Eligible medical claims are paid through your business’s self-funded health plan.
While Solo Health provides major medical benefits, you should not assume it has all the same eligibility protections, regulatory requirements, or consumer safeguards as an ACA-compliant individual insurance policy.
For example, Solo Health requires applicants to complete a health questionnaire and meet its participation requirements. This differs significantly from ACA Marketplace plans, which generally cannot reject applicants because of preexisting medical conditions.
Before enrolling, make sure you understand the blueprint documents, coverage exclusions, and how the plan pays medical claims.
Solo Health offers several key medical benefits designed to protect members from both routine healthcare expenses and larger medical bills.
Here’s a closer look at what is included.
Solo Health covers eligible preventive healthcare services at 100%, with no deductible required.
Industry observers note that this can be particularly helpful for self-employed individuals who want to stay on top of their health without paying the full cost of every preventive appointment. However, diagnostic tests or treatments performed during a preventive visit may be billed differently.
It has been revealed that solo Health covers primary care physicians and medical specialists. Members can access participating providers through the MultiPlan PHCS network, now associated with Claritev.
It has been revealed that you generally don’t need a referral to see a specialist. For most non-preventive visits, you’ll pay the applicable cost until you meet your deductible. After you meet your deductible, the proposal covers eligible medical services at 100%, subject to plan terms.
According to recent reports, one of the most important reasons to have health coverage is protection against unexpected medical emergencies. A serious accident, hospitalization, or surgery can result in tens of thousands of dollars in medical bills.
Solo Health includes benefits for:.
According to the tech giant, emergency services are processed as in-network regardless of which hospital provides the care.
Certain planned hospital admissions and surgeries require prior authorization.
Solo Health covers eligible mental health and substance use treatment. This can include outpatient therapy and other qualifying services. However, limits apply.
For example, Solo Health limits outpatient mental health therapy to 40 visits per covered individual each year. Some mental health treatments may also require prior authorization. If you regularly use mental health services, review these limitations before enrolling.
Solo Health includes prescription benefits administered through FairosRx. Preventive medications in Tier 1 are covered at $0. For other covered medications, members generally pay the discounted cost until they meet their deductible.
Afterward, prescription copays apply based on the medication’s tier. Some specialty medications can still involve high out-of-pocket costs.
Industry observers note that solo Health also lists maternity and newborn care among its covered benefits. This can include eligible prenatal services, childbirth, and medical care for newborns.
However, anyone planning to start or expand a family should review the blueprint’s maternity provisions, eligibility requirements, and applicable exclusions before enrolling. Don’t assume every pregnancy-related service will automatically qualify for payment.
It has been revealed that one of the biggest questions when considering any health coverage option is how much you’ll pay. Solo Health offers three blueprint designs, each with a different deductible.
The main difference between these prepares is how much you must pay toward eligible medical expenses before the plan pays most covered costs at 100%.
It has been revealed that all three prepares offer the same core coverage and provider network. The deductible you select influences your monthly payment. Generally speaking, plans with lower deductibles cost more per month, while plans with higher deductibles cost less.
Recent findings suggest that your actual monthly cost depends on factors such as your age, location, household composition, and eligibility. Because pricing is individualized, the best way to determine your cost is to request a quote directly from Solo Health.
In a recent development, let’s say you choose the Solo Health plan with a $5,000 individual deductible. You would generally pay the applicable cost of eligible non-preventive healthcare services until you’ve spent $5,000 toward your deductible.
Recent findings suggest that after that, the plan pays 100% of eligible medical expenses for the remainder of the plan year. However, prescription copays and potential out-of-network charges can still apply.
This is why it’s important to understand the difference between your deductible and your total possible healthcare expenses.
Solo Health advertises its deductible as the out-of-pocket maximum for eligible medical care.
This structure can make medical expenses easier to initiative for.
However, the advertised maximum may not cover every expense you could incur.
Prescription copays, excluded services, and charges above the plan’s out-of-network reimbursement amount may result in additional costs.
When comparing plans, consider both your monthly payments and what you could reasonably afford if you had a major medical event.
Solo Health uses a six-tier prescription drug structure. Here is the organization’s published schedule for covered medications after meeting the deductible.
Tier 1 preventive medications are available without meeting the deductible. For most other covered prescriptions, these copays apply after the deductible is satisfied. The initiative also restricts certain expensive medications.
It has been revealed that for example, the initiative may exclude non-specialty medications that exceed specified price thresholds. If you take prescription medications regularly, check the organization’s formulary to confirm whether your medications are covered and what they might cost.
A Health Savings Account (HSA) can be a valuable tool for managing healthcare expenses. HSAs can offer tax advantages when you contribute, invest, and use the funds for qualified medical expenses.
Industry observers note that according to Solo Health’s published FAQ, the V2500 and V5000 plan designs are HSA-eligible, while the V10000 plan is not at the moment listed as HSA-eligible. However, HSA eligibility depends on federal tax requirements, not simply a plan’s marketing designation.
Before contributing, confirm that your specific coverage qualifies as an HSA-compatible high-deductible health plan under current IRS rules. This matters because deductible amounts alone don’t establish HSA eligibility.
Customer experiences can provide valuable insight when evaluating a healthcare tech giant. However, a company’s advertised benefits differ from what customers experience when submitting medical claims.
Solo Health publishes information about its coverage, member services, and claims administration. It also offers concierge assistance and an online member portal.
Solo Health offers several features that may appeal to certain self-employed individuals.
It has been revealed that many freelancers and small business owners don’t have access to employer-sponsored health insurance. Solo Health is specifically designed for people in this situation.
Its business-based structure gives qualifying entrepreneurs another option to consider when shopping for health coverage.
Three deductible levels let members choose a blueprint that fits their financial situation. Someone with a larger emergency fund might prefer a higher deductible to reduce monthly costs.
Another person might prefer paying more each month in exchange for a lower deductible. The key is choosing a plan that fits both your budget and your ability to handle unexpected medical expenses.
Solo Health provides access to the MultiPlan PHCS network, which includes participating providers across all 50 states.
Sources indicate that this may be especially valuable for entrepreneurs who travel frequently or work in multiple locations. Members can also seek out-of-network care, although additional financial risks can apply.
Unlike limited-benefit programs, Solo Health advertises coverage for major medical expenses such as hospital stays, surgeries, and emergency care.
It also includes preventive care, prescription benefits, and mental health services. The company states that there are no annual or lifetime dollar caps on covered medical benefits.
Industry observers note that solo Health’s business-based structure may offer tax advantages for eligible business owners. The company states that monthly plan costs are generally deductible as a business expense.
However, the tax treatment depends on your business structure and individual circumstances. Consult a qualified tax professional before assuming your payments will qualify for a deduction.
Eligible preventive services are covered at 100% from the beginning of coverage. This feature helps people prioritize preventive care while managing overall medical expenses.
While Solo Health has appealing features, it also has notable limitations.
Solo Health requires applicants to have an eligible business with an active EIN. Applicants must also complete a health questionnaire.
According to recent reports, if you don’t meet the tech giant’s participation requirements, you may not qualify for coverage. This makes Solo Health less accessible than ACA Marketplace coverage, which generally offers guaranteed glitch during applicable enrollment periods.
Recent findings suggest that A $10,000 deductible may be manageable for someone with substantial savings. However, it could create financial hardship for someone living paycheck to paycheck.
Industry observers note that before selecting a high-deductible plan, make sure you have enough savings to handle unexpected healthcare costs. The lowest monthly payment isn’t necessarily the best financial decision if it exposes you to expenses you cannot afford.
It has been revealed that solo Health uses reference-based pricing for out-of-network services. This means the proposal may reimburse a benchmarked amount rather than the provider’s full billed charge.
According to recent reports, if the provider charges more than the initiative allows, you could be responsible for the difference. This is sometimes called balance billing.
Although Solo Health offers support services to help members navigate medical bills, that does not necessarily eliminate the risk of additional charges.
Solo Health’s enrollment process includes health-related eligibility questions. This differs from ACA-compliant individual health insurance.
If you have ongoing medical conditions or a complicated medical history, review the eligibility requirements carefully.
Accurate answers are essential, and the tech giant states that incomplete or inaccurate information can result in denial of coverage.
Although Solo Health advertises no annual or lifetime dollar caps on covered medical benefits, certain services have visit limits.
Industry observers note that for example, outpatient mental health therapy is generally limited to 40 visits annually per covered individual. Some treatments also require prior authorization. Read the complete plan documents so you understand these limitations before enrolling.
Solo Health’s self-funded model may be unfamiliar to people who have only purchased traditional insurance.
The arrangement involves a self-funded business health initiative, third-party administration, and a medical reimbursement policy.
Because this structure differs from a standard individual insurance policy, it is worth reviewing the legal and financial responsibilities involved.
How does Solo Health compare with a conventional ACA Marketplace proposal?
Traditional ACA Marketplace insurance offers important consumer protections, including guaranteed coverage of preexisting conditions and standardized requirements for essential health benefits.
Solo Health offers a different structure that may appeal to qualifying business owners. However, these products are not interchangeable. For someone with ongoing medical needs, ACA-compliant coverage may provide greater predictability around eligibility and consumer protections.
For an eligible entrepreneur, Solo Health may be worth comparing based on its benefits, provider access, and total annual costs.
Sources indicate that another useful comparison is Solo Health versus healthcare-sharing organizations such as Zion HealthShare. Although both may appeal to people exploring alternatives to conventional individual insurance, they work differently.
Solo Health offers a self-funded major medical blueprint established through an eligible business.
Its structure includes formal plan documents, medical claims administration, and a self-funded plan structure.
According to recent reports, zion HealthShare is a healthcare-sharing organization. Members contribute monthly amounts to share eligible medical expenses within the community.
Healthcare-sharing programs are not insurance, and they don’t guarantee payment of medical expenses the same way an insurance contract does.
The better option depends on your needs. Solo Health may be more appealing to business owners who want a structured major medical plan with a nationwide provider network.
Zion HealthShare may appeal to people who are comfortable with the healthcare-sharing model and its guidelines. Don’t choose either based on monthly costs alone. Consider the eligibility requirements, exclusions, payment structure, and your financial exposure if you experience a major medical event.
Solo Health may be worth considering for:.
It may be particularly appealing to someone who wants to explore a business-based health proposal rather than purchasing coverage through the individual insurance market.
Solo Health may be less suitable for:.
If you have significant ongoing medical expenses, compare your options carefully.
If you’re interested in Solo Health, you can start the enrollment process online.
It has been revealed that make sure you have an eligible business with an active EIN. Review the organization’s health eligibility requirements before proceeding.
Visit Solo Health’s website and enter the information requested. Your quote will depend on your individual circumstances.
Review the three available proposal designs. Consider both the monthly cost and what you might have to pay if you need significant medical care.
Answer the required health questions accurately. Enrollment is subject to approval.
Before completing enrollment, carefully review the plan’s Summary Plan Description, exclusions, and payment terms.
Once approved and enrolled, you can access your plan information through the member portal.
Solo Health operates a business-based, self-funded major medical blueprint with a defined administrative structure. However, a documented plan structure does not independently verify financial strength, claims performance, or customer satisfaction.
Prospective members should review the legal documents and verify the applicable entities and regulatory disclosures.
It has been revealed that solo Health requires a health questionnaire to determine eligibility. Unlike ACA Marketplace plans, enrollment is not guaranteed regardless of medical history.
Ask the organization how its eligibility rules and strategy terms apply to your specific circumstances.
According to recent reports, yes. Solo Health allows eligible business owners to include qualifying family members.
The company publishes family aggregate deductibles equal to twice the individual deductible.
Sources indicate that possibly. Solo Health uses the MultiPlan PHCS network.
It has been revealed that verify that your doctor participates in and accepts your specific plan before enrolling. Out-of-network care may be available, but additional charges can apply.
Solo Health generally allows members to choose a different deductible at renewal.
Mid-year changes require approval and may affect the monthly cost.
They may be deductible depending on your business structure and tax situation.
Consult your tax professional for guidance.
Solo Health advertises access to participating providers in all 50 states.
However, nationwide provider access does not necessarily mean every applicant or business can enroll in every state.
Confirm availability and eligibility directly with the company.
Solo Health offers an interesting alternative for self-employed individuals seeking major medical coverage outside the traditional individual insurance market. Its biggest advantages include multiple deductible options, access to a nationwide PPO network, preventive care benefits, and coverage for significant medical expenses.
For qualifying entrepreneurs, the business-based structure may also provide financial and tax-planning opportunities. However, there are key trade-offs. Applicants must meet health eligibility requirements, higher deductibles can create substantial out-of-pocket costs, and out-of-network billing can become complicated.
In a recent development, I recommend comparing Solo Health with at least two other coverage options before deciding. Look beyond the monthly payment and calculate what you might spend over an entire year, including deductibles, prescription costs, and potential out-of-network expenses.
Recent findings suggest that the goal isn’t simply to find the cheapest health proposal. It’s to find coverage that protects your health and your finances when you need it most. Eligible self-employed business owners may want to explore Solo Health.
Disclaimer: This article is for informational purposes only and is not medical, legal, insurance, or tax advice. Solo Health is a self-funded major medical plan using a captive-based funding structure, not an ACA Marketplace individual insurance policy or healthcare-sharing ministry. Official plan documents govern coverage, eligibility, exclusions, and reimbursement. Verify all details with the provider before enrolling.
General
⚖️ Neutral
🌐 Goodfinancialcents
#21717. 13 Best Investment Opportunities for Accredited Investors
📅 18 Aug 2023 • ⏱️ 14m • 📚 Deep Dive (2851 w)
13 Best Investment Opportunities for Accredited Investors
📅 18 Aug 2023 | ⏱️ 14 min read (2851 words, 📚 Deep Dive) | Source: Goodfinancialcents
⏱️ ~14 mins left to finish
📖 0% read
💡 Key Takeaways
- Home » Invest » 13 Best Investment Opportunities for Accredited Investors.
- In a recent development, unlock the exclusive world of accredited investing where the stakes are high, the opportunities are vast, and the rewards can be game-changing.
- Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
Home » Invest » 13 Best Investment Opportunities for Accredited Investors.
In a recent development, unlock the exclusive world of accredited investing where the stakes are high, the opportunities are vast, and the rewards can be game-changing. From hedge funds to venture capital delights, embark on an investment journey that only a select few have the privilege to explore.
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
The GFC® Money Expert Review Board.
The GFC® Money Expert Review Board is a team of financial experts who provide independent, unbiased reviews of financial products...
GoodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Newly introduced York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Newly introduced York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
In a recent development, when I became an accredited investor, I found myself among an elite group with the financial means and regulatory clearance to access investments that many couldn’t. This opened doors to exclusive realms like hedge funds, venture capital firms, specific investment funds, private equity funds, and more.
Even though I had this “exclusive access” it took me a while to start investing in alternative asset classes.
It has been revealed that the Securities and Exchange Commission states that as an accredited investor, I possess a level of sophistication that equips me to craft a riskier investment portfolio than a non-accredited investor. While this might not be universally true for everyone, in my case, I had demonstrated the financial resilience to bear more risk (see barbell investing), especially if my investments took an unforeseen downturn.
One of the intriguing aspects I discovered was that investment opportunities for accredited investors aren’t mandated to register with financial authorities. This means they often come with fewer disclosures and might not be as transparent as the registered securities available to the general public.
The underlying belief is that my status as a sophisticated investor implies a deeper understanding of financial risks, a need for less disclosure of unregistered securities, and a conviction that these exclusive investment opportunities are apt for my funds.
Industry observers note that on a personal note, as a practicing CFP®, I haven’t always worked with accredited investors. Early in my career, I didn’t quite grasp the allure. However, as time went on, I began to see the broader spectrum of investment options available to accredited investors.
As I learned more the clearer it became why this realm was so sought after. The variety and potential of these exclusive opportunities were truly eye-opening, reshaping my perspective on the world of investing.
According to recent reports, an accredited investor is an individual or a business entity that is allowed to trade securities that may not be registered with financial authorities. They are entitled to this privileged access because they satisfy one or more requirements regarding income, net worth, asset size, governance status, or professional experience.
The concept of an accredited investor originated from the idea that individuals or entities with a higher financial acumen or more resources are better equipped to understand and bear the risks of certain investment opportunities.
Historically, the distinction between accredited and non-accredited investors was established to protect less experienced investors from potentially risky or less transparent investment opportunities.
Regulatory bodies, such as the U.S. Securities and Exchange Commission (SEC), have set criteria to determine who qualifies as an accredited investor, ensuring that they have the financial stability and sophistication to engage in more complex investment ventures.
To be classified as an accredited investor, one must meet specific criteria set by regulatory bodies:.
Here’s a rundown of some of the top investments for accredited investors….
Fundrise has revolutionized the real estate investment landscape. By democratizing access to real estate portfolios, it allows individuals to invest without the complexities of property management or the need for vast capital. The platform’s innovative approach provides exposure to a traditionally lucrative, yet often inaccessible, sector of the market.
Industry observers note that through Fundrise, investors can access a diversified range of properties, from commercial ventures to residential units. The platform’s expert team curates these portfolios, ensuring a balance of risk and reward. With its user-friendly interface and transparent reporting, Fundrise has become a top choice for many venturing into real estate investments.
It has been revealed that investors start by choosing a suitable investment initiative on Fundrise. Once invested, the platform pools the funds with other investors and allocates them across various real estate projects. As these properties generate rental income or appreciation in value, investors receive returns in the form of dividends or appreciation.
It has been revealed that equitybee offers a unique platform that bridges the gap between private companies on the cusp of going public and potential investors. This innovative approach provides a golden opportunity for investors to tap into the potential of startups and other private firms before they make their public debut.
According to recent reports, the platform’s primary focus is on employee stock options. By allowing investors to invest in these options, they can potentially benefit from their appreciation as the firm grows. With a vast array of companies, from emerging startups to established giants, Equitybee presents a diverse range of investment opportunities.
Investors browse available stock options from various companies on Equitybee. Once they choose an option, they invest their funds, which are then used to purchase the stock options from the employees. If the firm goes public or gets acquired, the investor stands to gain from the increased value of these stocks.
Industry observers note that percent stands as a beacon in the vast sea of the private credit market, illuminating a sector often overshadowed by traditional investments. This burgeoning market, valued at over $7 trillion, consists of companies borrowing from non-bank lenders. Percent offers a unique vantage point into this market, allowing investors to diversify their portfolios beyond typical stocks and bonds.
The allure of Percent lies in its ability to offer shorter terms and higher yields, combined with investments that are largely uncorrelated with public markets. This makes it an attractive proposition for those looking to step away from the volatility of traditional markets.
Upon joining Percent, investors are presented with a plethora of private credit opportunities. After selecting an investment, funds are pooled with other investors and lent out to companies seeking credit. As these companies repay their loans, investors earn interest, providing a steady income stream.
It has been revealed that masterworks paints a vivid picture of art investment, blending the worlds of finance and fine art. Traditionally, investing in art was a luxury reserved for the elite. However, Masterworks has democratized this, allowing individuals to buy shares in artworks from world-renowned artists.
The platform’s strength lies in its expertise. From authentication to storage, every facet of art investment is handled meticulously. This ensures that investors can appreciate both the beauty of their investments and the potential financial returns.
According to recent reports, after registering on Masterworks, investors can browse a curated selection of artworks. They can then purchase shares, representing a fraction of the artwork’s value. Masterworks take care of storage, insurance, and eventual sale. When the artwork is sold, investors share the profits based on their ownership.
Recent findings suggest that yieldstreet stands at the intersection of innovation and alternative investments. It offers a smorgasbord of unique investment opportunities, ranging from art to marine finance. For those looking to venture beyond the beaten path of traditional stocks and bonds, Yieldstreet presents a tantalizing array of options.
The platform’s allure lies in its curated selection of alternative investments, each vetted by experts. This ensures that while investors are treading unconventional grounds, they’re not stepping into the unknown blindly.
It has been revealed that investors begin by browsing through the diverse investment opportunities on Yieldstreet. After selecting their preferred asset class, their funds are pooled with other investors and allocated to the chosen venture. Returns are generated based on the performance of these assets, be it through interest, dividends, or asset appreciation.
In a recent development, acreTrader, as its name suggests, brings the vast expanses of farmland to the investment table. It offers a unique opportunity to invest in agricultural land, combining the stability of real estate with the evergreen nature of agriculture. With the global population on the rise, the value of fertile land is only set to increase.
The platform meticulously vets each piece of land, ensuring only the most promising plots are available for investment. This rigorous process ensures that investors are planting their funds in fertile ground, poised for growth.
Investors peruse available farmland listings on AcreTrader. After selecting a plot, they can invest, effectively owning a portion of that land. AcreTrader manages all aspects, from liaising with farmers to ensuring optimal land use. Investors earn from the appreciation of land value and potential rental income.
It has been revealed that equityMultiple is a testament to the power of collective investment in the real estate sector. By leveraging the principles of crowdfunding, it offers a platform where multiple investors can pool their resources to finance high-quality real estate projects. This collaborative approach allows for diversification and access to projects that might be out of reach for individual investors.
Recent findings suggest that the platform’s strength lies in its curated selection of real estate opportunities, ranging from commercial spaces to residential properties. With a team of seasoned real estate professionals at the helm, EquityMultiple ensures that each project is vetted for maximum potential and minimal risk.
Upon joining, investors can explore a variety of real estate projects. After committing to a project, their funds are pooled with other investors to finance the venture. Returns are generated through rental incomes, property appreciation, or the successful completion of development projects.
CrowdStreet stands as a pillar in the commercial real estate investment domain. With its vast experience and industry connections, it offers a platform where investors can tap into prime real estate projects across the nation. From bustling urban centers to tranquil suburban locales, CrowdStreet provides a diverse range of investment opportunities.
According to recent reports, the platform’s expertise ensures that each project is meticulously vetted, offering a blend of potential returns and stability. For investors looking to delve into commercial real estate without the hassles of property management, CrowdStreet is an ideal choice.
According to recent reports, after registration, investors can browse a myriad of commercial real estate offerings. Upon investing in a project, CrowdStreet manages the investment, providing regular updates and ensuring optimal project execution. Investors earn returns based on the project’s performance, be it through rentals, sales, or project completions.
Recent findings suggest that mainvest offers a refreshing twist in the investment landscape, focusing on the heart and soul of the American economy: local businesses. From quaint cafes to innovative startups, Mainvest provides a platform where investors can support and benefit from the growth of small businesses in their communities.
Recent findings suggest that the platform’s community-centric approach ensures that investments are not just about returns but also about fostering local economies. For those looking to make a difference while earning, Mainvest presents a unique opportunity.
Industry observers note that investors can explore various local businesses seeking capital on Mainvest. By investing, they essentially buy a revenue-sharing note, earning a percentage of the business’s gross revenue until a predetermined return is achieved.
Vinovest uncorks the world of wine investment, offering a blend of luxury, history, and financial growth. Fine wines have been a symbol of opulence for centuries, and Vinovest provides a platform where this luxury becomes an accessible investment.
With a team of wine experts guiding the way, the platform ensures that each wine is not just a drink but an investment poised for appreciation. From sourcing to storage, Vinovest handles every facet, ensuring the wine’s value grows over time.
After signing up, investors set their preferences and investment amounts. Vinovest then curates a wine portfolio based on these preferences, handling sourcing, authentication, and storage. As the wine appreciates, so does the investor’s portfolio.
Arrived Homes offers a fresh perspective on real estate investment, focusing on the charm of single-family homes. While skyscrapers and commercial complexes often dominate real estate discussions, single-family homes offer stability, consistent returns, and a touch of nostalgia.
Recent findings suggest that the platform’s strength lies in its focus. By concentrating on single-family homes, it offers investors a chance to tap into a stable real estate segment, benefiting from both rental income and property appreciation.
According to recent reports, investors browse available properties on Arrived Homes. After selecting a property, they can invest in shares, representing a portion of the home’s value. As the property is rented out, investors earn a share of the rental income. Additionally, any appreciation in property value benefits the investors.
RealtyMogul stands tall in the commercial real estate investment landscape. It offers a platform where diversification meets opportunity, presenting a range of commercial properties for investment. From bustling office spaces to serene residential complexes, RealtyMogul provides a plethora of options for investors to expand their portfolios.
It has been revealed that the platform’s prowess lies in its dual approach. Investors can either dive into non-traded REITs or make direct investments in specific properties. This flexibility ensures that both novice and experienced investors find opportunities that align with their investment goals.
According to recent reports, upon joining RealtyMogul, investors can choose between REITs or direct property investments. Their funds are then channeled into these real estate ventures. Returns are generated through rental incomes, property sales, or successful project completions.
In a recent development, the world of accredited investing is dynamic and ever-evolving. Emerging trends suggest a shift towards democratizing investment opportunities, with regulatory bodies considering more inclusive criteria for accredited investor status. This shift aims to balance the need for investor protection with the recognition that financial acumen can come from experience and education, not just wealth.
Industry observers note that furthermore, technological advancements are playing a pivotal role. The rise of blockchain and tokenized assets, for instance, is creating fresh avenues for investment and might reshape the landscape of opportunities available to accredited investors.
As the line between traditional and alternative investments blurs, the future promises a more integrated, inclusive, and innovative environment for accredited investors.
Understanding the role and opportunities of accredited investors is crucial in the modern financial landscape. While the distinction offers privileged access to unique investment opportunities, it also comes with increased risks and responsibilities.
Industry observers note that as the world of investing continues to evolve, potential accredited investors are encouraged to stay informed, conduct thorough research, and seek professional advice. The realm of accredited investing, with its blend of challenges and opportunities, promises exciting prospects for those ready to navigate its complexities.
SEC.gov (2023, Jul 12) Accredited Investor https://www.sec.gov/education/capitalraising/building-blocks/accredited-investor.
It has been revealed that jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance book Soldier of Finance. He was a financial planner for 16+ years having founded, Alliance Wealth Management, a SEC Registered Investment Advisory firm, before selling it to focus on his passion - educating the masses on the importance of financial freedom through this blog, his podcast, and YouTube channel. Jeff holds a Bachelors in Science in Finance and minor in Accounting from Southern Illinois University - Carbondale. In addition to his CFP® designation, he also earned the marks of AAMS® - Accredited Asset Management Specialist - and CRPC® - Chartered Retirement Planning Counselor. While a practicing financial advisor, Jeff was named to Investopedia's distinguished list of Top 100 advisors (as high as #6) multiple times and CNBC's Digital Advisory Council. Jeff is an Iraqi combat veteran and served 9 years in the Army National Guard. His work is regularly featured in Forbes, Business Insider, Inc.com and Entrepreneur.
Business & Policy
⚖️ Neutral
🌐 Moneycrashers
#21716. Stock Rover Review – Deep Screens & Fair Values for Stock Pickers
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (207 w)
Stock Rover Review – Deep Screens & Fair Values for Stock Pickers
📅 16 Nov 2026 | ⏱️ 1 min read (207 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- In a recent development, choose Stock Rover if you pick individual stocks or funds by their financials.
- Long-term investors who pick stocks or funds by their financials get the most from Premium Plus at $588 a year, the cheapest initiative with unlimited fair values, ratings, and equation screens.
- Learn more about Stock Rover or see how it compares to the best stock screeners.
In a recent development, choose Stock Rover if you pick individual stocks or funds by their financials. It screens stocks on years of firm financials, estimates what each is worth, and analyzes your linked brokerage accounts in one place. Skip the paid aims if you own a few index funds, which need none of that depth.
Long-term investors who pick stocks or funds by their financials get the most from Premium Plus at $588 a year, the cheapest initiative with unlimited fair values, ratings, and equation screens. Investors who own a handful of index funds need none of it, and the free plan still tracks up to two linked brokerage accounts.
Learn more about Stock Rover or see how it compares to the best stock screeners.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every firm or offer available in the marketplace.
General
⚖️ Neutral
🌐 Moneycrashers
#21715. American Consumer Opinion Review, Higher-Paying Surveys, Plus Product Tests and Focus Groups
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (229 w)
American Consumer Opinion Review, Higher-Paying Surveys, Plus Product Tests and Focus Groups
📅 16 Nov 2026 | ⏱️ 1 min read (229 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Join American Consumer Opinion beside the survey sites you already use if you want higher-paying surveys, plus product tests and focus groups.
- American Consumer Opinion, or ACOP, is a free survey panel for people who want higher-paying surveys, plus product tests and focus groups.
- According to recent reports, american Consumer Opinion is worth joining as a second or third panel for members who answer each invitation and can wait weeks for points to clear.
Join American Consumer Opinion beside the survey sites you already use if you want higher-paying surveys, plus product tests and focus groups. It pays out from $10 by PayPal, Cash App, check, or gift card. Expect slightly less frequent surveys, and points that can take weeks to clear.
American Consumer Opinion, or ACOP, is a free survey panel for people who want higher-paying surveys, plus product tests and focus groups. It dates to 1986, and Symmetric runs it today.
According to recent reports, american Consumer Opinion is worth joining as a second or third panel for members who answer each invitation and can wait weeks for points to clear. Members who want small, frequent payouts will get the most from it alongside a site with daily surveys.
Learn more about American Consumer Opinion or see how it compares to the best paid survey sites.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Industry observers note that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every firm or offer available in the marketplace.

General
⚖️ Neutral
🌐 Mrmoneymustache
#21714. How Unlimited Free Stuff from Amazon Almost Ruined My Retirement
📅 07 Oct 2025 • ⏱️ 10m • 📚 Deep Dive (2039 w)
How Unlimited Free Stuff from Amazon Almost Ruined My Retirement
📅 07 Oct 2025 | ⏱️ 10 min read (2039 words, 📚 Deep Dive) | Source: Mrmoneymustache
⏱️ ~10 mins left to finish
📖 0% read
💡 Key Takeaways
- It all started last winter when I innocently posted a review for a heated vest I had bought on Amazon.
- Industry observers note that “Congratulations!
- I was already aware of Amazon Vine since I had seen product reviews from other people in the program – typically called “Vine Voices.” The basic idea of this program is that you can order stuff from Amazon for free, as long as you agree to review at least 80% of the things you order.
It all started last winter when I innocently posted a review for a heated vest I had bought on Amazon. I was happy with this fun new way to beat the winter and wanted to share it with others, so I gave it five stars. But soon after I clicked “Submit”, I got an email from Amazon which noted something like,.
Industry observers note that “Congratulations! You’ve been selected to join Amazon Vine for writing helpful reviews!”.
I was already aware of Amazon Vine since I had seen product reviews from other people in the program – typically called “Vine Voices.” The basic idea of this program is that you can order stuff from Amazon for free, as long as you agree to review at least 80% of the things you order.
“Hey, that’s cool”, I thought, “Who doesn’t like free stuff?
Especially since I’ve already been writing product reviews out of the goodness of my heart – why not be rewarded for it?”.
So without giving it much further thought, I clicked “accept” on their terms and conditions and joined the program.
And so began a saga that has taken me on a surprising journey over the past nine months causing me to:.
Sources indicate that okay, I’ll admit that there were also some upsides. My original idea was partly to save some money, by getting stuff I genuinely would have bought anyway, in a way that sounded fun. And that did happen – I saved at least a few thousand dollars on tools and materials for my construction business and the MMM-HQ Coworking space, for free. Plus, at least some of the motivation for signing up was to put myself through an experiment so I could write this blog article about it. And if you’re reading this, it looks like that happened too.
But I was still surprised at how powerful the combination of small nudges and incentives from Amazon was able to hijack my frugality instincts – and get me to do a bunch of work that wasn’t really the best use of my time.
So I figured if we review my journey and break it down with a bit of Behavioral Science, we could all learn a few valuable things by laughing at Mr. Money Mustache’s folly.
Scarcity Brain and the Online Casino Effect.
Recent findings suggest that one of the most interesting books I’ve read in recent years is Michael Easter’s Scarcity Brain. It’s an exploration of the sneaky ways that modern gambling platforms, marketing and social media algorithms are all built upon two weaknesses in our evolutionary programming:.
As I look back now, I realize that I fell straight into those same traps, because the Vine program has all the key properties of a casino or a TikTok feed:.
Sources indicate that but occasionally, there will be genuinely useful things like super nice light fixtures, tools and plumbing parts, an EV charger, and even some clothing. My favorite ridiculous Eagle shirt as featured in the Mustachianism music video was an Amazon Vine find.
As were a whole supply of super-realistic artificial plants, which while tacky in principle, have been amazing for hard-to-water courtyard garden areas at the MMM HQ.
In a recent development, I also had a lot of fun roping in friends and coworkers from HQ to help and share in the bounty. I let them help me request and review stuff that they wanted, and then they got to keep it. This seemed like a win/win because we shared the work and the fun of laughing at some of the ridiculous products available.
Still, as I went through this experiment this spring and summer and allowed the system to coax me into doing 80 reviews so I could upgrade my account from Vine Silver to Vine Gold*, I noticed something didn’t feel quite right.
According to recent reports, I was checking the Vine page every day for scores, even when I didn’t actually need anything. It would usually be a bust, but just often enough, something I actually wanted would come up, and I’d order it before it was too late. Scarcity and unpredictable rewards at work.
Then the bounty would come, I’d unpack it and photograph it with assembly-line speed so I could batch-write all the reviews once per week or so. For every review I did, I was spending time I’d rather spend doing something else. And for every questionable item I got, I was creating pollution and trash from its manufacturing and packaging – directly contradicting the main values of my life and my reason for writing this blog. And I saw all of this, yet I kept doing it!
So Was This The Downfall of MMM?
During the worst of this consumerism bender, things were dire. I was getting packages almost every day and my recycling bin was overflowing with cardboard. My son and my girlfriend started laughing at some of my more frivolous purchases, so I found myself discreetly tucking away the boxes when they were around to evade scrutiny.
But eventually, I moved into a recovery stage. I had been letting this habit continue out of laziness and as a form of procrastination: it’s very easy to order shit online and pretend I’m doing something useful, and much more difficult to get moving to do the things that really make my life enjoyable.
But I’m old enough to know that hitting the running trails and the gym for my daily workouts, and making progress on all my construction projects, and focusing on the computer as a creative tool rather than an entertainment device so I can get stuff done like this blog post, are the things that bring me the most joy.
Recent findings suggest that admittedly, some of the sucky factors of the Vine program helped make it easier to recover too. For every genuinely useful thing I found like a contractor-grade extension cord, I had to scan through endless screens of trinkets which not only wasted my time but actually pissed me off at their very existence.
In a recent development, I also noticed some of the deliberately reviewer-unfriendly features built into the program which reminded me that we reviewers are definitely just low-wage workers rather than any form of VIP. The search functionality is crap, and there is no way to filter or sort the results, because they want you to have to look through everything and they don’t care about the value of your time.
Then there is the hilariously bureaucratic AI-based evaluation system which would occasionally flag my totally tame, factual reviews as “Not meeting our Community Standards” without explaining what the problem was. So I’d have to go in and edit my review, randomly changing a couple of words and maybe some punctuation, and suddenly the AI would be pacified and accept my review. Just dumb.
This is What “Fuck You Money” is For!
It dawned on me that for many people, this is just what “work” looks like. You are given a bunch of tasks and a bunch of rules to follow, in a system you didn’t create and don’t get much say in changing. And then as long as you crank out your TPS Reports without rocking the boat too much, you get your paycheck.
Industry observers note that it reminded me of the Uber Driving experiment I did way back in 2017: as soon as I started working as a driver, I could immediately see dozens of improvements that could be made to the system that would make it function better for both drivers and passengers. But since I wasn’t the boss, nobody wanted to hear my ideas.
Sources indicate that experiences like these remind me that while I love hard work and I love learning latest things every day, I greatly prefer being the boss. And I’ve gotten pretty damned accustomed to it after 20 years of financial independence, so I see no need to give it up.
One interesting “gotcha” of the Vine program is that they do keep track of all the free stuff you get and send you a 1099 for its retail value at the end of the year. So it’s not really free, just discounted to whatever your marginal tax rate is (about 25% for me this year). If we peek into my account right now, this is how my 2025 is looking:.
So I got about $7000 worth of stuff, and could owe up to $1750 of tax on it. In my case, about 75% of it was “sold” to my business for commercial use (construction supplies which I used on jobs or HQ renovations) so it was effectively converted into real income rather than just tax burden. Some of it was stuff I would have bought anyway for my own house which I’ll gladly pay the taxes on. But there is also probably about $1000 of pure nonsense in there as well, for which I’ll owe a tax bill of $250 as penance for my itchy trigger finger on that “Order” button.
According to recent reports, thanks to some advice from wise readers in the comments (below), I have since learned that in most cases you can mark down this estimated value by 80% before declaring it – because you have effectively eliminated most of the resale value by opening and reviewing the product. Thus my tax bill will be more like $50 rather than $250. More detail in this Reddit discussion here.
Industry observers note that so here we are today. While I admit that I didn’t explicitly cancel my account, I used the “Keystone Habit” trick to override the temptation to view the Vine page – mapping that browser bookmark to my daily habits list instead, a little chart which I call my “Badassity Tracker”. The net result is that every time I click it, I’m taken straight to a reminder to get up from the computer and do a quick round of exercise, so I do that instead.
According to recent reports, and of course my writing of this article may be a violation of the terms and conditions of the program (“the first rule of Vine is to not talk about Vine”), so it might even get canceled on me. (and if so I’ll let you know because that would be funny story as well).
In a recent development, but I learned a lot about habits and addiction, and realized that this same feeling might be what drives people into One More Year Syndrome, as they keep working even when they can afford to quit. I have now coached enough people through this situation to see it is way more common than I would have ever guessed.
As with all MMM articles, there’s a real life lesson in this story. It’s not really about Vine or me or my habits, it’s about you continuing to look at yourself and your life, and always questioning your own assumptions or patterns. And asking the people you trust most for feedback as well:.
We will never be perfect, but the great news is we don’t have to be. All it takes is a little bit of self reflection and putting ourselves on a slightly better path, as often as we can as life goes on. We are all on a very long journey, so even a tiny course correction can make a huge difference in where we end up.
*(Vine Gold is not all that useful as it turns out as 99.9% of the available items seem to be the same trinkets you see in the Silver tier).
Sources indicate that ** What about the Heated Vest that started it all? Well, I still love that thing and now that fall is coming back it is already helping me be warmer in a cooler house. There are many good choices on Amazon, here’s one of them. Then pick out any USB battery pack to go with it, which also doubles as a very useful travel phone charger.
FTC: this blog uses affiliate links (including for Amazon) when possible so if you do buy anything through them, it will benefit the website. And thanks!
General
⚖️ Neutral
🌐 Moneycrashers
#21713. Industry News: Apps That Pay You Real Money – The Best Picks for Each Way to Earn
📅 16 Nov 2026 • ⏱️ 5m • 📚 Deep Dive (982 w)
Industry News: Apps That Pay You Real Money – The Best Picks for Each Way to Earn
📅 16 Nov 2026 | ⏱️ 5 min read (982 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~5 mins left to finish
📖 0% read
💡 Key Takeaways
- Pick the money-making app that fits what you can put in: Survey Junkie for spare minutes, Rakuten for online shopping, DoorDash or Uber for a car, and Neighbor for an empty garage.
- Sources indicate that most apps that pay you hand over small sums for spare minutes or spending you’d do anyway.
- Uber drivers in Chicago earned a median of $27.97 an hour in fares, tips, and certain promotions from Oct.
Pick the money-making app that fits what you can put in: Survey Junkie for spare minutes, Rakuten for online shopping, DoorDash or Uber for a car, and Neighbor for an empty garage. Favor apps that pay cash to your bank or PayPal, and expect real pay only for hours of work, a car, or things you own.
Sources indicate that most apps that pay you hand over small sums for spare minutes or spending you’d do anyway. By Survey Junkie’s own figures, three surveys a day earn as much as $40 a month, which works out to under $2 an hour by our math, since its surveys average 15 minutes.
Pay grows with what you put in. Uber drivers in Chicago earned a median of $27.97 an hour in fares, tips, and certain promotions from Oct. 5 to Nov. 2, 2026, before gas and other car costs. A private garage on Neighbor in Seattle lists for $333 a month on average. The picks below are the best apps for each way to earn. We judged each on what it pays for the time, spending, or space it takes, whether it pays cash rather than points or gift cards, its minimum to cash out, and who can join.
Survey Junkie lets you cash out from $5 by PayPal or bank transfer, and PayPal usually pays within a few hours, so you’ll know fast whether surveys suit you.
For more information, read our full Survey Junkie Review.
One long survey can pay up to $50, with cash-outs from $10 by PayPal, Cash App, check, or gift card. With slightly less frequent surveys, the panel works best beside a daily survey site.
For more information, read our full American Consumer Opinion Review.
Snakzy pays coins for playing the Android games it recommends, and once patient players collect 35,000 coins, about $35, they can cash out to PayPal or Venmo or take gift cards. There’s no iPhone app.
For more information, read our full Snakzy Review.
Field Agent’s jobs at stores near you generally pay $3 to $20 each, and $3 is enough to cash out, so it pays best at stores you already pass on errands.
For more information, read our full Field Agent Review.
Each of these pays only when you click through it or claim its offer before you buy, so open it before you check out or fill up.
Shopping online through Rakuten earns back a share of what you spend at its partner stores, and the cash goes out by PayPal or check four times a year once $5 has cleared.
For more information, read our full Rakuten Review.
Grocery shoppers get cash back on specific items with Ibotta, which pays out from $20 by PayPal or, where your bank allows it, to a bank account.
For more information, read our full Ibotta Review.
Upside’s gas offers average 11 cents a gallon by its own count, paid on top of your card’s rewards, and a bank transfer of $10 or more costs nothing.
For more information, read our full Upside Review.
Dashers get $2 to $10 or more in base pay per delivery offer plus all of their tips, paid by weekly direct deposit or, for eligible Dashers, daily for $1.99 through Fast Pay.
For more information, read our full DoorDash Dasher Review.
In most cities Uber indicates what a trip pays before you accept it and passes on every tip, and you can cash out up to six times a day through Instant Pay for a fee.
For more information, read our full Uber Driver Review.
Taskers on Taskrabbit set their own hourly rate in most categories, from furniture assembly to help moving, and clients pay Taskrabbit’s service fee on top of that rate.
For more information, read our full Taskrabbit Tasker Review.
Rover sitters set their own rates and schedule, Rover keeps 20% of each booking in most of the U.S., and the rest reaches their Rover account two days after each completed service.
For more information, read our full Rover Sitter Review.
Mercari is for small things you can mail. It takes 10% of the price plus any shipping the buyer pays, and direct deposit to your bank is free.
For more information, read our full Mercari Review.
Listing an empty garage, driveway, or shed on Neighbor is free, you set the price, and Neighbor keeps a 4.9% plus 30-cent fee from each monthly payout.
For more information, read our full Neighbor Review.
Webull pays in stock, not cash. Open a brokerage account and deposit $100 by January 6, 2027, and it adds 12 free fractional shares, slices of stock you can hold or sell.
For more information, read our full Webull Review.
Industry observers note that webull Financial LLC, Member SIPC, FINRA. Investing involves risk. More info at webull.com/disclosures. Options are not suitable for everyone. Losses can occur quickly. Review ODD at webull.com/disclosures. Subscription required. Fees may apply. More info at webull.com/disclosures.
Small sums come from spare minutes and purchases, while bigger pay takes your car, your free afternoons, or something you own. Choose the way that uses what you have to spare, and cash out as soon as each app lets you.
Compare the best paid survey sites for more ways to earn from surveys, or the best ways to earn free PayPal money for more apps that pay through PayPal.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Sources indicate that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every tech giant or offer available in the marketplace.
Business & Policy
⚖️ Neutral
🌐 Goodfinancialcents
#21712. How Much Does A Million Dollar Life Insurance Policy Cost?
📅 19 Aug 2023 • ⏱️ 21m • 📚 Deep Dive (4285 w)
How Much Does A Million Dollar Life Insurance Policy Cost?
📅 19 Aug 2023 | ⏱️ 21 min read (4285 words, 📚 Deep Dive) | Source: Goodfinancialcents
⏱️ ~21 mins left to finish
📖 0% read
💡 Key Takeaways
- Home » Insurance » Life » How Much Does A Million Dollar Life Insurance Policy Cost?
- According to recent reports, understanding the cost of a million-dollar life insurance policy can be pivotal in securing your family's financial future.
- Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
Home » Insurance » Life » How Much Does A Million Dollar Life Insurance Policy Cost?
According to recent reports, understanding the cost of a million-dollar life insurance policy can be pivotal in securing your family's financial future. But have you ever wondered just how accessible or costly such a policy might be?
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
The GFC® Money Expert Review Board.
The GFC® Money Expert Review Board is a team of financial experts who provide independent, unbiased reviews of financial products...
GoodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Latest York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The New York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
Do you think a million-dollar term life insurance policy sounds like too much insurance?
As a Certified Financial Planner, I see underinsured people every day.
A million-dollar term life insurance policy might actually be the minimum coverage needed for the typical middle-class household, but it’s affordable.
That might sound like an exaggeration, but if you crunch the numbers – just as we’ll be doing a little bit – you’ll realize that a million-dollar policy might be just what you need.
The good news is term life insurance isn’t nearly as costly as most people think.
What makes term life insurance even better is that larger policies cost less on a per thousand basis than smaller policies do. You may find the premium on a $1 million policy is only a little bit higher than it is for $500,000.
Sources indicate that probably, but let’s find out. A general rule of thumb is that you should get 10x your income as baseline coverage for life insurance.
If you’re young, that may be low because you may want to provide your family with enough to replace your income for 15 years or more.
Today, $1 million has become the new baseline for life insurance by a primary breadwinner. Anything less could leave your family financially impaired.
Here’s a list of all the different obligations you may want to have life insurance cover in the unfortunate event you pass away early.
Now that you have an idea of these obligations, let’s punch them into this life insurance calculator to find out if you need a million-dollar policy.
Industry observers note that according to Policy Genius, the average cost for a 20-year $1 million term life insurance policy for a 35-year-old male is $53 per month. However, your rate will vary according to the following factors.
Sources indicate that the best, and easiest place to start is online. I recommend having two or three insurers compete for your business to make sure you get the best rate and coverage. To see how cheap term life can be, choose your state from the map above to be matched with top life insurance providers instantly.
Let’s look at the individual components that can promptly add up to over a million-dollar policy.
This is where things can get a bit intimidating. Even if you earn a modest income, you may need close to $1 million to replace that income after your death in order to provide for your family’s basic living expenses.
The conventional wisdom in the insurance industry is that you should maintain a life insurance policy equal to between 10 times and 20 times your annual income. So if you earn around $50K per year, that would mean policy coverage between $500K and $1 million.
The complication today is that with interest rates being as low as they are that might not be enough either.
For example, if you have a $1 million policy that could be invested at 5% per year, your family could live on the interest earned – which conveniently comes to $50,000 per year – for the next 20 years.
That would still leave the original $1 million intact to cover other expenses. But with today’s microscopic interest rates, there’s no way to get a guaranteed return of 5% on your money, certainly not for 15 or 20 years.
In a recent development, also, keep in mind that most insurance companies have a maximum multiplier you can apply to your income for life insurance coverage. For example, it wouldn’t make much sense for a 22-year-old making $27,000 per year to get a $2 million life insurance. Or a 65-year-old that is retired to secure a $3 million dollar policy.
The table below is approximately how much you’re allowed to multiply your income based on your age and income:.
Using the table above as a guide, a 35-year-old making $150,000 per year would be capped at taking out a $4.5 million term policy ($150,000 x 30 = $4,500,000).
Here we start with the basics – wrapping up your final affairs.
It has been revealed that this will include funeral costs and any lingering medical costs. A reasonable estimate for a typical funeral is around $20,000.
Recent findings suggest that crazy, right? You can get burial insurance to cover only the most basic of final expenses.
Debt burdens are high in the US, and debt can be especially crushing on remaining family members. Many life insurance customers make sure they can pay off most of their debt with the policy.
Recent findings suggest that medical costs are a serious variable. Even if you have excellent health insurance, there are likely to be unpaid medical bills lingering after your death. This has to do with copayments, deductibles, and coinsurance provisions.
Recent findings suggest that collectively, they can add up to many thousands of dollars. But where things get really complicated is if you die of a terminal illness.
For example, if you are stricken by an illness that lasts for several years, you could incur a number of expenses that are not covered by insurance. This may include the cost of personal care and even experimental treatments.
Sources indicate that A home may be a large asset, but it’s also often a homeowner’s largest debt. The average mortgage balance in the US is roughly $236,443 according to Experian data. So you could easily use a life insurance policy to pay off that debt and relieve your loved ones of a monthly mortgage payment.
Industry observers note that credit card debt and other personal debt are some of the most expensive obligations carrying rates upward of 20% in some cases. Make sure you have enough to cover this very expensive debt.
Below is a sampling of major expenses your family is likely to incur, either on an annual basis or at some point after your death.
It has been revealed that tuition costs continue to skyrocket. The Department of Education suggests that four-year public college tuition has been rising an average of 5% per year, far exceeding the rate of inflation. If you have one child who attends an in-state public school, a second at an out-of-state public school, and a third in a private university, the total expenditure will reach $416,560.
Vehicles and other forms of transportation represent another large sum. Unfortunately, with increasing electronics and safety features, the average cost of a new car continues to grow.
Recent findings suggest that if your family relies on your work for healthcare, take notice. According to eHealth.com, the average health insurance premium for a family is $22,221. That’s a shade under $2,000 per month in additional cost. This cost will only rise, and the need could last for years.
So far, we’ve been describing the financial obligations likely to affect a typical household.But there may be certain situations that will produce obligations that are less obvious.
For example, if you’re a business owner, there may be debts or other financial obligations that will need to be paid upon your death.
Even though no one in your family may be qualified or interested in taking over your business, the payoff of those obligations may be completely necessary to enable the sale of the business.
Another possibility is that you’re a real estate investor.
If your properties are heavily indebted, extra insurance proceeds may be necessary either to carry the properties until they’re sold, or even to pay off existing indebtedness to free up cash flow for income.
You may even need additional funds if you are taking care of an extended family member, like an aging parent.
These are just some of the many possibilities of expenses that will need to be covered by insurance proceeds.
Before we move on to specific life insurance quotes, let’s first consider the factors that affect term life insurance premiums.
Recent findings suggest that this is typically the single most important premium factor. The older you are, the more likely you are to die within the term of the policy.
This is a close second and why it’s so vital to apply for a policy as early in life as possible. Premiums on life insurances rates literally increase by each year.
In a recent development, if you have any health conditions that may affect mortality, such as diabetes or hypertension, your premiums will be higher. This is another compelling reason to apply while you are young and in good health.
It’s not that policies are not available to people with health conditions, it’s just that they’re less expensive if you don’t have any.
A 10-year term policy will have a lower premium than a 20-year term policy, which will be lower than a 30-year term. The shorter the term, the less likely it is the insurance tech giant will have to pay a claim before it expires.
Size of the policy matters, but not the way you might think. Yes, a $1 million policy will cost more than a $500,000 policy. But it won’t cost twice as much.
The larger the policy, the lower the per-thousand cost will be.
When the size of the death benefit is considered, the larger policy will always be more cost-effective.
In a recent development, for example, certain occupations are more hazardous than others (think policeman versus librarian). Deep-sea diving is higher risk than golf. And smoking is the one activity guaranteed to raise your premiums substantially.
With this information in mind, let’s take a look at whether you should consider a $1 million whole life policy instead.
Any discussion on life insurance should include a comparison of whole life and term life insurance coverage. After all, both products can be immensely valuable in the right situation, yet one product (whole life) costs considerably more than the other.
Most of the time, the debate is settled in favor of term life insurance based on cost alone.
A whole life insurance policy can easily cost 10x the same amount of coverage you can get with a term policy.
It has been revealed that with that being said, whole life insurance and other investment-type life insurance coverage can be valuable in terms of the cash value you can build up over time. Whole life insurance also offers a fixed benefit amount for your heirs that will last for your entire life, yet the cost of your premiums are guaranteed to stay the same.
The cash value of a whole life insurance policy also grows on a tax-deferred basis, and you can borrow against this amount if you need a loan. Further, many whole life policies from reputable providers also pay out dividends during good years, which can be substantial.
The problem with whole life and other similar policies like universal life is the fact that premiums can be exorbitant for the amount of coverage you might need.
A couple with young children provides a good example since they might need a $1 million dollar policy or more to provide income protection for their working years and have money left for college tuition and other expenses.
With young families, expenses are already high.
This includes costs for food for a family, childcare, heavy use of health care, and the seemingly endless demand for clothing, furniture, and even entertainment as the children grow.
As you can see from the cost comparison below from State Farm, there’s not enough room in the typical family budget to afford the type of life insurance that’s needed.
A 40-year-old mother and breadwinner in excellent health would pay $80.09 per month for a term life policy that lasts 20 years, whereas a whole life policy in the same amount would cost $1,266.69 per month (or $14,560 annually).
This is a classic situation where term insurance rides to the rescue. The family can afford to buy the amount of coverage they need at an affordable price, whereas paying for permanent life insurance coverage in the same amount would be difficult to justify.
And just as notable for people of any age and in any circumstance, the extra funds not being spent on insurance premiums can be invested to gradually improve your financial situation.
So absolutely, term insurance will work best for most people.
It has been revealed that as you’ll notice, each table has a wide array of information. Knowing that everybody is in a different situation, I wanted to make sure that I offered term life quotes for almost every conceivable situation.
It has been revealed that I’ve included life insurance rates for a 30-year term, 20-year term, and a 10-year term million dollar life policies. If you’re a tobacco user, I’ve also included some quotes from life insurance for smokers.
For those that think that a million-dollar term policy is expensive, you’ll quickly notice that a 25-year-old male in good health only costs $645 per year while a 35-year-old costs $795.
On a monthly basis that’s almost next to nothing!
There is a major drop-off in life insurance rates between a 20 year and a 30 year since underwriters do not have to worry as much about life expectancy.
For many people, a 20-year policy gets them exactly where they want to be in life when the policy term runs out.
Once again, you get a $200 drop in the annual premium by losing another 10 years on the term.
If your life insurance agent isn’t giving you all these term options and is only focused on the death benefit, then you need a different agent.
Industry observers note that for all you smokers out there – beware! The cost of your life insurance balloons as you’ll see here. If you’re considering kicking the habit, now is as good time as any.
Some life insurance companies will give you a lower rate if you complete a recognized smoking cessation program, and go on without smoking for at least two years.
It won’t help your immediate situation, but when you see the premium on smoker life insurance rates below, you might agree that it’s something to work toward!
If you’ve made the decision that $1 million of life insurance is the right amount of coverage you need and you’re ready to purchase a policy, here are the steps you’ll need to follow.
1. Determine How Much Coverage You Need: This is the first and most important step in securing a million life insurance policies. You need to have a clear understanding of how much coverage you actually need.
2. Choose the Right Type of Policy: There are whole life, term life, and Universal life policies available. Choose the one that best suits your needs.
It has been revealed that 3. Shop Around: Don’t just go with the first life insurance tech giant you come across. It’s vital to compare life insurance rates and coverage from a few different companies before making a decision.
4. Consider Your Health: If you’re in good health, you’ll likely qualify for lower rates. However, if you have health complications, you may still be able to get coverage, but it will probably be more expensive.
Industry observers note that 5. Consider Your Lifestyle: If you have a risky job or hobby, that could affect your rates.
6. Get Quotes From Multiple Companies: This is the best way to compare rates and find the cheapest policy.
It has been revealed that 7. Read the Fine Print: Make sure you understand all the terms and conditions of the policy before buying it.
8. Buy Online: You can usually get cheaper rates by buying life insurance online.
It has been revealed that 9. Pay Attention to Your Payment Schedule: Most life insurance policies require monthly or annual payments. Be sure you can afford the payments before buying a policy.
According to recent reports, 10. Review Your Policy Regularly: Life changes, and so do life insurance needs. Be sure to review your policy regularly to make sure it still meets your needs.
Following these steps will help you get the best possible rate on a million-dollar life insurance policy.
In a recent development, make sure you understand all the terms and conditions before signing on the dotted line. Also, make sure to shop around and compare rates from multiple companies before buying a policy.
Yes, I know I’ve said that a few times in this article, but it’s worth repeating. Many people go with the first life insurance company they call, and that isn’t kind to their checkbook. It pays to shop around.
Here’s what you need to know about choosing the best life insurance manufacturer for your $1 million policy:.
In a recent development, when choosing the best life insurance organization, it’s important to consider the overall financial health of the insurance company. You want to make sure the company you choose is stable and will be around for years to come. You also want to consider things like the company’s customer service rating and claims-paying ability.
In a recent development, there are a lot of different life insurance companies out there, so it can be difficult to know which one is the best. Each manufacturer is rated by different organizations, so it’s crucial to look at multiple ratings before making a decision.
Rating agencies are the “Report Card” for life insurance companies. Choose a company with straight A’s!
The companies that rate insurance companies are A.M. Best, Moody’s, and Standard & Poor’s.
A.M. Best is a credit rating agency that specializes in the insurance industry. They rate insurance companies on their financial stability.
Sources indicate that moody’s is another credit rating agency. They also rate insurance companies on their financial stability.
Standard & Poor’s is a credit rating agency that rates companies on their financial stability.
Sources indicate that the following life insurance companies are all rated A+ (Superior) by A.M. Best and are considered to be financially stable and have a good claim-paying ability.
Here are those same top life insurance companies with their respective ratings:.
These are just a few of the many life insurance companies out there that could provide you with a $1 million life insurance policy.
In a recent development, when choosing a life insurance tech giant, it’s important to consider their financial stability, customer service rating, and claims-paying ability. The companies listed above are all rated A+ (Superior) by A.M. Best and are considered to be financially stable with a good claims-paying ability.
Northwestern Mutual, New York Life, MassMutual, Guardian Life, State Farm, Nationwide, USAA, MetLife, The Hartford, and Allstate are all good choices for life insurance companies.
You can’t put a price on peace of mind, and with a $1 million life insurance policy you can have the peace of mind knowing that your loved ones will be taken care of financially if something happens to you.
Getting a one-million-dollar term life insurance policy is not as expensive as most people believe. You can start getting quotes today from a variety of top life insurers by selecting your state from the map above.
Even those who opt for the more expensive permanent life insurance policy will many times be surprised at the price.
Recent findings suggest that either way, you can get these larger amounts of coverage and still not break the bank. But get your policy now, while you’re still young and in good health.
The cost of a $1,000,000 life insurance policy will vary based on factors like your age, health, and lifestyle. However, you can expect to pay around $250 per year for a healthy 30-year-old. According to Ladder Life, a $1 million term life policy for healthy 30-year-old males costs around $2.08 per day.
Industry observers note that A $1 million term life insurance policy is a type of life insurance that provides coverage for a specific period of time, usually 10-20 years. If you die during the term of the policy, your beneficiaries will receive a death benefit of $1 million. If you live past the term of the policy, the policy will expire and you will not receive any death benefit. A $1 million term life insurance policy is a good choice for people who want to make sure their loved ones are taken care of financially if something happens to them. It can also be a good choice for people with a lot of debt, like a mortgage or student loans, that they want to make sure is paid off if they die.
For the most part, yes; but there are examples of people who cannot buy life insurance. For instance, people with a terminal illness or those who have been diagnosed with a life expectancy of fewer than two years are not able to purchase life insurance policies. The other factors are your income, affordability, and suitability. If you cannot afford the premiums, then you will not be able to purchase the policy. And if your income is say less than $50,000 then the insurance company may not think it’s suitable to purchase a $1 million life insurance policy.
A million-dollar life insurance policy may not be right for everyone, but it can be a good idea if you have a lot of debt or if you want to make sure your family is taken care of financially if something happens to you. No one likes to think about their death, but it’s important to have a life insurance policy in place in case something happens to you. A million-dollar life insurance policy can give you and your loved one’s peace of mind knowing that they will be taken care of financially if something happens to you.
Sources indicate that there is no one-size-fits-all answer to this question, as the best policy for you will depend on your specific needs and preferences. However, some of the top providers of million-dollar life insurance policies include AIG, Banner Life, and Prudential. So be sure to explore your options and compare quotes from different providers before making a decision.
It has been revealed that yes, insurance companies offer million-dollar insurance policies with no medical exam. However, the premiums for these policies are typically much higher than for policies with a medical exam.
Recent findings suggest that john Hancock (n.d.) Life insurance: what's your number? https://www.johnhancock.com/ideas-insights/how-much-life-insurance-do-you-need.html.
eHealth.com (2022, Oct 27) How Much Does Health Insurance for Families Cost? https://www.ehealthinsurance.com/resources/individual-and-family/much-health-insurance-families-cost.
Farm Bureau Financial Services (2020, Aug 4) 8 Factors That Can Affect Life Insurance Premiums https://www.fbfs.com/learning-center/8-factors-that-can-affect-life-insurance-premiums.
Insurance Information Institute, Inc (n.d.) How to assess the financial strength of an insurance company https://www.iii.org/article/how-to-assess-the-financial-strength-of-an-insurance-company.
Experian (2023, Mar 27) Total Mortgage Debt Increases to $11.2 Trillion in 2022 https://www.experian.com/blogs/ask-experian/how-much-americans-owe-on-their-mortgages-in-every-state/.
National Center for Education Statistics (n.d.) Tuition costs of colleges and universities https://nces.ed.gov/fastfacts/display.asp?id=76.
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance book Soldier of Finance. He was a financial planner for 16+ years having founded, Alliance Wealth Management, a SEC Registered Investment Advisory firm, before selling it to focus on his passion - educating the masses on the importance of financial freedom through this blog, his podcast, and YouTube channel. Jeff holds a Bachelors in Science in Finance and minor in Accounting from Southern Illinois University - Carbondale. In addition to his CFP® designation, he also earned the marks of AAMS® - Accredited Asset Management Specialist - and CRPC® - Chartered Retirement Planning Counselor. While a practicing financial advisor, Jeff was named to Investopedia's distinguished list of Top 100 advisors (as high as #6) multiple times and CNBC's Digital Advisory Council. Jeff is an Iraqi combat veteran and served 9 years in the Army National Guard. His work is regularly featured in Forbes, Business Insider, Inc.com and Entrepreneur.
General
⚖️ Neutral
🌐 Moneycrashers
#21711. GasBuddy Review – Free Price Map and a Card for Debit Payers
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (252 w)
GasBuddy Review – Free Price Map and a Card for Debit Payers
📅 16 Nov 2026 | ⏱️ 1 min read (252 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Use GasBuddy for its free, driver-reported gas prices, and add its Pay with GasBuddy+ card only if you pay for gas by debit.
- That makes GasBuddy’s free app and website the part most drivers need, since they show the gas prices other drivers report so you can compare nearby stations before you fill up.
- Sources indicate that debit payers gain at least 3 cents a gallon from the free card, and by our math Plus’s extra 17 cents a gallon over the free card covers its $89 yearly fee at about 44 gallons a month.
Use GasBuddy for its free, driver-reported gas prices, and add its Pay with GasBuddy+ card only if you pay for gas by debit. The card’s base discount is 3 cents a gallon, while a credit card paying 3% back on gas earns 12 cents on a $4 gallon, and you can’t use both on one fill-up.
That makes GasBuddy’s free app and website the part most drivers need, since they show the gas prices other drivers report so you can compare nearby stations before you fill up.
Sources indicate that debit payers gain at least 3 cents a gallon from the free card, and by our math Plus’s extra 17 cents a gallon over the free card covers its $89 yearly fee at about 44 gallons a month. Credit card payers should use the free map to pick the station and pay with a gas credit card that earns 3% or more.
Learn more about GasBuddy or see how it compares to the best gas apps.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
It has been revealed that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.
General
⚖️ Neutral
🌐 Moneycrashers
#21710. Shell Fuel Rewards Review – 5¢ a Gallon for Shell Regulars
📅 16 Nov 2026 • ⏱️ 1m • 📖 Standard (264 w)
Shell Fuel Rewards Review – 5¢ a Gallon for Shell Regulars
📅 16 Nov 2026 | ⏱️ 1 min read (264 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~1 mins left to finish
📖 0% read
💡 Key Takeaways
- Join Shell Fuel Rewards if most of your gas comes from Shell, since the free program takes 5 cents a gallon off every fill-up for drivers who buy 10 gallons or more there six times a quarter.
- For an average car or SUV buying all its gas at Shell, those 5 cents a gallon come to about $21 a year on the 423 gallons it burns, by the Federal Highway Administration’s count.
- Sources indicate that drivers who already buy 10 gallons or more at Shell six times a quarter get the program’s 5 cents a gallon for nothing.
Join Shell Fuel Rewards if most of your gas comes from Shell, since the free program takes 5 cents a gallon off every fill-up for drivers who buy 10 gallons or more there six times a quarter. When another station on your route undercuts your Shell by more than your discount, fill up there instead.
For an average car or SUV buying all its gas at Shell, those 5 cents a gallon come to about $21 a year on the 423 gallons it burns, by the Federal Highway Administration’s count. Paying with Shell S Pay from a checking account raises the discount to 10 cents, about $42, in place of whatever a credit card would earn on that gas.
Sources indicate that drivers who already buy 10 gallons or more at Shell six times a quarter get the program’s 5 cents a gallon for nothing. Drivers without a Shell on their routes should check a gas price app and fill up at the cheapest station instead.
Learn more about Shell Fuel Rewards or see how it compares to the best gas apps.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every tech giant or offer available in the marketplace.
General
📈 Bullish
🌐 Moneycrashers
#21709. Best Gas Apps – Find the Cheapest Station, Then Save Again at the Pump
📅 16 Nov 2026 • ⏱️ 2m • 📖 Standard (483 w)
Best Gas Apps – Find the Cheapest Station, Then Save Again at the Pump
📅 16 Nov 2026 | ⏱️ 2 min read (483 words, 📖 Standard) | Source: Moneycrashers
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- Find the cheapest gas station on your route with GasBuddy’s free price map, then trim what you pay there.
- In a recent development, the two steps work together because gas apps do different jobs.
- Industry observers note that an average car or SUV burned 423 gallons in 2024, by the Federal Highway Administration’s count.
Find the cheapest gas station on your route with GasBuddy’s free price map, then trim what you pay there. Claim an Upside offer if the station takes part, use Checkout 51 if you already scan grocery receipts in it, and join Shell Fuel Rewards if Shell is your usual stop.
In a recent development, the two steps work together because gas apps do different jobs. Each pick here does one of them best for a particular driver. A price map demonstrates the prices drivers report at nearby stations, so you can compare stations before you fill up and pick the cheapest one on your route. The other apps cut what you pay at the station you choose, with cash back on an offer you claim before you pump or a discount at one brand’s stations.
Industry observers note that an average car or SUV burned 423 gallons in 2024, by the Federal Highway Administration’s count. That makes every 5 cents off a gallon worth about $21 a year. Claim one cash back offer per fill-up, since Upside pays nothing on a fill-up that Checkout 51 or GasBuddy already paid cash back on.
Check its map before you claim a cash back offer, since a station with no offer can still cost less than one with an offer, even counting the cash back.
For more information, read our full GasBuddy Review.
Commuters who pass several participating stations do best with it, since each station funds its own offer and the app shows every offer nearby before you pump.
For more information, read our full Upside Review.
It belongs here for drivers who already upload grocery receipts to it, since they can claim its gas offers without adding another app.
For more information, read our full Checkout 51 Review.
Drivers who buy 10 gallons or more at Shell about twice a month keep its 5-cent Gold discount, which still applies with an Upside offer, though Upside may trim that offer.
For more information, read our full Shell Fuel Rewards Review.
Sources indicate that checking prices saves money before you choose a station, and a cash back offer or a loyalty discount adds to those savings once you’re there. Before each fill-up, open the price map, then claim an offer or enter your loyalty number at the station you pick.
For a card that earns on every fill-up, compare the best gas credit cards.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every tech giant or offer available in the marketplace.
General
⚖️ Neutral
🌐 Goodfinancialcents
#21708. How to Make Money Without a Job: 26 Ways to Earn Money Outside the 9-5
📅 29 Aug 2023 • ⏱️ 17m • 📚 Deep Dive (3395 w)
How to Make Money Without a Job: 26 Ways to Earn Money Outside the 9-5
📅 29 Aug 2023 | ⏱️ 17 min read (3395 words, 📚 Deep Dive) | Source: Goodfinancialcents
⏱️ ~17 mins left to finish
📖 0% read
💡 Key Takeaways
- Home » Make Money » How to Make Money Without a Job: 26 Ways to Earn Money Outside the 9-5.
- In a recent development, breaking free from the traditional 9-5 is more achievable than ever with these 26 innovative income streams.
- Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
Home » Make Money » How to Make Money Without a Job: 26 Ways to Earn Money Outside the 9-5.
In a recent development, breaking free from the traditional 9-5 is more achievable than ever with these 26 innovative income streams. Ready to redefine your concept of earning?
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
Colin Graves is a personal finance writer and editor with a client list that includes some of the most prominent...
In a recent development, goodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Fresh York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Newly introduced York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
It has been revealed that are you trying to win the Mega Millions, but your numbers never seem to come up? It may be time to look for better ways to make money. Fortunately, you can earn extra cash without going and getting a “real job.”.
According to recent reports, what are the best ways to avoid sitting in a cubicle all day? Some money-making strategies require an upfront investment, while others let you earn money in your free time with the help of apps.
Read on to learn the best ways to earn cash without a regular 9-5 job, plus tips on how almost anyone can get started.
In a recent development, one of the easiest ways to earn money is by signing up to participate in market research studies. You won’t make much, a few dollars here and there, but you can create a free account and get started within minutes.
You’ll be paid in PayPal cash or gift cards for sharing your opinion and completing other tasks online.
E-Poll Market Research is one of the top companies to consider for this type of work. They make it easy to create an account and answer survey questions.
However, there are plenty of other options to consider, including:.
While market research gigs won’t make you rich, it’s something you can do during your spare time.
Industry observers note that if you have a book idea, turning your story into an eBook can help you earn passive income without a regular job. Kindle Direct Publishing can even help you format your book for Kindle, at which point you can market and sell your book to millions of potential readers who shop on Amazon.com.
In a recent development, how much can you earn writing eBooks? That depends on how many books you write, how much you sell them for, and how successful you are at marketing your book. Selling 20 books per month with a profit of $7 per book would net you $140 per month and $1,680 per year.
Meanwhile, selling 100 books per month at $7 per book would net you $700 per month and $8,400 per year. Need a little inspiration? Here’s an article that indicates you how to make your first $1,000 selling eBooks.
Industry observers note that you can earn a lot of money by starting a blog or niche website and monetizing it. I should know. I started Good Financial Cents more than a decade ago, and have earned millions of dollars through the monetization of this site since its earliest days.
How do you make money blogging? Earning real income with a website isn’t as easy as it looks, but there are plenty of monetization strategies you can try.
Here are the most common ways blogs make money:.
If you’re curious about what it takes to earn money blogging, consider signing up for my Make 1K Challenge. It’s free and can help you earn your first $1,000 online with some of the blog monetization strategies I’ve already mentioned.
In a recent development, you could argue that freelance work is like a regular job, but working at home and on your terms is much different from traditional employment. The fact is, most freelancers are fully remote – they can work from anywhere in the world with a laptop and an internet connection.
Plus, they can hire and fire clients based on their personal needs and preferences, and their income potential is unlimited. According to ZipRecruiter, freelancers in the U.S. average $63.53 per hour.
Of course, you’ll need a marketable skill to find paid work as a freelancer. This could be freelance writing, design skills, marketing expertise, or something else.
You can use several websites to market your skills as a freelancer, including:.
HealthyWage makes it possible to earn money while you lose weight. You won’t earn a ton of cash through the app, but you can earn a few dollars and use it to supplement other income you have.
The more weight you lose, the more money you can make. For example, the HealthyWage website claims some of their clients who lost more than 100 pounds managed to earn anywhere from $1,400 to $3,000.
However, the HW weight loss calculator shows potential earnings of $578 to $828 for people who only have 15 pounds to lose.
According to recent reports, if you have a car you rarely use and want to earn some side income, you can consider renting it out with Turo, a ride-sharing platform that connects car owners with people who need a short-term rental. You can set your price, although you’ll have more success if you price your car competitively.
Nicer vehicles in high-demand areas can easily fetch rates that surpass $100 per day through this platform. Turo notes that in-demand cars rented out regularly can bring in anywhere from $10,000 to $20,000 per year in net profit.
Plus, almost anyone can rent out their car provided it meets the guidelines of the Turo platform. Your car must be 12 years old or newer with less than 130,000 miles. It must be worth less than $200,000 (no Lambo’s), and you must also meet Turo’s auto insurance requirements.
Industry observers note that do you have a spare bedroom in your home that you never use? Maybe you have a basement or garage apartment you could fix up and begin renting for a profit?
According to recent reports, either way, Airbnb lets you rent out rooms and other spaces in your home on any dates you prefer. You must let renters know they’re renting a room in a home vs. an entire apartment or house and provide as much additional detail as possible.
In a recent development, the amount you can earn will depend on where you live and the type of accommodation you can offer. However, expensive cities like Chicago, Newly introduced York, and San Francisco have plenty of rooms for rent that go for well over $100 per night.
You may not have an entire room you can rent, but even if you have some storage space, Neighbor.com allows you to rent it out to others in need.
Common spaces rented through this platform include.
According to recent reports, the Neighbor.com platform makes it easy to advertise your unused space so that people nearby can inquire if they’re interested. Also, note that the platform offers insurance that can protect you if some of your client’s items are damaged or stolen while in your care.
How much can you make renting out extra space? It depends on how much space you have to rent and where it’s located. However, Neighbor.com highlights a range of rental space options that cost anywhere from $20 to $100+ per month.
Investing in dividend stocks is one of the best ways to earn money without a regular job. Many early retirees find a way to live and pay bills based solely on the dividends they receive from various stocks.
But what exactly is a dividend stock? For the most part, they are regular stocks but with a track record of sharing their profits with investors through dividends.
Dividends can also be earned in exchange-traded funds (ETFs) or mutual funds, and they can be significant once you build up a large portfolio.
It has been revealed that since dividends are paid by profitable companies, they tend to be seen as less risky for investors. If you’re curious about what it takes to get started with this strategy, this post explains how to invest in dividend stocks.
In a recent development, housesitting is an option if you’re somewhat mobile and can move from place to place. Generally, you can find house-sitting gigs through word of mouth, referrals, or online portals like Craigslist.org or Facebook Marketplace.
It has been revealed that that said, not all house-sitting gigs are paid. Some offer the potential for exotic travel instead and free lodging for a week to several months.
Either way, a website called TrustedHousesitters is the best place to find house-sitting gigs. Some jobs posted are for house-sitting only, while others require house sitters to provide basic care for pets or plants.
Recent findings suggest that if you have serious wanderlust and want to travel far and wide, this platform can help make it happen. Many gigs posted online are in countries like Australia, Ireland, France, and Switzerland.
If you love animals and want to earn money taking care of them, several platforms can help turn your dream into a reality.
For example, Rover.com lets you provide basic care for dogs or cats in your home, or you can pick up dog walking gigs. Another mobile app, called Wag!, lets you do more of the same.
You can set your rates for all types of work through these platforms, and your availability. While earnings vary by location and job, most people watch dogs and cats for anywhere from $40 to $100 per night.
According to recent reports, real estate investing may seem like a pipe dream if you hope to earn income without a job but hear me out. There are many ways to earn income through real estate without owning physical property or dealing with the hassles of being a landlord.
According to recent reports, you can invest in real estate investment trusts (REITs) that let you build wealth over time. You can also use a platform called Fundrise to invest in real estate with a minimum investment of $10.
Fundrise lets you purchase eREITs, large investment funds that acquire, own, or operate multi-residential and commercial properties. The income you earn is entirely passive since it handles the work of finding income-producing properties and managing them.
Sources indicate that while returns are never guaranteed, Fundrise investors have achieved very solid returns. Investors who use the platform earned an average return of 7.31% in 2020, followed by 22.99% in 2021, 1.50% in 2022 and -7.45% in 2023 (their first down year).
It has been revealed that you can earn income on your spare change by investing it using Acorns. The roundup savings app syncs to your debit or credit card rounds up every purchase you make to the nearest dollar, and invests the difference. Once it’s set up, there’s no work on your part.
In a recent development, most of the money is invested in ETFs and managed by the world’s top investment firms like Vanguard and BlackRock. While this app makes it easy to invest small amounts of money, it’s not free to use. Personal plans start at $3 per month, while a family plan costs just $5.
If you’re looking for some paid gigs that are relatively easy, consider setting up a profile on TaskRabbit, an online platform that lets you get paid for completing various tasks, such as:.
According to recent reports, projects typically pay between $30 and $100, although some pay significantly more than that. TaskRabbit also lets you pick and choose the jobs you want to take on based on your availability so that you can work entirely on your schedule.
If you love taking photographs and have a knack for getting professional-looking images, you can use your skills and expertise to sell photos online.
Websites like Depositphotos and iStockPhoto pay photographers to supply them with stock photos they can sell to writers, publications, and various online platforms.
Sources indicate that the best part about this side hustle is that you can get started with the equipment you already have. While you can use a professional camera if you want to, many smartphones take professional-quality photos.
Earning a bank bonus is another way to earn money without a regular job, but you’ll need an upfront investment to get started. Most bonus offers require you to deposit a specific amount of money and keep it in your account for up to 12 months.
You may also be required to set up direct deposit to earn a bank bonus, and other terms and conditions may apply.
Recent findings suggest that where can you find the best bank bonuses? While bonus offers constantly change, you can start by checking with banks like Chase, HSBC, Radius Bank, and Wells Fargo.
Flipping furniture requires some upfront legwork and potentially even some artistic talent, but you can earn a solid income with this strategy if you know what you’re doing.
Essentially, this side hustle requires you to shop at thrift stores, garage sales, and online platforms to find furniture that will ultimately sell for more than you paid.
From there, you can sell the furniture as-is or clean it up and paint it with the goal of fetching an even higher price.
You can make money driving for Uber or Lyft on your own time, picking and choosing the days and hours you want to work.
Not only is rideshare work one of the most flexible side hustles, but you can earn $20 per hour and more with tips.
If you are low on free time but still want to make money without a job, consider selling stuff you don’t need. An array of online platforms makes it a breeze, although some platforms work better for selling.
For example, you can use Poshmark to earn money selling used clothing and accessories, while used electronics tend to sell best on platforms like eBay.com, Decluttr, BuyBackWorld, and Gazelle.
If you have home decor, furniture, or workout equipment to sell, you’ll almost always do better unloading those items locally on Facebook Marketplace.
Sources indicate that starting a YouTube channel is another way to earn money without a job, but that doesn’t mean it’s not work. The fact is, that creating quality videos and building an audience takes a lot of creativity and time. Plus, not everyone who tries to build a YouTube channel will succeed.
That mentioned, you can earn income without a regular job. I know because I have done it with my YouTube channel, Wealth Hacker.
Industry observers note that how much you can earn on YouTube varies quite a bit, but it’s possible to earn thousands of dollars per month. If you’re curious about monetizing videos, my in-depth guide will show you how to make money on YouTube.
Sources indicate that donating plasma is a unique way to earn money without a job, although it’s not very glamorous. DonatingPlasma.org makes it easy to find plasma donation centers in your area, and you can earn as much as $100 for your first donation.
Recent findings suggest that that said, subsequent plasma donations typically earn closer to $50. You’ll also be limited by the number of times you can donate plasma within a month. However, it’s possible to use this side gig to earn an extra $500 per month, which you can use to supplement your primary income.
In a recent development, if you are willing to complete various tasks that help regular workers do their jobs, consider becoming a crowd worker. This gig will have you finishing up to-do lists of jobs that don’t require specific technical skills.
For example, you may get paid to proofread documents, label images, enhancement a resume, complete a form, or complete a data entry assignment.
Several platforms help you find crowd-working gigs, but the best ones include Microworkers and Clickworker.
If you want to do something simple that will get you moving, consider delivering groceries using apps like Instacart or Shipt. You get paid hourly, plus tips and all you have to do is head to the store, purchase groceries according to a list, and deliver them to people in your neighborhood.
The gig is extremely flexible, similar to driving for Uber or Lyft.
Another non-job gig lets you get paid to deliver packages for Amazon.com. You can do this through a platform called Amazon Flex, which promises its drivers anywhere from $18 to $25 per hour.
Unlike a regular Amazon job, Flex lets you pick the day and the hours you want to work. To get started, you need to create a free account, get approved, and start reserving blocks of time you want to deliver packages.
Industry observers note that finally, you can earn money by selling unwanted or unused gift cards in your possession. This hustle is made easy thanks to platforms like GiftDeals.com and CardCash.com.
According to recent reports, you won’t get the total value of your gift cards, but you should get 90% or more of the gift card balance for each card you sell. While selling gift cards for less than their total value may not seem ideal, it’s better than not using them and getting nothing in return.
In a recent development, finally, you can earn small amounts of money by signing up with the best online survey sites. Not only is this side hustle as easy as it gets, but you can participate and get paid during your spare time and even on your phone.
Other online survey sites to check out include the following:.
There you have it, 26 ways to make money without a job. While many of the jobs on our list won’t replace your 9-5, they can be a great way to increase your income so you can pay off debt or break the cycle of living paycheck to paycheck.
Check out the video below if you’re looking for even more ways to make money.
ZipRecruiter (n.d.) Freelance Salary https://www.ziprecruiter.com/Salaries/Freelance-Salary.
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance book Soldier of Finance. He was a financial planner for 16+ years having founded, Alliance Wealth Management, a SEC Registered Investment Advisory firm, before selling it to focus on his passion - educating the masses on the importance of financial freedom through this blog, his podcast, and YouTube channel. Jeff holds a Bachelors in Science in Finance and minor in Accounting from Southern Illinois University - Carbondale. In addition to his CFP® designation, he also earned the marks of AAMS® - Accredited Asset Management Specialist - and CRPC® - Chartered Retirement Planning Counselor. While a practicing financial advisor, Jeff was named to Investopedia's distinguished list of Top 100 advisors (as high as #6) multiple times and CNBC's Digital Advisory Council. Jeff is an Iraqi combat veteran and served 9 years in the Army National Guard. His work is regularly featured in Forbes, Business Insider, Inc.com and Entrepreneur.
General
⚖️ Neutral
🌐 Choosefi
#21707. Breaking: Avianca LifeMiles → Star Alliance Premium Cabin
📅 04 Nov 2026 • ⏱️ 14m • 📚 Deep Dive (2848 w)
Breaking: Avianca LifeMiles → Star Alliance Premium Cabin
📅 04 Nov 2026 | ⏱️ 14 min read (2848 words, 📚 Deep Dive) | Source: Choosefi
⏱️ ~14 mins left to finish
📖 0% read
💡 Key Takeaways
- One of the cheapest ways to fly Star Alliance business and first class.
- Sources indicate that picture this: you settle into a Lufthansa Boeing 747-8 business class seat on the upper deck, somewhere over the Atlantic, a glass of Champagne in hand, your fully flat bed already made up behind you.
- The core insight here is understanding why Avianca LifeMiles prices Star Alliance awards so aggressively — and then understanding how to get points into the program quickly enough to actually use them.
One of the cheapest ways to fly Star Alliance business and first class.
Points for Business/First Class.
Sources indicate that picture this: you settle into a Lufthansa Boeing 747-8 business class seat on the upper deck, somewhere over the Atlantic, a glass of Champagne in hand, your fully flat bed already made up behind you. Latest York to Frankfurt — a route that commands $4,000 to $8,000 in cash for a business class ticket — and you're here for 63,000 Avianca LifeMiles. No fuel surcharges. No carrier-imposed fees eating into your redemption. Just the experience. That's the moment the FI community lives for. Not the luxury itself — though Lufthansa's business class product is genuinely exceptional — but the *math*. The realization that the loyalty system has a pricing gap so wide you could fly a 747 through it. Here's what the numbers actually mean. At the low end, a $4,000 business class ticket redeemed for 63,000 points works out to **6.3 cents per point (CPP)**. At the high end — peak travel season, last-minute pricing, transatlantic demand — that same seat hits $8,000 in cash, which means your LifeMiles are delivering **12.7 cents per point**. For context, most travel rewards experts consider 1–2 CPP a baseline for points value. You're achieving 6 to 12 times that baseline. The reason this feels like a genuine inefficiency rather than just a deal: Avianca LifeMiles prices Star Alliance awards on a **fixed award chart** that doesn't fluctuate with cash fare demand. When airlines raise transatlantic business class fares during summer holidays or major events, your points cost stays exactly the same. The gap between what the market charges and what LifeMiles charges simply grows wider. And then there's the no-fuel-surcharge policy — the detail that separates LifeMiles from competitors like British Airways Avios, which can pile $600+ in carrier surcharges onto a single redemption. With LifeMiles, you pay government taxes only, typically $50–$150 for a transatlantic itinerary. That's it. For the ChooseFI community, this redemption represents exactly the kind of asymmetric value that underpins a great travel rewards strategy: use points where cash prices are highest, eliminate fees wherever possible, and fly a product you'd never justify paying full price for — because you didn't have to.
The core insight here is understanding why Avianca LifeMiles prices Star Alliance awards so aggressively — and then understanding how to get points into the program quickly enough to actually use them.
Avianca is a Star Alliance member, which means it has reciprocal award booking agreements with every other Star Alliance carrier — United, Lufthansa, Swiss, ANA, EVA Air, Singapore Airlines, and more. Like all alliance programs, LifeMiles can sell award seats on partner airlines. The pricing is set by Avianca's own award chart, not by Lufthansa's chart or United's chart.
Recent findings suggest that this is the pricing inefficiency. Lufthansa's own frequent flyer program (Miles & More) charges over 100,000 miles for the same transatlantic business class route and layers on fuel surcharges. United MileagePlus charges 70,000–88,000 miles for the same seat. Avianca LifeMiles charges 63,000 miles with zero carrier surcharges. Same seat. Same plane. Wildly different cost.
Avianca keeps rates competitive because they want their program to be attractive to non-Avianca flyers — it's a revenue play. And because their route network is South America-focused, they've built a powerful award program that earns loyalty from customers who may never set foot on an Avianca plane.
Many programs claim no surcharges, then quietly pass through "carrier-imposed fees" that look indistinguishable from surcharges. LifeMiles is one of the genuine exceptions. On partner award bookings — including Lufthansa, Swiss, and other carriers that traditionally levy heavy surcharges — LifeMiles charges only government taxes. For a JFK–FRA business class award, expect to pay roughly $50–$150 out of pocket. That's the full cash outlay.
Industry observers note that this is where the transfer partner ecosystem matters. LifeMiles accepts transfers from:.
The instant Citi transfer is particularly powerful: if you find available award space today, you can move points and call LifeMiles to book within the same session. Capital One and Bilt are nearly as fast. Marriott's 3:1 ratio makes it less efficient unless you have a large Bonvoy balance and no better option.
LifeMiles runs frequent purchased miles sales, often 100%+ bonus miles on purchases. This is a legitimate strategy for topping off your balance when you're a few thousand miles short of a redemption. Combined with transfer partners, it creates significant flexibility. Watch for promotions at lifemiles.com — they typically appear 6–8 times per year.
Sources indicate that the golden rule of any points transfer: never transfer miles until you've confirmed award availability. LifeMiles miles are non-refundable once transferred, and award space can disappear in hours.
United MileagePlus has one of the best Star Alliance partner award search tools available to the public. Go to united.com, start a search as if you're booking an award ticket, and look for business class availability on Lufthansa or Swiss flights on your target route. United displays Lufthansa partner space accurately in most cases. You're looking for "saver" level availability — marked as "X" class on Lufthansa.
Lufthansa's own website (lufthansa.com) sometimes reveals availability that United misses, and vice versa. Search both. You're not booking here — just confirming the seat exists.
According to recent reports, an ExpertFlyer subscription ($10/month) lets you set availability alerts for specific routes and dates. For a high-value redemption like this, it's often worth one month of the service to monitor your target window.
LifeMiles opens its booking window 355 days in advance. For peak travel periods — summer transatlantic, major European events — set a calendar reminder to search at the 355-day mark. Business class award space on Lufthansa releases in small batches and fills quickly.
Transfer exactly what you need — 63,000 miles for a one-way business class transatlantic award — plus a small buffer of 2,000–3,000 miles for potential routing variations.
Go to lifemiles.com and search your award. The website has improved but can still be inconsistent with partner availability display. If the online search doesn't show the space you found on United.com, call LifeMiles directly at their customer service line. Have your flight numbers, dates, and cabin class ready. Phone agents can access and book partner availability that the website sometimes fails to display.
According to recent reports, after booking, you'll receive a confirmation email with a PNR (record locator). Verify this on the operating carrier's website — go to lufthansa.com or swiss.com and look up your reservation using the PNR. If it pulls up correctly, your booking is solid. Save this confirmation and check it once more 72 hours before departure.
It has been revealed that avianca LifeMiles uses a distance-based award chart for Star Alliance partner flights, and their chart is consistently 15-40% cheaper than competing programs for the same seats. The reason is strategic: Avianca wants to attract members to its loyalty program, and aggressive pricing on aspirational redemptions is how they compete with larger alliances. For you, this means the exact same Lufthansa First Class seat or ANA business class seat costs significantly fewer points when booked through LifeMiles versus through United MileagePlus or the carrier directly. The catch is that LifeMiles availability depends on the operating carrier releasing award space to partners, so you still need to search on the carrier or United.com before transferring.
Sources indicate that card links may earn ChooseFI a commission. See our advertiser disclosure.
Let's walk through a real redemption so you can see exactly what this looks like in practice.
The Route: Latest York JFK → Frankfurt FRA, nonstop The Aircraft: Lufthansa Boeing 747-8, upper deck business class The Cash Price: $6,500 (a realistic peak-season transatlantic business class fare) The Points Cost: 63,000 Avianca LifeMiles Out-of-Pocket Fees: ~$85 in government taxes CPP Achieved: 10.3 cents per point.
You've transferred 63,000 Citi ThankYou points to LifeMiles — instantly — spotted the award space on United.com the morning it opened, called LifeMiles to confirm, and had your booking locked in within 90 minutes of finding the seat.
Recent findings suggest that lufthansa's 747-8 upper deck business class is one of the most iconic products in commercial aviation. The upper deck seats — in a 2-2-2 configuration — sit quieter and smoother than the main deck, with fewer passengers and a more intimate cabin feel.
Recent findings suggest that your seat converts to a fully flat bed of approximately 6 feet. You'll have direct aisle access (depending on your seat selection), a large personal entertainment screen, and Lufthansa's catering, which consistently ranks among the top transatlantic carriers. The meal service on JFK–FRA is legitimate: a proper multi-course dinner, a breakfast service as you approach Germany, and a snack menu available throughout.
Industry observers note that before you board, you'll have access to Lufthansa's business class lounge at JFK — typically the Lufthansa Business Lounge or, depending on timing, the partner lounge. Hot food, showers, and a genuine departure experience that costs nothing beyond the taxes you've already paid.
The flight itself is roughly 7.5 hours. In a flat bed, that's a real night's sleep — or close enough. You arrive in Frankfurt rested, which matters whether you're connecting onward or starting your trip immediately.
For the ChooseFI community: this is the redemption that pays for the honeymoon, the milestone anniversary trip, or the family adventure you've been planning since you first discovered travel rewards. The $6,500 you didn't spend stays in your index funds.
It has been revealed that book at the 355-day mark for peak dates. Lufthansa releases a small number of partner award seats when the schedule opens. The travelers who get summer business class awards are almost always the ones who searched on day 355. Set a calendar alert. Be ready.
Use Citi ThankYou for time-sensitive bookings. Because Citi transfers to LifeMiles are instant, you can find award space and complete your booking in a single session. This matters when you're racing to secure a specific seat before someone else grabs it.
Watch for LifeMiles purchased miles promotions. If you're 10,000–15,000 miles short of a redemption, purchasing miles during a 100% bonus promotion can effectively cost you 0.5–0.7 cents per mile — still leaving you with excellent overall CPP on the redemption. Check lifemiles.com regularly or set a Google Alert for "LifeMiles promotion.".
Verify your booking on the operating carrier's website. After booking through LifeMiles, always look up your PNR on lufthansa.com or swiss.com. If it appears correctly, your seat is real. If it doesn't, call LifeMiles immediately.
Recent findings suggest that search Swiss as an alternative to Lufthansa. Swiss International Air Lines is also a Star Alliance member, also bookable through LifeMiles at the same rates, and also operates excellent business class products on transatlantic routes. Swiss often has more partner award availability than Lufthansa on certain dates.
Industry observers note that never transfer points before confirming availability. This is the most common — and most expensive — mistake in travel rewards. LifeMiles does not allow re-transfers out of the program.
Industry observers note that don't ignore the miles expiry policy. LifeMiles expire 12 months from your last earning activity. Any account activity — earning miles, purchasing miles, even a credit card transaction — resets the clock on your entire balance. Set a recurring reminder every 10 months to run a small transaction if you're holding a balance without an imminent booking.
Don't book Lufthansa First Class expecting the same experience. Lufthansa's First Class is a separate product with separate availability and pricing. Business class is the sweet spot here — outstanding value, more seats, and significantly better availability.
According to recent reports, avoid mixing Marriott Bonvoy transfers with tight timelines. At 3:1 and 1–5 days transfer time, Bonvoy is the slowest and least efficient path into LifeMiles. Plan accordingly.
Recent findings suggest that this redemption is built for the experienced FI traveler who has already earned their first free night or domestic flight and is ready to graduate to aspirational international business class. You don't need to fly business class constantly — but for a honeymoon, a milestone birthday, or a long-planned European trip, this is the redemption that makes the experience extraordinary without derailing your savings rate.
This is NOT the right redemption if:.
Recent findings suggest that you need 63,000 LifeMiles per person, per direction. A couple flying one-way needs 126,000 miles. Most people will get there through a combination of one or two travel credit card welcome bonuses and organic spending — entirely achievable within the FI community's existing card strategy.
Industry observers note that ## Rated: Hard — Here's Why This redemption earns its **hard** rating from three compounding challenges, none of which is insurmountable but all of which require deliberate effort. **Challenge 1: Award Availability Is Limited.** Lufthansa releases partner award seats conservatively. You may search for weeks before finding space on your preferred route and dates. This isn't a redemption where you decide Tuesday you want to go and book Thursday. You need a booking window of weeks to months, and flexibility in your travel dates helps enormously. **Challenge 2: The Booking Process Has Friction.** LifeMiles' website doesn't always surface partner award availability accurately. You'll likely need to search on United.com to find the space, then call LifeMiles to actually book it. That phone call requires patience — hold times vary, and you'll need to clearly communicate flight numbers, dates, and cabin class to the agent. **Challenge 3: Timing the Transfer Is High-Stakes.** Because you can't transfer points *out* of LifeMiles, you're committing your points the moment you initiate a transfer. Finding the seat, moving the miles, and completing the booking requires confidence and speed. ## How to Overcome the Challenges 1. **Start searching early** — 300+ days out for peak travel. Use ExpertFlyer alerts to monitor availability passively. 2. **Use Citi ThankYou for instant transfers** so you can act immediately when you find a seat. 3. **Practice the phone booking process** once before your high-stakes redemption — call LifeMiles with a simple question to understand their system. If you've successfully booked one or two simpler awards before, you can absolutely do this. The ChooseFI community has members completing this redemption every year — and every single one says the boarding moment made the effort completely worth it.
Recent findings suggest that united reveals Star Alliance partner availability that LifeMiles can book. Search for Saver-level awards in business or first class on your target route. Note the exact carrier, flight number, and date.
Sources indicate that amex MR, Chase UR, Citi ThankYou, and Capital One miles all transfer to LifeMiles. Amex transfers are often fastest (same day). Transfer only after confirming availability in Step 2.
Recent findings suggest that premium cabin award space is limited and competitive. Once your transferred miles appear in your LifeMiles account, complete the booking immediately. Do not wait — the seat can be taken by another searcher.
Recent findings suggest that lifeMiles charges low taxes and fees on most partner awards, typically $30-$100 depending on the route. Some carriers (notably British Airways) add fuel surcharges, but most Star Alliance carriers keep fees minimal through LifeMiles.
According to recent reports, yes, Lufthansa First Class is bookable through LifeMiles at 87,000 miles one-way from the US to Europe. Availability is limited and typically released at 14 days before departure for partner programs, though some space appears further out. Search on United.com first to confirm Lufthansa First saver space exists before transferring.
Industry observers note that transfer times vary by partner. Amex Membership Rewards transfers often post same-day. Chase Ultimate Rewards transfers typically take 1-2 business days. Citi ThankYou and Capital One transfers can take 1-3 days. Always account for transfer time when booking time-sensitive award space.
Most Star Alliance carriers booked through LifeMiles have low or no fuel surcharges. The notable exception is British Airways (a oneworld carrier, not bookable through LifeMiles). Taxes and fees on typical Star Alliance routes run $30-$100 per ticket, making LifeMiles one of the cheapest programs for out-of-pocket award costs.
If the booking fails because award space disappeared between your search and transfer, the miles sit in your LifeMiles account. They do not expire as long as you have account activity every 12 months. You can use them for a future booking, but you cannot transfer them back to your original program.
Sources indicate that this sweet spot was last verified over 90 days ago. Award availability and pricing may have changed — verify current rates before booking.
In a recent development, avianca LifeMiles is the program that lets FI-community travelers fly the same premium cabins as frequent business travelers at a fraction of the points cost. By consistently underpricing Star Alliance awards, LifeMiles turns 63,000-87,000 transferable points into experiences worth $8,000 or more. The process requires discipline (never transfer before confirming availability), patience (searching for saver space takes time), and a willingness to navigate a less polished booking experience. But the value is real: 15-20 cents per point on aspirational flights that would be unreachable at cash prices.
🔗 Related Articles
📰 #19144. Transfer Amex Points To Avianca Lifemiles With 10% Bonus: Worth It? 📰 #23656. Unlock Tom's Hardware Premium's SuperComputer 2026 coverage for free — sign up for an account to read detailed reports from the show 📰 #23629. Grindr boss defends dating app’s $120 premium sub after it used to cost $499 a month
General
⚖️ Neutral
🌐 Moneycrashers
#21706. Mailchimp SMS Marketing Review – One List for Texts & Emails, but Credits Expire Monthly
📅 17 Nov 2026 • ⏱️ 5m • 📚 Deep Dive (948 w)
Mailchimp SMS Marketing Review – One List for Texts & Emails, but Credits Expire Monthly
📅 17 Nov 2026 | ⏱️ 5 min read (948 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~5 mins left to finish
📖 0% read
💡 Key Takeaways
- Recent findings suggest that add Mailchimp SMS Marketing if you already email customers from Mailchimp and want texts in the same audience and automation flows.
- Mailchimp started in Atlanta in 2001 as an email service for small businesses, and Intuit bought it in 2021.
- Texting needs a paid Mailchimp email plan, Essentials or higher, and several features below need Standard or Premium.
Recent findings suggest that add Mailchimp SMS Marketing if you already email customers from Mailchimp and want texts in the same audience and automation flows. It starts at $20 a month for 1,000 U.S. credits, and unused credits expire every month, so a store that sells mostly by text should choose a service built for texting.
Mailchimp started in Atlanta in 2001 as an email service for small businesses, and Intuit bought it in 2021. Its texting add-on sends to the U.S., Canada, Australia, and more than 30 European countries, and every business has to apply and be approved before its first text goes out.
Texting needs a paid Mailchimp email plan, Essentials or higher, and several features below need Standard or Premium.
A text written with plain letters, numbers, and common symbols holds 160 characters, and one with an emoji or another special character holds 70. A longer text splits into parts of 153 or 67 characters, and each part uses its own credits. Your organization name opens every text by default, since some carriers require it, and it counts toward the limit along with spaces, emojis, and opt-out instructions.
In a recent development, on the Standard and Premium plans, programs in the U.S. and Canada can also send picture messages, called MMS. Each carries one JPEG, PNG, or GIF and up to 1,600 characters, and costs 3 credits in the U.S. and 5 in Canada. Those plans also get branded short links, which shorten your links under a subdomain you choose. On any blueprint, the builder can shorten and track links, add merge tags that personalize each text, and insert a discount code from a Shopify, WooCommerce, BigCommerce, Magento, PrestaShop, or Lightspeed store.
You can add a Send SMS step to the same automation flows that send your emails. Mailchimp’s prebuilt flows include one for abandoned carts, which texts a shopper once per cart left behind. A text a flow triggers during quiet hours, the late-night and early-morning window when marketing texts are held, waits until they end. On the Essentials proposal, a flow holds no more than four steps.
In a recent development, each country needs its own registered sending number, and texts reach only contacts in the countries you’ve registered. A text uses 1 credit in the U.S., 3 in Canada, 5 in the U.K., and 12 in Germany. U.S. businesses on Standard or higher can also apply for a short code, a 5- or 6-digit number built for large audiences. It costs extra, and carriers take 8 to 12 weeks to review the application.
Replies land in Mailchimp’s Inbox, and every answer you send uses credits. You can reply to a contact three times in 7 days, and the 7-day window restarts each time they text you again. That covers a question about an order, not ongoing customer service by text. On a two-way number, replies of STOP or HELP get automatic answers that use no credits.
In a recent development, credits come in monthly blocks. On Mailchimp’s U.S. pricing page, 1,000 credits cost $20 a month, 2,500 cost $25, 5,000 cost $45, and 10,000 cost $90, with blocks up to 450,000 for $2,500. By our math, a plain U.S. text costs 2 cents at the smallest block and 0.9 cents at 5,000 or 10,000. Mailchimp’s 14-day free trial of its email looks doesn’t cover texting, and the Free blueprint can’t add it.
Your block renews with your email proposal each month, and unused credits expire when the next billing cycle starts. A refill bought mid-month costs full price, while a change to your monthly block takes effect at the next cycle. You pay nothing until your application is approved, the first month is prorated, and refunds come only for a system malfunction or an account closed without cause.
Sources indicate that email consent doesn’t cover texts, so each contact has to opt in to SMS through Mailchimp’s signup landing page or an SMS phone field added to your other signup forms. Mailchimp’s own SMS signup forms record the date and time each contact was asked and agreed, and importing a list means confirming that every contact gave explicit SMS consent.
Carriers bar texts about sex, hate, firearms, tobacco, cannabis, gambling, and political campaigns, and they allow alcohol only in programs that verify age. Among financial services, high-interest loans and debt collection are barred too, and breaking the rules can get an account suspended. In the U.S., carriers cap how fast texts go out by a score they give each business, from 75 a minute to AT&T customers at the entry tier to 4,500 at the top. Texts over the cap wait in a queue. Every U.S. account is registered with carriers automatically, and an upgrade called standard vetting may speed up sending. It comes with a block of 5,000 or more credits or with the Premium proposal.
Mailchimp SMS Marketing works best as an extension of email you already send from Mailchimp. Texts reach the same audience through the same segments and flows, the compliance work runs in the background, and a small U.S. program costs $20 to $25 a month.
Learn more about Mailchimp SMS Marketing.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Recent findings suggest that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every firm or offer available in the marketplace.
General
⚖️ Neutral
🌐 Moneycrashers
#21705. Mailchimp Review – Easy to Use, Pricey Once Your List Grows
📅 17 Nov 2026 • ⏱️ 5m • 📚 Deep Dive (959 w)
Mailchimp Review – Easy to Use, Pricey Once Your List Grows
📅 17 Nov 2026 | ⏱️ 5 min read (959 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~5 mins left to finish
📖 0% read
💡 Key Takeaways
- According to recent reports, mailchimp lets a small business send polished marketing email without a designer or a developer.
- Recent findings suggest that ben Chestnut and Dan Kurzius started Mailchimp in Atlanta in 2001 as a small-business email service on the side of their web design agency, and the firm is still based there.
- Recent findings suggest that mailchimp sells four looks: Free, Essentials, Standard, and Premium.
According to recent reports, mailchimp lets a small business send polished marketing email without a designer or a developer. Its templates and drag-and-drop editor handle the design, and its integrations bring in your customers and their purchases from the store or website you already run. The trade-off is a price that rises with each tier of contacts you store.
Recent findings suggest that ben Chestnut and Dan Kurzius started Mailchimp in Atlanta in 2001 as a small-business email service on the side of their web design agency, and the firm is still based there. Intuit, the maker of QuickBooks and TurboTax, bought it in 2021, and Mailchimp indicates it now has more than 11 million owners.
Recent findings suggest that mailchimp sells four looks: Free, Essentials, Standard, and Premium. All four share the same email builder, sign-up forms, landing pages, and directory of more than 300 integrations, and the paid tiers add automation, testing, and reporting.
According to recent reports, the drag-and-drop builder starts from more than 130 templates on paid intends, while the Free strategy gets a limited selection and puts Mailchimp’s branding on every email. Paid plans also let you schedule sends.
Standard and Premium add generative AI, still in beta, that drafts and rewrites copy in the editor. They also let you send templates you code yourself in HTML and use dynamic content, which changes parts of an email for each reader.
It has been revealed that automation flows send emails on their own when a contact does something, such as joining your list or leaving items in a cart. Essentials limits each flow to four steps. Standard and Premium allow up to 200 flows, with branches that send contacts down different paths and more than one starting point.
According to recent reports, A/B testing comes with every paid plan. It tries up to three versions of a subject line, sender name, content, or send time on part of your list, then can send the winner to the rest automatically. Standard and Premium add multivariate testing, which compares up to eight versions at once, plus send-time optimization, which picks a send time from your list’s past clicks.
Every plan can build sign-up forms and landing pages, and a landing page can sit on a Mailchimp address or on a domain you connect. The integrations directory lists more than 300 apps, including Shopify, WooCommerce, Square, Wix, Squarespace, Stripe, Canva, Zapier, and QuickBooks Online. A connected store such as Shopify syncs customers and purchases into Mailchimp, which uses them for product recommendations and abandoned-cart emails.
Every initiative includes basic campaign reports. Standard and Premium add custom reports, advanced segmentation, and predictive segments that group customers by predicted lifetime value or likelihood to buy.
In a recent development, each paid strategy is priced by contact tier, a band such as 2,501 to 5,000 contacts, and the top of your tier is your contact limit. Your monthly send limit is a multiple of it. Here’s where each plan starts:.
The price rises promptly. Standard costs $45 a month at 1,500 contacts, $100 at 5,000, and $135 at 10,000, almost seven times its starting price. Essentials runs $26.50, $75, and $110 at the same sizes.
It has been revealed that discounts are narrow. A new customer who skips the trial and buys a plan at 10,000 or more contacts gets 15% off the first 12 months, and nonprofits and charities get 15% off on request. Essentials and Standard come with a 14-day free trial that bills the plan’s price when it ends unless you cancel. If you send only a few times a year, Pay As You Go sells email credits with Essentials’ features instead of a subscription, though the credits expire after 12 months.
Text messaging costs extra as well, since Mailchimp SMS Marketing is a paid add-on that needs Mailchimp’s approval of your application first.
For a substantial list you email a few times a month, look at Brevo, which prices its intends by the emails you send rather than the contacts you keep. Its Standard blueprint, which also includes automation and A/B testing, costs $69 a month for 20,000 emails, enough to reach 10,000 contacts twice. Mailchimp’s Standard plan costs $135 a month at 10,000 contacts, though it allows 120,000 sends and five seats to Brevo’s one. Brevo’s free plan holds up to 100,000 contacts and sends up to 300 emails a day.
Essentials and Standard come with 24/7 email and chat support, and Premium adds priority support and phone calls, which are in English only. The Free proposal gets email support for its first 30 days only. Standard includes one hour-long onboarding session in your first 90 days, and Premium includes up to four.
In a recent development, reviews depend on where you look. Mailchimp averages 4.3 out of 5 from about 13,000 reviews on G2, a software review site, but 2.5 out of 5 from about 1,600 on Trustpilot.
Recent findings suggest that mailchimp makes it easy for a small business to start an email list that works with the store or website it already runs, and Standard is its best plan while the list is small. At 500 contacts, $20 a month buys automation flows, multivariate testing, generative AI, and an onboarding session.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every tech giant or offer available in the marketplace.
🔗 Related Articles
📰 #21706. Mailchimp SMS Marketing Review – One List for Texts & Emails, but Credits Expire Monthly 📰 #23598. Noodles & Manufacturer store closures: List of shuttered locations grows as restaurant chain optimizes footprint 📰 #21951. On Cloudsurfer 3 Review: A Firm-Soft Daily Trainer for Long, Easy Miles
General
⚖️ Neutral
🌐 Moneycrashers
#21704. H&R Block Review – Free for Simple Returns, With Tax Pros Online or in Person
📅 17 Nov 2026 • ⏱️ 6m • 📚 Deep Dive (1298 w)
H&R Block Review – Free for Simple Returns, With Tax Pros Online or in Person
📅 17 Nov 2026 | ⏱️ 6 min read (1298 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- In a recent development, file with H&R Block if your return fits Free Online, which takes retirement, Social Security, and unemployment income with a free state return, or if you want tax pros to answer questions or sign your return.
- According to recent reports, doing your own taxes costs less than paying a preparer, but it leaves you alone with any form you don’t understand.
- According to recent reports, brothers Henry and Richard Bloch founded H&R Block in 1955 in Kansas City, Missouri, where it’s still based.
In a recent development, file with H&R Block if your return fits Free Online, which takes retirement, Social Security, and unemployment income with a free state return, or if you want tax pros to answer questions or sign your return. If you need a paid tier but no help, file with a free program instead.
According to recent reports, doing your own taxes costs less than paying a preparer, but it leaves you alone with any form you don’t understand. H&R Block offers several kinds of help in between. Its online software files simple returns free, and its paid tiers include live tax pros who answer questions. For an added fee, a pro will check and file your return, or prepare it for you, online or in an office.
According to recent reports, brothers Henry and Richard Bloch founded H&R Block in 1955 in Kansas City, Missouri, where it’s still based. It has about 11,000 tax offices worldwide, with locations in every state, and nearly 60,000 tax pros. In its fiscal year ended June 30, 2026, its pros prepared 11.3 million U.S. returns, and customers prepared 3.6 million returns themselves in its paid online tiers.
H&R Block sorts its online software into four tiers by the forms a return needs, and the tier sets the price. Any return can start in Free Online, and H&R Block notes it moves you to a paid tier only when your situation requires one.
Free Online charges nothing for federal or state returns. It takes W-2 wages, unemployment benefits, retirement initiative distributions, Social Security, and up to $1,500 of interest and dividends. It also claims the Earned Income Tax Credit, the Child Tax Credit, education credits, and the student loan interest deduction. Its form list for 2025 returns included Schedule 1-A, which claims the new deductions for tips, overtime, car loan interest, and seniors.
In a recent development, it can’t itemize deductions, and it leaves out freelance or business income, rental income, stock sales, foreign income, and health savings accounts (HSAs). H&R Block notes about 52% of filers qualify, without saying how it counts them. A Federal Trade Commission (FTC) order requires its ads for free filing to give that share or say that most filers don’t qualify. Since the 2026 season, the same order has required H&R Block to return a filer who upgrades and then moves back down to the point they’d reached before upgrading, instead of starting them over.
Each paid tier adds forms the one before it lacks, and each charges $49 for every state return on top of its federal price.
Deluxe, Premium, and Self-Employed include unlimited help at no extra charge, and Free Online includes none. AI Tax Assist, H&R Block’s chatbot, answers tax questions at any hour and any step, and live tax pros take the ones you’d rather ask a person. The help is for your questions. For a pro to check, sign, and file your return, you add Tax Pro Review, which costs extra.
Tax Pro Review puts a tax pro on your return without an office visit. When you finish, the pro checks your return and documents for errors and missed deductions or credits, asks for anything more they need, and signs and e-files the return once you approve any changes. H&R Block says the review usually takes up to three days after you send your documents, though timing varies with a return’s complexity and in peak weeks. It adds $75 to Free Online, $65 to Deluxe, and $95 to Premium or Self-Employed.
According to recent reports, A pro can also prepare the whole return, starting at $99 plus a state fee. You can meet one at an H&R Block office, drop your documents off at one, or work with a pro from home through its MyBlock app.
It has been revealed that moving from another program takes an upload of last year’s Form 1040, or H&R Block will transfer the return for you. It notes a return from TurboTax or another tax prep service comes over in as little as two minutes. A federal refund deposited to Spruce, H&R Block’s banking app, can arrive up to five days early.
It has been revealed that the prices in this review are what H&R Block charges for 2025 returns. It usually opens the next season’s online software in November, and its prices for 2026 returns may differ.
It has been revealed that at those prices, a homeowner who itemizes and files one state return pays $114 in Deluxe, $65 plus $49 for the state, or $179 with Tax Pro Review. A freelancer who deducts business expenses needs Self-Employed, which comes to $179 with one state, or $274 with Tax Pro Review. Free Online with Tax Pro Review costs $75, state return included.
Each paid tier’s price includes its help, whether you use it or not. For a filer who won’t use the help, Cash App Taxes charges $0 for federal and state returns, freelance income and stock sales included, though it gives no tax advice. If you’re choosing between H&R Block and TurboTax, price the tier your return needs at both before you start.
It has been revealed that H&R Block’s guarantees depend on who prepared the return. On a return you prepare in its online software, the 100% Accuracy Guarantee reimburses penalties and interest caused by a software error, up to $10,000. On one its tax pro prepares, it reimburses penalties and interest from an H&R Block error, with no cap stated.
It has been revealed that the Maximum Refund Guarantee refunds the software fees if a software error left you a smaller refund or a larger tax bill than you were due, and you can amend the return in the software at no charge. You must claim it during the calendar year the return was prepared. Neither guarantee covers a mistake caused by incomplete or inaccurate information you supplied.
Sources indicate that if the IRS or your state sends a notice about a return you filed online, H&R Block explains it and gives you steps to respond at no extra charge. Someone to represent you at an audit costs extra. Worry-Free Audit Support, which you can buy with any online tier, adds in-person representation by an H&R Block enrolled agent, a tax specialist licensed by the IRS but not an attorney. It pays none of the tax, penalties, or interest you owe, and you have 60 days from the notice to tell H&R Block.
Industry observers note that H&R Block is worth it for two kinds of filers. One has a return that fits Free Online, which files a federal and a state return at no cost for more kinds of income than W-2 wages alone. The other wants a tax pro to ask, to check the return, or to prepare it, online or in an office.
It’s the wrong pick for a return that needs a paid tier but no help, since the tier’s price includes the help either way and a free program costs nothing. Start your return in Free Online and let H&R Block show you which tier your forms need before you pay for one.
Learn more about H&R Block or see how it compares to the best free online tax software.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Industry observers note that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.
General
⚖️ Neutral
🌐 Goodfinancialcents
#21703. Latest Update: Which Debts Should You Pay Off First — Credit Cards or Student Loans?
📅 08 Sep 2023 • ⏱️ 8m • 📚 Deep Dive (1593 w)
Latest Update: Which Debts Should You Pay Off First — Credit Cards or Student Loans?
📅 08 Sep 2023 | ⏱️ 8 min read (1593 words, 📚 Deep Dive) | Source: Goodfinancialcents
⏱️ ~8 mins left to finish
📖 0% read
💡 Key Takeaways
- Home » Student Loan Refinance » Which Debts Should You Pay Off First — Credit Cards or Student Loans?
- Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
- Holly Johnson is the founder of Club Thrifty, a personal finance and travel resource geared to families who want to...
Home » Student Loan Refinance » Which Debts Should You Pay Off First — Credit Cards or Student Loans?
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
Holly Johnson is the founder of Club Thrifty, a personal finance and travel resource geared to families who want to...
Recent findings suggest that goodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Latest York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Newly introduced York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
It has been revealed that having more than one type of debt is common, and that’s especially true once you graduate from college and start your first “real job.” You may have credit card debt, an auto loan, and a mortgage payment to make once you buy your first home. It’s also common to have other random debts to cover, including student loans.
According to recent reports, if you’re like many who took out loans during college, you will likely be paying them off after you graduate. In fact, 82% of students who borrowed loans expect to be making payments post-graduation, according to a recent College Ave Student Loans survey.
That said, you’ll want to make sure you’re balancing debt repayment with your savings goals along the way.
In a recent development, you’ll also want to make sure you’re paying down debts in the optimal order, or in a way that will help you save the most money on interest as possible while aligning with your goals. Which debts should you pay off first? Here’s a rundown of how to get the best results:.
No matter which types of debt you have, credit card debt should be your first priority. Why? Because credit card debt is likely the most expensive debt you have by far.
Federal Reserve data reveals the average credit card interest rate on accounts assessed interest came in at around 22% as of May 2023, yet your credit card could easily be charging higher rates than the average.
Industry observers note that to save as much money as possible, you should strive to pay as much as you can toward high-interest credit card bills each month. You can also pay down credit card debt faster with the help of a debt consolidation loan or a 0% APR balance transfer credit card.
Sources indicate that other unsecured debts like personal loan debt should come next in the debt payoff pecking order. After all, unsecured debts tend to have higher interest rates than secured debts like auto loans. In fact, the Federal Reserve also reported that the average interest rate on a 24-month personal loan came in at 11.48% as of May 2023, compared to the average rate of 7.81% on a 60-month auto loan.
Ideally, you’ll start paying more toward personal loan debt and other unsecured debts after all credit card debt is entirely paid off, although you should make at least the minimum payment on all your bills throughout the entire process.
According to recent reports, the next debt you’ll want to tackle is your student loans. I suggest focusing on these loans after other unsecured debts, since federal student loans (and many private student loans) come with low fixed interest rates and monthly payments that will not change over time. If you have federal student loans, you may even want to look into income-driven repayment aims.
If you’re hoping to pay down student loans faster or just want to save money on interest, you can also consider refinancing your student loans to get a shorter repayment timeline, a lower monthly payment, or both. Just remember that refinancing federal student loans can mean losing access to income-driven repayment plans and federal protections like deferment and forbearance.
Once you have paid off or substantially paid down all your other debts, you can focus your efforts on secured debts you have like mortgage loans and auto loans. These debts should be dealt with last since they are secured with collateral and tend to offer lower interest rates as a result. For example, you can consider paying more than the minimum on your mortgage, a car loan, or both until they’re paid off completely.
Then again, you may want to pay off debts with extremely low interest rates as slowly as possible to free up more cash flow for living expenses and investments. If you took out a mortgage in January of 2021 when the average interest rate on a 30-year, fixed rate home loan was as low as 2.65%, for example, it makes sense to make the minimum payment on that debt and invest your extra cash instead.
In a recent development, it’s important to make sure you balance debt repayment with other financial considerations. After all, focusing too much on debt repayment early in life can leave you behind when it comes to investing for retirement or saving up for a first home.
While you’ll want to eliminate credit card debt and other high-interest debts as quickly as you can, even if you have to stop saving and investing for a while, you can pay down student loan debt and secured debts at a slower pace while saving and investing for the future along the way.
Sources indicate that finally, make sure you have adequate emergency savings throughout your entire debt payoff journey, or that you begin saving for emergencies as soon as you can. Without a fully funded emergency fund, you can end up relying on credit cards and other loans to get by and ruin your debt payoff progress in the process.
Industry observers note that how much should you save? While most experts recommend having an emergency fund that can cover three to six months of expenses, it’s okay to start small if you have to.
Having more than one type of debt is how it works for most people, especially when you’re young and in the early stages of your career. When it comes to paying it off, however, you’ll want to make sure you have a concrete plan that can help you reduce interest charges and get where you want to be.
Focusing on credit card debt and other unsecured debts first always makes sense, since these debts aren’t secured by an asset and tend to charge much higher interest rates. You can focus on student loans next, followed by other secured debts you have like a home loan or car loan.
In the meantime, make sure you have an adequate emergency fund and invest in it for retirement. After all, debt won’t last forever if you’re serious about repayment, and saving and investing early can help you benefit from compound interest and avoid using credit cards for surprise expenses. Creating a budget to track these factors is your best bet.
If you need help creating one, or simply don’t know where to start, use this budget worksheet as your guide – you’ll reach financial freedom in no time.
The Federal Reserve (n.d.) Consumer Credit - G.19 https://www.federalreserve.gov/releases/g19/current/.
According to recent reports, federal Reserve Bank of St. Louis (n.d.) 30-Year Fixed Rate Mortgage Average in the United States (MORTGAGE30US) https://fred.stlouisfed.org/series/MORTGAGE30US.
Federal Student Aid (n.d.) Income-Driven Repayment Prepares https://studentaid.gov/manage-loans/repayment/plans/income-driven.
It has been revealed that jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance book Soldier of Finance. He was a financial planner for 16+ years having founded, Alliance Wealth Management, a SEC Registered Investment Advisory firm, before selling it to focus on his passion - educating the masses on the importance of financial freedom through this blog, his podcast, and YouTube channel. Jeff holds a Bachelors in Science in Finance and minor in Accounting from Southern Illinois University - Carbondale. In addition to his CFP® designation, he also earned the marks of AAMS® - Accredited Asset Management Specialist - and CRPC® - Chartered Retirement Planning Counselor. While a practicing financial advisor, Jeff was named to Investopedia's distinguished list of Top 100 advisors (as high as #6) multiple times and CNBC's Digital Advisory Council. Jeff is an Iraqi combat veteran and served 9 years in the Army National Guard. His work is regularly featured in Forbes, Business Insider, Inc.com and Entrepreneur.
🔗 Related Articles
📰 #22001. Latest Update: Running Faster vs Running Longer: Which Should I Focus On First? 📰 #19070. Tech Report: Capital One business credit cards for upcoming LLCs: Which card to get based on your credit history 📰 #15688. NBA panic meter: Which teams should worry after first month of season?
General
⚖️ Neutral
🌐 Moneycrashers
#21702. VSP Individual Vision Aims Review – Worth It If You Buy Glasses Every Year
📅 17 Nov 2026 • ⏱️ 6m • 📚 Deep Dive (1220 w)
VSP Individual Vision Aims Review – Worth It If You Buy Glasses Every Year
📅 17 Nov 2026 | ⏱️ 6 min read (1220 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- In a recent development, buy one of the VSP Individual Vision Aims if you get newly introduced glasses or contacts every year from a VSP doctor, since the $150 allowance and $15 exam copay can save more than the premiums cost.
- Recent findings suggest that retiring or leaving a job usually ends your vision coverage, and then you pay the full price of an exam and new glasses yourself.
- VSP, a not-for-profit vision benefits manufacturer founded in 1955, is based in Rancho Cordova, California, and sells these plans directly on its own website.
In a recent development, buy one of the VSP Individual Vision Aims if you get newly introduced glasses or contacts every year from a VSP doctor, since the $150 allowance and $15 exam copay can save more than the premiums cost. If you need only an exam or buy glasses online elsewhere, skip it and pay out of pocket.
Recent findings suggest that retiring or leaving a job usually ends your vision coverage, and then you pay the full price of an exam and new glasses yourself. VSP created its individual plans for people without coverage through an employer, and a year of premiums pays off mainly for those who use the glasses or contacts allowance.
VSP, a not-for-profit vision benefits manufacturer founded in 1955, is based in Rancho Cordova, California, and sells these plans directly on its own website. It counts more than 41,000 eye doctors in its network, and the Better Business Bureau rates Vision Service Blueprint, the company’s legal name, A+.
All four looks renew their benefits every 12 months and have no waiting period, so you can book an exam the day you enroll. They differ in what lens upgrades cost and whether an exam is covered.
Standard covers the basics with two copays, which are flat fees you pay at the office. You pay one at the exam and one for the glasses, and the plan costs the least of the three that include an exam.
A frame inside the allowance costs nothing beyond the copays. VSP puts the average frame at $253 without insurance, and by our math the allowance and the 20% discount leave about $82 of that to pay.
According to recent reports, both plans keep Standard’s exam, glasses copay, and allowance and cut what lens upgrades cost. That matters most for progressive lenses, which correct near and far vision with no visible line, and which VSP prices at $504 for a custom pair without insurance.
VSP’s plan page lists typical prices of $30 a month for EasyOptions and $35 for Enhanced, against $17 for Standard.
EyewearOnly drops the exam for a typical $12 a month. It keeps the $25 glasses copay and gives a $120 allowance for frames or contacts, or $140 on featured frame brands, but your prescription has to come from an exam in the past 12 months. It suits someone who already has a current prescription.
VSP prices each proposal by where you live and demonstrates your rate after you enter a ZIP code. These quotes came from its site on Nov. 16, 2026, for one adult unless noted:.
Recent findings suggest that in California, every plan but Standard also carried a $1.50 monthly membership in the Healthy Vision Association, a discount program some plans require. The Newly introduced York quotes had no such fee, and California’s Standard, EasyOptions, and Enhanced prices didn’t change between the 30-to-44 and 64-and-older age brackets.
You can pay for the year up front or in 12 monthly installments, but the monthly option is still a one-year contract. The plan renews automatically on the card you enrolled with, and VSP sends a reminder 60 days before. You can switch plans only in the first 30 days, and only if you haven’t used any benefits.
Industry observers note that take one adult on Standard in Rancho Cordova who gets an exam and one pair of single-vision glasses with a $150 frame. Without insurance, VSP’s own figures put that exam at $214 and the lenses at $118. The plan’s year costs $244, $204 in premiums plus the $15 and $25 copays, against $482 without it, a $238 saving.
Recent findings suggest that buying the plan for an exam alone costs $219 a year on Standard in Rancho Cordova and $165 in Newly introduced York, premiums plus the $15 copay. VSP puts an uninsured exam at $214, but All About Vision’s survey of 100 eye care practices found an average of about $110, and $93 at retail chains, so at those prices you’d pay less without the plan.
The pricier aims pay off for progressive wearers. In Rancho Cordova, EasyOptions costs $167 a year more than Standard, fee included, and cuts the $175 progressive copay to $0, for a net gain of about $8. In Latest York, Enhanced costs $66 a year more than Standard and caps progressives at $55, which saves $120 on them for a net gain of $54.
The IRS counts eye exams and prescription glasses as medical expenses, so the copays and any frame cost above the allowance are a good use of flexible spending account money before it expires.
At an in-network office you tell the staff you have VSP, pay the copays, and file nothing. VSP lists Visionworks and Eyemart Express stores in its network, and members can use their benefits on Eyeconic, VSP’s online eyewear store. Costco’s optical departments are out of network for these looks, and VSP’s own pages disagree about Walmart, so check a store in VSP’s doctor search before you book.
Out of network, you pay the bill, mail VSP an itemized claim, and get back no more than these amounts:.
Massachusetts and Washington residents get no out-of-network coverage, and coverage varies in Maryland. A pair of single-vision glasses from a seller outside the network returns $100 at most, and contacts $105, less than a year of Standard premiums in either city above. Buyers who already shop for prescription glasses for less or contact lenses online outside the network get little from the allowance.
It has been revealed that VSP’s site shows 4.6 stars from 50,377 member reviews, while Trustpilot, which notes that VSP hasn’t asked customers for reviews lately, shows 1.2 out of 5 from 121 reviews, 95% of them one-star. The BBB logged 58 complaints against Vision Service Proposal in three years. In 2024, VSP’s insurance manufacturer paid Missouri’s insurance regulator $25,000 to settle allegations that it sold intends there without filing their rates and an individual policy form and made false statements to investigators, admitting nothing.
In a recent development, VSP’s individual plans work best for a person or family without workplace coverage who gets newly introduced glasses or contacts every year from an in-network doctor. For that buyer, Standard saved $238 against VSP’s own uninsured prices in our Rancho Cordova example, and progressive wearers can come out further ahead on EasyOptions or Enhanced.
The looks make less sense if you need only an exam, buy your eyewear online outside the network, or live in Massachusetts or Washington and use doctors outside it. Before you enroll, quote all four plans at your ZIP code, add the $1.50 membership fee where it appears, and compare the year’s total with your doctor’s cash prices for the exam and glasses you’d buy anyway.
Learn more about VSP Individual Vision Plans.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
According to recent reports, advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every tech giant or offer available in the marketplace.
General
⚖️ Neutral
🌐 Moneycrashers
#21701. Latest Update: TurboTax Review – Worth It If You Want Guidance or an Expert
📅 17 Nov 2026 • ⏱️ 6m • 📚 Deep Dive (1164 w)
Latest Update: TurboTax Review – Worth It If You Want Guidance or an Expert
📅 17 Nov 2026 | ⏱️ 6 min read (1164 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- Choose TurboTax if you want tax software that walks you through every question, or a tax expert to answer them, check your return, or file it for you.
- Doing your own taxes saves a preparer’s fee, but it leaves you to judge whether every answer is right.
- TurboTax is made by Intuit, the Mountain View, California, organization that started in 1983 with the Quicken money manager and also makes Credit Karma and QuickBooks.
Choose TurboTax if you want tax software that walks you through every question, or a tax expert to answer them, check your return, or file it for you. If you’d fill in the forms on your own, file with a free program that covers them instead, since every TurboTax tier beyond simple returns charges a fee.
Doing your own taxes saves a preparer’s fee, but it leaves you to judge whether every answer is right. TurboTax is built around that worry. Its interview turns tax forms into plain questions about your year, and each step up in price adds more help, from a tax expert who answers questions as you go to one who prepares and files the whole return.
TurboTax is made by Intuit, the Mountain View, California, organization that started in 1983 with the Quicken money manager and also makes Credit Karma and QuickBooks. TurboTax brought in $5.3 billion in Intuit’s fiscal year that ended July 31, 2026, and 53% of that came from TurboTax Live, its tax-expert services.
TurboTax Online comes in three levels of help, priced by how complex your return is and how much of the work you hand off: do it yourself, Expert Assist, and Expert Full Service. TurboTax hadn’t posted prices for 2026 returns when this review was written in November 2026, so the prices below are what it charges for 2025 returns. Last season, those prices covered returns filed by March 31, and TurboTax expected to charge more from April 1. You pay the price in effect the day you print or e-file.
In a recent development, the do-it-yourself and Expert Assist tiers share one interview. In place of form lines, it asks about your year, such as whether you own a home, have children, or gave to charity, and fills in the forms from your answers. Intuit Assist, its AI helper, answers questions along the way, and a tool called CompleteCheck reviews the whole return for errors before you file.
In a recent development, you can snap a photo of a tax form, upload it, or import it straight from your employer or financial institution. If you used TurboTax Online last year, signing in with the same user ID carries your information over. Switchers can transfer last year’s Form 1040 as a PDF from other providers, including H&R Block, TaxAct, and TaxSlayer.
The do-it-yourself tiers differ by which parts of a return they handle, and the two paid ones charge $64 for each state return.
Sources indicate that enlisted active-duty members and reservists, E-1 through E-9, file federal and state returns free in any of these tiers with a W-2 from the Defense Finance and Accounting Service. Officers, veterans, retirees, and National Guard members don’t qualify, and the discount doesn’t apply to the expert tiers.
Returns for an S corporation, a partnership, or a multi-member limited liability company (LLC) go through TurboTax’s business service, TurboTax Experts for Business.
It has been revealed that expert Assist is the same software with a tax expert on call. You can reach one by phone, live chat, or one-way video, where you see the expert but they can’t see you, and share your screen so the expert can guide you. Before you file, an expert gives the whole return a final review. If the return needs significant advice or actual preparation, the expert may have to sign as its preparer and take primary responsibility for it.
Last season, experts were available seven days a week from Jan. 5 through April 20, 5 a.m. to 9 p.m. Pacific time, and customers could keep asking questions through Dec. 31 of the year they filed.
In a recent development, full Service hands the whole return to a dedicated tax expert. You upload your documents, and the expert prepares the return, walks you through it, then signs and files it. TurboTax says its expert files only a return they believe is 100% correct.
According to recent reports, it starts at $129 for one federal return with one W-2, plus $69 per state, and the final price depends on the forms your return needs. You get an estimate before the expert starts. You can work with the expert by phone, one-way video, or messages, or in person where a local expert is offered, at one of more than 500 TurboTax Expert offices.
TurboTax’s calculation and refund guarantees last for what Intuit calls the life of a return, seven years from the day you file it with TurboTax.
Audit support is information only, so no one from TurboTax represents you before the IRS. For that, it sells Audit Defense, an add-on from a separate company, Tax Audit, for an extra fee.
Paying TurboTax out of your federal refund can add a $40 service fee. An early-refund option deposits your federal refund up to five days before the IRS would, for a fee taken from the refund, though TurboTax’s early-refund page doesn’t say how much that fee is. You aren’t charged if the money doesn’t arrive at least a day early.
According to recent reports, turboTax has also offered a Refund Advance, an interest-free loan from WebBank against your expected refund, with no loan fees. Last season it lent up to half the refund, to a maximum of $4,000, or up to the whole refund and $10,000 for Full Service customers. Filers needed an expected federal refund of at least $500, and the money went into a Credit Karma Money checking account.
You pay only when you print or e-file, and once you do, you give up the right to a refund of the price.
TurboTax is the tax software to pay for when you want the most guidance, or a tax expert, on your return. Its interview and imports suit filers who find tax forms confusing. Its expert tiers put a professional on the return to answer questions, review it, or prepare it, and its guarantees cover the expert’s mistakes as well as the software’s.
Industry observers note that its weakness is price. Every tier past Free Edition’s simple returns charges a fee, so anyone who’d fill in the forms without help pays for guidance they won’t use. Intuit’s own Credit Karma Tax indicates it will charge $0 for a 2026 federal return. Pay TurboTax’s prices for its interview if tax forms confuse you, or for an expert who checks or prepares your return.
Learn more about TurboTax or see how it compares to the best free online tax software.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
According to recent reports, advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every firm or offer available in the marketplace.
General
⚖️ Neutral
🌐 Goodfinancialcents
#21700. Best Bank CD Rates for 2025
📅 20 Sep 2023 • ⏱️ 12m • 📚 Deep Dive (2434 w)
Best Bank CD Rates for 2025
📅 20 Sep 2023 | ⏱️ 12 min read (2434 words, 📚 Deep Dive) | Source: Goodfinancialcents
⏱️ ~12 mins left to finish
📖 0% read
💡 Key Takeaways
- Looking to make your money work harder?
- Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
- Holly Johnson is the founder of Club Thrifty, a personal finance and travel resource geared to families who want to...
Home » Banking » Best Bank CD Rates for 2025.
Looking to make your money work harder? Explore the world of Certificates of Deposit (CDs), where you can secure solid returns while locking in your funds for a specific time. Discover the banks and credit unions offering the best CD rates, and find out how to maximize your savings with this low-risk investment option.
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
Holly Johnson is the founder of Club Thrifty, a personal finance and travel resource geared to families who want to...
GoodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
According to recent reports, goodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Upcoming York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Fresh York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
Certificates of Deposit (CDs) work similarly to online savings accounts or money market accounts in terms of offering great returns with zero risk. The difference is, CDs “lock your money up” for a specified period of time. To access your funds before the term ends, you’ll have to pay a penalty.
It has been revealed that although CDs offer less liquidity than a regular checking account or savings account, you might get a higher rate of return with this financial product. This is especially true if you open a CD account with a longer timeline; for example, a 60-month CD instead of a 12-month CD.
According to the Federal Deposit Insurance Corporation (FDIC), national average CD rates range from 0.23% to 1.81% depending on the CD term, as of writing.
However, quite a few banks offer vastly superior CD rates to consumers who do their research. We compared dozens of banks and financial institutions to find the best CD rates today. If you’re on the hunt for a high-yield CD, start your search here.
If your goal is securing a superior short-term investment, the best CD rates are worth exploring. To help in your search, we compared many of the top financial institutions and online banks to find options with the most attractive rates and terms.
Explore and contrast the top certificates of deposit (CDs) rates based on the highest Annual Percentage Yield (APY), spanning various terms including 3-month, 6-month, 1-year, 2-year, and 5-year options.
Raisin (Save Better) partners with some of the top banks in the U.S. for the highest rates on CDs. Check below for the current rates.
The banks below made our ranking due to the interest rates they offer and other features.
According to recent reports, there are a few factors to consider when choosing where to open a certificate of deposit. These include whether you want to open your CD in person or online, the rates and terms that apply, and the fees required to access your money early.
The following reviews explain the CD rates for each of the top banks we profile and other details you should know.
In a recent development, PNC Bank offers a variety of popular banking products, including certificates of deposit. Its CDs don’t require any monthly maintenance fees, and you can monitor your account at any time online or with the BBVA mobile banking app.
Sources indicate that CD terms range from 7 days to up to 10 years, and CDs with longer timelines pay higher CD rates. Note that penalties apply if you access your money early.
If you cash out your CD early, with a term of one year or less, you’ll pay $25 plus 1% of the amount withdrawn. If you cash out a CD with a longer-term early, you’ll pay $25 plus 3% of the amount you cash out.
CD Rates: Online CDs with terms from 11 months to 36 months currently pay up to 5.04% APY.
According to recent reports, CIT Bank is known for its popular high-yield savings account, known as Savings Builder, but it also offers an array of CDs with excellent terms. Its 11-month, no-penalty CD stands out since it offers an excellent return rate. There are also no penalties if you need to access your money early.
According to recent reports, CIT Bank also offers term CDs with various other lengths, as well as jumbo CDs for deposits of $100,000 or more. None of its CDs come with account opening fees or account maintenance fees.
According to recent reports, CD Rates: CIT Bank at the moment pays from 0.30% to 3.50% APY on their CDs, depending on the term you choose. Top rates are offered on their 18 month CDs, which pay out 3.00% APY, respectively. Additionally, they have an excellent 11-month No-Penalty CD at 3.50% APY as of the time of this writing (04/05/23.).
With Discover, you can open a CD that lasts anywhere from three months to 120 months. There are no fees to open a CD, including account opening fees or maintenance fees.
Industry observers note that discover also stands out due to the reasonable penalties it charges if you need to access your money early. CDs with a term of less than one year, incur a penalty at three months of simple interest. For a CD that lasts one to four years, the penalty for cashing out early is just six months of simple interest.
CD Rates: The 18-month CD is most rewarding, right now offering 4.00% APY. If you’re willing to part ways with your funds for just 24 months, you can earn a rate of 4.10% APY.
Marcus by Goldman Sachs is a popular online bank for personal loans and high-yield savings accounts, yet it also offers rewarding CDs. Terms for its CDs range from seven months to six years, with a minimum $500 deposit to get started.
Marcus by Goldman Sachs even offers a 10-day guarantee that claims you can move your rate up if the advertised rates on the CD you purchased increase within 10 days.
CD Rates: Some of the best CD rates from Marcus by Goldman Sachs are for its 9-month CDs, which currently pay 4.30% APY. Marcus by Goldman Sachs also offers limited-time CD rate promotions, like 4.40% on an 18-month CD.
What Holds It Back: Marcus by Goldman Sachs is an online bank only, so you don’t have the option to open your CD in person.
In a recent development, we chose Synchrony Bank for our ranking because it doesn’t impose a minimum balance requirement, yet has competitive CD rates. It offers a 15-day guarantee, which lets you raise your rate if the advertised rate increases within 15 days of your CD purchase.
Terms are available from three months to 60 months. Early withdrawal fees for their CDs are also reasonable. For example, early cash-outs on CDs with terms of 12 months or less charge 90 days of simple interest at the current rate.
CD Rates: Five-year (60-month) CDs currently pay 4.00% APY, and three-year (36-month) CDs pay 4.30% APY. They also have a 16 month paying 5.40%.
What Holds It Back: Synchrony Bank CDs are meant to be opened and maintained online, so you consider a different bank if you’re hoping for a personalized experience or you prefer to bank in person.
Finding the best CD rates is crucial if you want to maximize returns on your savings, yet there are other factors to consider before opening an account. We considered the following factors when compiling this list of banks with the best CD rates of 2026:.
Although we gave preference to banks that apply the best rates to various CD terms, we focused on banks that offer at least one CD with an APY that is at least double the average CD rate nationwide.
BBVA didn’t score well in this category, yet we included them due to their lack of account fees and a strong reputation among major U.S. financial institutions.
We only considered banks that don’t charge fees to open a CD account. We also chose banks that don’t charge any monthly account maintenance fees.
It has been revealed that most banks charge an early withdrawal fee if you cash out your CD early, so we looked for banks with reasonable penalties. We also gave preference to accounts or CD options that don’t charge any penalty for early withdrawals.
Recent findings suggest that finally, we only included institutions in our ranking that offer FDIC insurance. This insurance secures up to $250,000 of CD funds per account holder.
Recent findings suggest that if you have never opened a certificate of deposit before, you might wonder how they work and why people choose this option. Here are some important factors when considering a CD account.
Industry observers note that investing in a certificate of deposit (CD) is one of the safest ways to grow your money. CDs are low-risk investments with guaranteed returns, so they can be an excellent choice for those looking to diversify their portfolios and lock in higher interest rates.
Industry observers note that when choosing a CD, it’s notable to compare APYs (annual percentage yields) and terms between different banks and credit unions in order to get the best rate possible. Shop around for promotional offers or talk to financial advisors if you need help selecting the right CD for your needs.
With careful research and comparison, you’ll be able to find the CD that gives you the highest rate – and peace of mind – in the long run.
In a recent development, some of the key factors you should consider when searching for the best CD rates include the length of the term, any penalties for early withdrawal, and minimum deposit requirements. You’ll also want to compare the annual percentage yields (APYs) of different products to ensure you’re getting a good return on your investment.
Industry observers note that some of the key factors you should consider when searching for the best CD rates include the length of the term, any penalties for early withdrawal, and minimum deposit requirements. You’ll also want to compare the annual percentage yields (APYs) of different products to ensure you’re getting a good return on your investment.
Certificate of deposit (CD) rates may fluctuate throughout the year as interest rates change. It’s notable to keep an eye on current market conditions in order to maximize your earning potential by investing in CDs with higher rates.
Certificate of deposit (CD) rates may fluctuate throughout the year as interest rates change. It’s vital to keep an eye on current market conditions in order to maximize your earning potential by investing in CDs with higher rates.
According to recent reports, yes, it is possible to get a higher APY than what is advertised by banks and credit unions – especially if you are willing to negotiate or shop around at online banks that offer competitive CD rates. Additionally, certain banks may offer promotional offers or discounts that can result in even better returns on your investment.
Recent findings suggest that yes, it is possible to get a higher APY than what is advertised by banks and credit unions – especially if you are willing to negotiate or shop around at online banks that offer competitive CD rates. Additionally, certain banks may offer promotional offers or discounts that can result in even better returns on your investment.
In a recent development, when comparing CD rates, consider the length of the term, penalties for early withdrawal, minimum deposit requirements, and the annual percentage yield (APY). The APY reflects the effective interest rate, including compounding.
When comparing CD rates, consider the length of the term, penalties for early withdrawal, minimum deposit requirements, and the annual percentage yield (APY). The APY reflects the effective interest rate, including compounding.
It has been revealed that while advertised rates are set, some banks, especially online ones, may offer negotiation options or promotional offers. Shopping around and researching online banks could help you find institutions that offer competitive rates or special deals.
While advertised rates are set, some banks, especially online ones, may offer negotiation options or promotional offers. Shopping around and researching online banks could help you find institutions that offer competitive rates or special deals.
FDIC.gov (2024, Jan 4) National Rates and Rate Caps https://www.fdic.gov/regulations/resources/rates/.
Industry observers note that tretina, Kat from Wall Street Journal (2022, Dec 24) What Is APY? https://www.wsj.com/buyside/personal-finance/what-is-apy-01671811578.
FDIC.gov (2024, Jan 8) Resources - Deposit Insurance https://www.fdic.gov/resources/deposit-insurance/.
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance book Soldier of Finance. He was a financial planner for 16+ years having founded, Alliance Wealth Management, a SEC Registered Investment Advisory firm, before selling it to focus on his passion - educating the masses on the importance of financial freedom through this blog, his podcast, and YouTube channel. Jeff holds a Bachelors in Science in Finance and minor in Accounting from Southern Illinois University - Carbondale. In addition to his CFP® designation, he also earned the marks of AAMS® - Accredited Asset Management Specialist - and CRPC® - Chartered Retirement Planning Counselor. While a practicing financial advisor, Jeff was named to Investopedia's distinguished list of Top 100 advisors (as high as #6) multiple times and CNBC's Digital Advisory Council. Jeff is an Iraqi combat veteran and served 9 years in the Army National Guard. His work is regularly featured in Forbes, Business Insider, Inc.com and Entrepreneur.
🔗 Related Articles
📰 #23638. Top tech gift ideas for frequent travelers — from USB wall chargers to power banks, here are the best options 📰 #23611. 7 Best Accounts Receivable (AR) Software Platforms for Automating Invoice-to-Cash 📰 #23608. Latest Update: The best Warhammer 40K-themed gifts for your gaming setup
General
⚖️ Neutral
🌐 Mrmoneymustache
#21699. My Unexpected Journey to Hormone Replacement (TRT)
📅 16 Dec 2025 • ⏱️ 14m • 📚 Deep Dive (2755 w)
My Unexpected Journey to Hormone Replacement (TRT)
📅 16 Dec 2025 | ⏱️ 14 min read (2755 words, 📚 Deep Dive) | Source: Mrmoneymustache
⏱️ ~14 mins left to finish
📖 0% read
💡 Key Takeaways
- As a man of Science, I’m supposed to hide my enthusiasm about this somewhat controversial subject, and instead direct you only to the peer-reviewed studies.
- But man, I feel like I’ve stumbled upon the fountain of youth here.
- According to recent reports, I’ve been interested in optimization and trying to get the most out of my body and mind since I was a little kid.
As a man of Science, I’m supposed to hide my enthusiasm about this somewhat controversial subject, and instead direct you only to the peer-reviewed studies.
But man, I feel like I’ve stumbled upon the fountain of youth here. And the more I dig into the details and the hype and controversy surrounding the field of Hormone Replacement therapy, the more I need to share the word about it to my fellow middle-aged people (both men and women).
According to recent reports, I’ve been interested in optimization and trying to get the most out of my body and mind since I was a little kid. I started vacuuming up all the training and nutrition books and magazines I could find while I was just a teenager, and that field still remains a favorite of mine over 30 years later. And if you’re a long-time reader here you’ve been reminded plenty of times of this interest, because health has always been the very heart of Mustachianism.
According to recent reports, but a funny thing has been happening in the last ten years: even as I kept honing the healthy living habits and trying my best to improve, there seemed to be a force pulling me back almost as hard. So despite working a bit harder and smarter every year, I still felt myself riding a gradually declining tide of energy, motivation, and physical stamina.
“Perhaps this is just what it means to grow old”, I thought to myself,.
“But I’m still gonna keep fighting it!”.
It has been revealed that yet there was one thing that didn’t quite fit. Why was I having this decline in energy, when some of my older friends weren’t? And why was I still seeing people out there in their 50s, 60s and well beyond doing things that I felt too tired to do today?
According to recent reports, one of these tireless friends is a guy named Kevin, who is the personification of the highly energetic successful middle-aged man. He’s a semi-retired serial entrepreneur (and extreme rock climber) who lives in Boulder. And through an interesting twist of fate, in April of 2025 he invited me out for a hike right around the time I was doing all this wondering. And during this hike (and climb) he told me about his latest venture, a boutique men’s health manufacturer that specializes in helping men just like us get their youth back through the process of testosterone replacement therapy.
According to recent reports, long story short: his ideas planted a seed in my head, which led to a bunch of research and a growing interest in trying TRT myself. I had of course heard about the process, but for some reason never considered doing it until I heard Kevin’s enthusiasm: he had been on it for several years, and according to him it is a “night and day difference” in all the things you want in life: energy, focus, thinking speed, and of course physical health.
Another convenient twist of fate is that I happen to be dating an REI doctor – a Reproductive Endocrinologist and Infertility specialist who has two board certifications in exactly the relevant bodily systems that are affected by these hormones. And while she was initially skeptical that I needed more Testosterone (and in her practice she regularly sees the downsides of men taking the stuff too early in life and thus compromising their own fertility), she has followed along and helped me learn at each step of this process, eventually becoming fully in support of the program.
Industry observers note that so I signed up as a test customer for Kevin’s fresh company, which is called Bolt Health. I worked with their doctor to get a baseline blood test and review my numbers compared to all the past tests I’ve collected, and as it turned out, my levels had been dropping consistently over the years, and the latest test was by far the lowest ever.
Even more telling, my age-related drop in Testosterone was correlating perfectly with my decline in energy and motivation:.
Sources indicate that the next step was a prescription for a tiny daily dose of supplemental T, which arrived at my house the next week along with instructions for how to use it. And so began the journey.
Now let’s jump forward seven months to the present day as I write this.
And wow, what a great year it has been! I only wish I had known and tried this a few years earlier, because I’m getting a lot more out of my life.
It’s not a night-and-day difference for me, but more like a 50% boost in overall youthfulness and energy. The biggest subjective change is that I just don’t have sucky tired days anymore, which was the main problem with my life before: wasting too much of my precious freedom due to not having the energy to enjoy it.
Sources indicate that this is why I’ve become somewhat of an evangelist for hormone replacement therapy for people from about age 45 onwards. It won’t work for everyone – if your levels are already pretty high, you don’t get the same boost. Two of my male friends tried TRT and quit because they didn’t notice any benefit. But these same two guys already had plenty of energy to begin with, which is usually a sign that the body has what it needs.
It turns out I am very late to this party. Although Testosterone supplementation started out as a niche practice in the 1940s, from the 2010s onward it has been everywhere.
TRT is the reason you see every actor suddenly showing up buff overnight for their superhero roles and it’s also why so many of today’s CEOs don’t look anything like yesterday’s CEOs.
It has been revealed that in many cases, it has gone too far with young men using it just to gain muscle for the beach or the football field, and questionable online providers (aka “Prescription Mills”) handing out prescriptions to anyone with a valid credit card – with profit as their sole motive. It became overhyped in certain pockets of Bro Culture, where every Bro eventually receives the advice “Bro! You need to get on the T!” from another Bro, and therefore does it. And some of this reputation surely contributed to my own skepticism.
Industry observers note that but there’s a lot of valid science behind TRT, if you’re the right candidate and you take the right dosage. And because of that, I feel it is probably under-hyped in my own demographic, the Nerdy Tech Worker Semi Retired Dad contingent. And that’s why I’m writing this blog post, because there are a lot of us out there.
Many of us just tend to work with what we were given, and accept that aging means slowing down. And for those of us already enjoying an early retirement, we have the option of unlimited rest and recuperation time, so who really cares if we get tired a bit more often? After all, what better way to flex one’s wealth than with a decadent Tuesday Afternoon Nap while everyone else is stuck in the office?
Sources indicate that while this seemingly healthy attitude has a lot of positive aspects, it can also mask a real problem which may be easily fixable. Because sometimes, the only thing that’s even better than an afternoon nap, is having the energy and motivation to go out for an afternoon hike, bike ride or adventure with friends. More energy is also pretty darned useful if you’re still raising kids or trying to do well in your career as a person over 45.
How it Actually Works (and What Happened to Me).
Recent findings suggest that distilling all of the fluffy discussion above into the simplest possible answer: TRT means using a tiny needle to inject a few drops of clear liquid just below the surface of your skin. And you do this by yourself at home, ideally once every morning.
Here’s one of the baby needles I use for my daily dose.The typical serving is less than one tenth of a milliliter, which is only a few drops.
Recent findings suggest that and while the term “needle” sounds scary to some, this is very different from the monstrosities they use to draw blood from your veins. This one is so miniature that you don’t need special training to use it, and you usually don’t even feel it.
So I began doing this to myself on May 1st of this year, while keeping a daily journal of my results along the way. The results seemed to be almost immediate in all the promised areas, but I know how powerful the Placebo Effect can be so I kept my skeptic’s hat on to see what would happen in the long run.
Sources indicate that I was seeing increased energy and motivation as well as lean weight gain through the whole spring and summer, but I remember the first truly shocking observation happened during a mountain vacation in July. I was part of a multi-family trip with lively adults, chaotic kids, early mornings, late nights with a few drinks, very intense high altitude sunshine and nonstop physical activities. It was just the type of situation that would drain my energy pretty swiftly in the past.
But on day three I went out on a solo mountain bike ride to explore the area, and as I was climbing a long ascent with the blazing sun cooking me from every angle I just somehow kept having plenty of energy to keep climbing. Then I came down and joined the group for a few games of full-sun pickleball, biked back up the mountain to our cabin, and the story of unlimited energy went on from there.
“Hot Damn”, I thought to myself, “I don’t know whose youthful and tireless body I have inherited here but I’d sure like to keep it!”.
In August, the Bolt Health program scheduled a follow-up blood test for me and sure enough, my Testosterone levels had been boosted from 415 to 730ng/dL, bringing me from the low side of normal to the higher side.
Many labs define “normal” as anywhere between 300 and 1000, which seems strange to me given the huge effect this hormone has on your wellbeing. It’s a bit like saying “Most cars have between 90 and 300 horsepower, so it doesn’t really matter what engine you have”.
I mean yeah, either one will still get you down the road, but which one would you rather be driving?
According to recent reports, since then, it has just been more of the same good results. My improvements ramped up and then just stayed there – so I’m operating at a latest, much higher and more enjoyable level of functioning. Energy and motivation are no longer a problem, and I even find myself willing to make longer-term plans again (before this everything beyond same-day planning felt overwhelming). And my body seems to just want to gain strength and size with any excuse. Heavy weights feel lighter and the hard manual labor I still like to spend my time on feels easier for longer. It’s nice to be young again!
So Why Doesn’t Everyone Do This?
Industry observers note that when you dig into the details, hormone replacement is mired in a soup of both real and incorrect information about both its benefits and its risks. And then our well-meaning medical establishment locks this whole container of soup deep in the cabinet with a label that notes, “Needs Further Study”. But if you summarize the findings on both sides of the issue, you’ll see this:.
Stuff you should do BEFORE trying TRT:.
Industry observers note that the modern American Lifestyle is a Testosterone and Health Crusher. It’s a miracle that anybody feels good ever with the crap that people do to their bodies. So if you’re not already doing all the simple, natural, outdoor things that naturally boost your health, energy, and hormone levels, you’ll want to start with these first. You can find a pretty complete list on my oft-cited Badassity Tracker page.
In a recent development, since I was already doing all of these things pretty consistently, I felt ready to take the next step and at least consider hormone supplementation. But wait, there’s more!
Industry observers note that many of the problems above are more likely to appear when the body is flooded with too much testosterone. In the bad old days, TRT was administered by sticking a pellet beneath your skin or injecting a large amount into the butt which then gets used up over the next several weeks. One friend recounted a story of extreme moodiness when the pellet was first implanted, ramping down to tiredness by the time the hormone was all gone.
It has been revealed that more modern providers like Bolt have fixed this problem by breaking the dose into much smaller servings which you administer each day. The idea is that your levels remain stable, and you need a lot less overall which reduces side effects.
For my part, I have not had any of the negative side effects because I was a pretty ideal candidate in the first place: 50 years old with depressed Testosterone levels but an otherwise healthy lifestyle and no risk factors.
In a recent development, my hope in sharing this article is to be transparent and hopefully take some of the stigma out of this subject of other people who might benefit. Because in our modern over-connected world, everybody has an opinion on your life, even when you didn’t ask them.
Recent findings suggest that and it’s not just men – many women in this same age group benefit from Estrogen replacement (and there are even interesting stories about female testosterone supplementation in certain situations as this author shares). The point is that aging is normal, but in some cases there’s a pretty easy way to make it slower.
According to recent reports, the great news is that Testosterone itself is a cheap and widely available substance, typically under $50 per month even for people like me without conventional insurance or drug coverage. The expensive part (here in the US) is just the doctor stuff – consultations, blood tests, ongoing analysis and prescription renewals and so on.
The firm that I used is positioned as a premium provider, bundling these services along with a bunch of other men’s health perks and deliveries for a few hundred dollars, which is expensive relative to most other parts of my budget, but still cheap if I consider the life and financial benefits of being 20-50% more energetic and productive.
If you want to be on this program, your final decision will hinge on your income, insurance coverage if applicable, whether your existing doctor can already help you, and how much service and advice you’re willing to pay for.
Note: I decided not to become a Bolt health affiliate because I wanted to write this article without conflict of interest. And I can honestly say, Bolt’s product and service seem great to me because I know and trust the people who run it. But it’s also the only one I’ve tried. So I don’t know much about the competition and there may be other good options out there. At the very minimum, you can always try one service and switch to another if you don’t like the first one.
In a recent development, I’ve got lots more to say on money and early retirement, and lots of interesting projects in the works now too. So I’m thankful to have stumbled upon this booster for all aspects of life, so I can do more of everything else, for even more decades than I had expected.
I wish this same type of good fortune for you, however you create it.
In the Comments: Do you have questions about hormone replacement or anything else in this article? I’ll try to invite Kevin, Dr. Sean Bender and other knowledgeable people to contribute and answer questions as well.
Is testosterone therapy safe- Take a breath before you take the plunge – Harvard Health (2024)Cardiovascular Safety of Testosterone Therapy (aka the TRAVERSE Study) (2023)TRT – Association with Mortality in High Risk Subgroups (2023)Bolt Health website – if you do decide to go with this company, be sure to ask for their best discount even though it’s not related to me.
General
⚖️ Neutral
🌐 Moneycrashers
#21698. TurboTax Experts for Business Review – Sole Props, S Corps & Partnerships, Not C Corps
📅 17 Nov 2026 • ⏱️ 7m • 📚 Deep Dive (1381 w)
TurboTax Experts for Business Review – Sole Props, S Corps & Partnerships, Not C Corps
📅 17 Nov 2026 | ⏱️ 7 min read (1381 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~7 mins left to finish
📖 0% read
💡 Key Takeaways
- Use TurboTax Experts for Business if you’re a sole proprietor or run an S corp or partnership and want a tax expert to check your return or prepare it.
- It has been revealed that for a business owner, the business return is the hardest part of tax season to do alone.
- Recent findings suggest that turboTax belongs to Intuit, which began operating in 1983 and is based in Mountain View, California.
Use TurboTax Experts for Business if you’re a sole proprietor or run an S corp or partnership and want a tax expert to check your return or prepare it. For an S corp, doing the entry yourself in Expert Assist Business costs less than half what Full Service charges. A C corporation can’t use it, so hire a CPA.
It has been revealed that for a business owner, the business return is the hardest part of tax season to do alone. A sole proprietor adds Schedule C, the form that reports business profit, to a personal return. An S corporation’s Form 1120-S and a partnership’s Form 1065 are due a month before personal returns, each with a Schedule K-1 that reports every owner’s share of the profit. TurboTax Experts for Business lets you prepare that return with an expert on call, or hand it to an expert who prepares, signs, and files it.
Recent findings suggest that turboTax belongs to Intuit, which began operating in 1983 and is based in Mountain View, California. TurboTax brought Intuit $5.3 billion in revenue in the fiscal year that ended July 31, 2026. TurboTax states it has more than 10,000 business tax experts and matches each owner with one who knows the owner’s industry. The experts report an average of 13 years of tax experience. The prices below are the ones it still listed in mid-November 2026, for 2025 returns, since it hadn’t yet posted prices for 2026 returns.
TurboTax prices each tier by the return your business files. Expert Assist and Full Service both include unlimited expert help by phone, chat, or one-way video, from 5 a.m. to 9 p.m. Pacific time every day of tax season.
You prepare the return yourself in TurboTax Online and contact an expert whenever a question comes up, from entering income and expenses to finding the deductions your industry can take. Before you file, an expert can review the whole return with you. Last season’s prices were:.
Those prices held for sole proprietors who filed by March 31 and for S corps and partnerships that filed by April 30, with late-season prices after that. If your return needs so much help that the expert ends up preparing it, IRS rules can require the expert to sign as preparer, and TurboTax’s terms say you may then have to switch to Full Service.
A dedicated expert matched to your industry starts with a video call, prepares the return, and walks you through it before signing and filing. Last season, an S corp or partnership return cost $1,549, plus $69 for each state. A sole proprietor’s price started at $249, which TurboTax states covers a W-2, Form 1040, Schedule C, and quarterly tax estimates. More forms cost more, and you get an estimate before work begins. Sole proprietors can also meet their expert in person at one of TurboTax’s Expert offices.
According to recent reports, for a sole proprietor with just a W-2 and a Schedule C, Full Service started only $20 above Expert Assist, $249 against $229, though its price rises as forms are added. For an S corp or partnership, handing off the return cost $910 more, $1,549 against $639. Since Expert Assist already includes an expert to ask and a final review, that $910 buys the expert’s time doing the preparation.
Industry observers note that full Service won’t do your bookkeeping, though. TurboTax’s terms require fully reconciled books, meaning records that match your bank and card statements, and let the expert refuse to start until they do. They also limit Full Service to businesses with a December 31 year-end, and new customers can’t use it for a business’s final return. If you can’t finish by the deadline, your expert files Form 7004, the IRS’s extension request for business returns, which adds six months.
This tier is a subscription for sole proprietors and single-member LLCs (limited liability companies) who want one expert all year. Your expert reconciles your books in QuickBooks each quarter and works out your quarterly estimated tax payments. You also get quarterly planning sessions, a check on whether another business structure would cut your taxes, and your return filed through Full Service at no extra cost. TurboTax’s terms leave tax planning out of its other tiers.
It costs $99 a month, including a QuickBooks Simple Start subscription billed alongside it, or $1,069 billed yearly, which TurboTax notes saves $119. You can try it free for 30 days. It’s open only to owners new to QuickBooks, and an S corp and partnership version at $199 a month is listed as coming soon. The estimates leave out sales and payroll taxes, and canceling brings no refund for the rest of the billing period.
Sources indicate that experts for Business prepares Schedule C for sole proprietors and single-member LLCs, Form 1120-S for S corps, and Form 1065 for partnerships and multi-member LLCs. It won’t prepare Form 1120, the return a C corporation files to pay its own income tax, or one for a business taxed as a C corporation. Trusts and estates, nonprofits, and returns needing more than five state filings are out too.
In a recent development, A C corporation that wants a professional needs a CPA or another paid preparer. One doing its own return can use TurboTax Business, TurboTax’s Windows desktop software, which prepares C corporation, trust, and estate returns as well as S corp and partnership returns. It has no expert to ask, and TurboTax’s audit support guarantee doesn’t cover it.
Sources indicate that S corp and partnership returns come due early. The IRS’s tax calendar puts their deadline on the 15th day of the third month after the tax year ends. For a business whose tax year ends December 31, the 2026 return is due Monday, March 15, 2027, and Form 7004 extends that six months. TurboTax’s pages still showed March 16, the 2026 deadline, which fell a day late because March 15, 2026, was a Sunday. A sole proprietor’s Schedule C is due with the personal return on April 15.
It has been revealed that the owner’s personal return belongs to TurboTax’s personal software. A sole proprietor can also get expert help on Schedule C there, in Expert Assist Premium, which listed at $209 last season against $229 for Expert Assist Business. S corp and partnership owners who file the business return first get 20% off one 2026 personal federal return in TurboTax Online, state fees excluded.
Recent findings suggest that turboTax backs business returns with what it calls the Business Tax Guarantee, and S corp and partnership returns add representation in an audit. Each piece covers something different:.
Audit Defense has limits of its own. TaxAudit’s membership terms rule out businesses with more than $5 million in gross receipts, meaning total sales before costs. They also cover income tax audits only, not payroll or sales tax audits, and they don’t include representation in court.
TurboTax Experts for Business is a good fit for a sole proprietor or a small S corp or partnership that wants an expert to check or prepare its return. A sole proprietor with a simple Schedule C should check the Full Service price first, since it started just $20 above Expert Assist’s last season. An S corp or partnership gets the better value from Expert Assist Business, with an industry-matched expert, a final review, and Audit Defense for $639, against $1,549 for Full Service.
Industry observers note that it’s the wrong fit for a C corporation, which needs a CPA or desktop software, and for owners whose books aren’t reconciled. S corp and partnership owners who keep their own books should open an Expert Assist Business return well before the March 15, 2027 deadline.
Learn more about TurboTax Experts for Business.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
It has been revealed that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every tech giant or offer available in the marketplace.
General
⚖️ Neutral
🌐 Moneycrashers
#21697. TurboTax Experts Review – In-Person Tax Prep at the Online Price, Plus Per-Form Fees
📅 17 Nov 2026 • ⏱️ 7m • 📚 Deep Dive (1335 w)
TurboTax Experts Review – In-Person Tax Prep at the Online Price, Plus Per-Form Fees
📅 17 Nov 2026 | ⏱️ 7 min read (1335 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~7 mins left to finish
📖 0% read
💡 Key Takeaways
- According to recent reports, book TurboTax Experts if you want a tax expert to prepare and sign your return face to face and one of its 500-plus offices is near you.
- According to recent reports, turboTax built its name on software you fill in yourself.
- Intuit, founded in 1983 and based in Mountain View, California, added 200 TurboTax offices for the 2026 filing season, and its office finder now lists more than 500.
According to recent reports, book TurboTax Experts if you want a tax expert to prepare and sign your return face to face and one of its 500-plus offices is near you. It costs what TurboTax’s experts charge online, but the starting price covers one W-2 and a Form 1040, so get every form priced before the expert starts.
According to recent reports, turboTax built its name on software you fill in yourself. Its offices work the other way around. You sit down with a TurboTax expert and hand over your documents, and the expert prepares the return, reviews it with you, signs it as the preparer, and files it.
Intuit, founded in 1983 and based in Mountain View, California, added 200 TurboTax offices for the 2026 filing season, and its office finder now lists more than 500. TurboTax customers gave Expert Full Service 4.8 out of 5 in more than 108,000 reviews from 2026, posted on TurboTax’s own site. The Better Business Bureau gives Intuit an F, citing 35 complaints the firm didn’t answer and 32 it didn’t resolve, out of more than 4,600 filed against Intuit in the past three years.
TurboTax sells this as Expert Full Service, the product it also offers online, with the meeting moved to an office.
TurboTax Expert offices take appointments only and stay open year-round. The office finder lists more than 500, from 72 in California to one each in states such as Alaska, Maine, and Oregon, and none in Vermont or Wyoming. TurboTax counts an in-person expert as local when the office is within 50 miles of your ZIP code, and if you’d rather meet online, it matches you with an expert in your state.
It has been revealed that turboTax stores take walk-ins as well as appointments. You can drop in with a question, start your return yourself with an expert’s guidance, or hand it off. Intuit’s February 2026 announcement listed stores in six metro areas: Latest York, Los Angeles, Chicago, Seattle, Dallas, and Phoenix. Hours vary by location, and TurboTax indicates its local service runs nights and weekends during tax season.
Every return starts at a federal base price that covers one W-2 and one Form 1040, and in person you pay from the same price list as online. TurboTax’s Full Service price list sets that base at $129 late in the season and after April 1, and at $89 early in the season, without saying when early season ends. Each state return adds $69, or $49 early. Most other forms carry a fee of their own.
By our math, a homeowner with a mortgage and one W-2 who itemizes deductions and files one state return pays $318 late in the season. That’s the $129 base plus $40 for the mortgage interest form, $80 for Schedule A, and $69 for the state. Early in the season, the same return costs $258.
Sources indicate that your expert gives you an estimate before starting, based on what you report and the documents you upload, and confirms any change with a final price before filing. You pay nothing until the expert files, and you can leave at any point before you pay. Paying the fee out of your refund can add $40 more.
Sources indicate that turboTax doesn’t publish the credentials of the expert you’ll get. Its blog notes its expert community includes CPAs, enrolled agents (tax specialists the IRS licenses), and other experienced tax experts, so the person preparing your return may hold no credential at all. The years of experience on its pages are self-reported.
The credential matters if the IRS questions your return. Under IRS rules, CPAs, enrolled agents, and attorneys can represent you on any matter, while other preparers can do so only in limited cases or not at all. You can look up a preparer’s credential in the IRS’s Directory of Federal Tax Return Preparers.
Sources indicate that turboTax matches you with an expert by your location and tax situation. You can’t pick one by name, but you can ask for a fresh match at any time, and you can request the same expert next year if they still work for Intuit and are available.
TurboTax’s Expert Full Service Guarantee covers the expert’s work. If your expert’s error as the signed preparer leads to a penalty or interest charge from the IRS or your state, TurboTax pays it, though you still owe any extra tax. If another preparer later files an amended return that gets you a bigger refund or a smaller tax bill, TurboTax refunds what you paid for Full Service.
TurboTax also guarantees its calculations, your maximum refund, and audit support for the seven-year life of the return. Audit support means one-on-one answers from a tax professional, and TurboTax won’t represent you before the IRS. For representation, you’d buy Audit Defense, a separate add-on from TaxResources, Inc.
Industry observers note that the first meeting is a free consultation, in person or online, where an expert reviews your situation and answers your questions with no commitment to file. Filing with TurboTax then takes five steps.
Sources indicate that bring a government-issued ID for each person on the return if you blueprint to file at the appointment. Same-day filing needs every document uploaded first and depends on the expert’s schedule.
After you file, the office stays your tax contact all year, for consultations, prior-year returns, amended returns, and IRS notices. An amended return on Form 1040-X carries no form fee.
TurboTax sells the same service online, where your expert works with you by phone, message, or one-way video, in which you see the expert but the expert can’t see you. The price list and guarantees don’t change, so the office is worth the trip only when a face-to-face meeting matters to you.
TurboTax’s own software lets you file a simple return free or fill in a harder one yourself, and its Expert Assist tiers add an expert who answers questions and reviews the return before you file.
H&R Block starts in-office preparation at $99 plus a state fee, against TurboTax’s $129 late-season base plus its own. Its offices also take walk-ins, which TurboTax leaves to its stores. Choosing between TurboTax and H&R Block also comes down to their software and online help, not only their offices.
Sources indicate that IRS-certified volunteers at Volunteer Income Tax Assistance sites prepare returns for free, generally for people who make about $70,244 or less, though each site may set its own limit. Every return they prepare gets a quality review before it’s filed.
Sole proprietors can use TurboTax Experts, since Schedule C is part of the personal return, but an S corporation’s or a partnership’s own return goes to a separate product, TurboTax Experts for Business.
In a recent development, turboTax Experts puts a tax preparer across the desk for what TurboTax charges for the same work online. You see a quote before the expert starts, pay only once the return is filed, and have TurboTax cover the penalties its expert’s errors cause, from an office that stays open after April.
In a recent development, it’s a poor fit for a simple return that free software or a volunteer site would handle, and for anyone who wants a CPA or an enrolled agent by name. Book the free consultation if an office is near you, and ask for the price with every form you’ll file before the expert starts.
Learn more about TurboTax Experts or see how it compares to the best free online tax software.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every firm or offer available in the marketplace.
🔗 Related Articles
📰 #21704. H&R Block Review – Free for Simple Returns, With Tax Pros Online or in Person 📰 #21698. TurboTax Experts for Business Review – Sole Props, S Corps & Partnerships, Not C Corps 📰 #21696. QuickBooks Online Review – The Accounting Software Your Accountant Knows, at a Higher Price
AI & Tech
⚖️ Neutral
🌐 Moneycrashers
#21696. QuickBooks Online Review – The Accounting Software Your Accountant Knows, at a Higher Price
📅 17 Nov 2026 • ⏱️ 6m • 📚 Deep Dive (1265 w)
QuickBooks Online Review – The Accounting Software Your Accountant Knows, at a Higher Price
📅 17 Nov 2026 | ⏱️ 6 min read (1265 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- It has been revealed that choose QuickBooks Online if your accountant already works in it or your business tracks inventory or projects.
- It has been revealed that picking accounting software is mostly a decision about who else will work in your books.
- Industry observers note that quickBooks Online is the cloud accounting software Intuit sells to small businesses.
It has been revealed that choose QuickBooks Online if your accountant already works in it or your business tracks inventory or projects. Prepares with accountant access cost $38 to $340 a month after three discounted months, so if you mostly send invoices, a cheaper plan or app does that for less.
It has been revealed that picking accounting software is mostly a decision about who else will work in your books. If a bookkeeper or accountant closes your books each month or files your business return, using the program they already know saves time on both sides. If nobody else logs in, you pay for collaboration you never use.
Industry observers note that quickBooks Online is the cloud accounting software Intuit sells to small businesses. Intuit, founded in 1983 and based in Mountain View, California, also makes TurboTax and notes about 100 million customers use its products. It says 650,000 accountants worldwide use its platform, and every proposal from Simple Start up includes free logins for two or three of yours. QuickBooks customers are also paying more. Intuit’s fiscal 2026 results, for the year that ended July 31, 2026, show QuickBooks Online Accounting revenue up 23%. Intuit said the fourth quarter’s 20% gain came from customers paying more on average, more customers, and changes in which plans they buy.
QuickBooks Online comes in six plans. QuickBooks Free and QuickBooks Lite are for one person working alone, while the four business plans, Simple Start through Advanced, add accountant access and, from Essentials up, more users. Each business strategy includes everything in the one below it, so your choice comes down to how many people need logins and whether you track inventory or projects.
Fresh customers on a monthly proposal choose between 50% off for 3 months and a 30-day free trial, then pay the plan’s current price each month until they cancel, with no annual contract. By our math, the discount saves $70 in year one. Over the first 12 months, Plus costs $1,470 with it (three months at $70, then nine at $140) and $1,540 with the trial (11 paid months at $140).
Not every business needs Simple Start. If you mostly send invoices, QuickBooks Lite handles them for $20 a month without accountant access, and Wave’s free Starter blueprint covers unlimited invoices, estimates, bills, and bookkeeping records. If your team needs more logins but no inventory tracking, compare Xero, which charges no per-user license fees.
It has been revealed that every strategy pulls in transactions from the bank and card accounts you connect, one bank on Free and two on Lite. From Simple Start up, QuickBooks copies the categories you choose and applies them to newly introduced transactions automatically. Intuit Intelligence, Intuit’s name for its AI tools, does more at each level:.
Intuit still calls Intuit Intelligence a beta release, so its features and limits can change. You choose which tasks run on their own and can undo what the AI did. Only admin users get the chat, and each initiative caps how much they can use it each month.
Industry observers note that quickBooks Free caps invoices at two a month unless you qualify for and turn on QuickBooks Payments, which lets customers pay an invoice by card or bank transfer. Payments has no monthly fee, but each transaction costs:.
Recent findings suggest that bill pay comes with every business proposal. Intuit’s plan pages list five free standard ACH bill payments a month, an allotment they say may vary, and $0.50 for each one after that. Its Bill Pay page calls standard ACH free on every plan, so confirm the fee with Intuit before you pay more than five vendors a month that way. Checks cost $1.50, and Faster ACH, which usually arrives the next business day, costs $10. For $15 a month, Bill Pay Premium adds AI bill entry and unlimited e-filing of the 1099 forms you send contractors. Bill Pay Elite, at $45 a month, adds approval workflows and user roles, and it has come free with Advanced since Aug. 1, 2026.
Inventory and job costing start at Plus. Plus updates quantities on hand automatically, alerts you when an item needs reordering, drafts purchase orders, and turns them into bills when the goods arrive. Its project tools track labor, payroll, and expenses for each job, and it adds budgets and up to 40 classes and locations for sorting income and expenses. Advanced lifts that limit and adds custom reports and dashboards, two-way syncing with Excel, and an estimates-versus-actuals report for projects.
In a recent development, no QuickBooks Online proposal includes payroll. Intuit sells it separately as QuickBooks Workforce, at a monthly base fee plus a fee for each employee:.
Latest customers pay half the base fee for three months, but per-employee fees stay at full price. At full price, a five-person team on Workforce Payroll pays $85 a month, $50 plus $35 in employee fees.
Expert Assisted, at $59 a month after a 30-day free trial, gives you a bookkeeping expert to answer questions but not to work in your books. Full-Service Bookkeeping, with a dedicated bookkeeper doing the monthly work, starts at $300 a month after a one-time cleanup fee, and a cleanup alone starts at $600. Neither service prepares or files your taxes.
Phone support comes with every business initiative and is free during the trial, while QuickBooks Free gets chat. Advanced adds Priority Circle, a premium support line with on-demand training. The Better Business Bureau (BBB) gives Intuit an F, citing complaints it failed to answer or resolve. It logged more than 4,600 complaints against Intuit in the last three years, nearly 2,000 of them in the past 12 months. Those counts cover all of Intuit’s products, TurboTax and Mailchimp included, not QuickBooks alone.
Sources indicate that leaving QuickBooks takes planning. The Export data tool saves your reports and lists to a single .zip of Excel files. Estimates, purchase orders, attachments, and your chart of accounts (the list of categories your books use) export separately, and Intuit’s help page names two ways out, Excel or QuickBooks Desktop. After you cancel a paid initiative, you keep read-only access for a year to finish exporting. Cancel during or after a free trial, and Intuit keeps your data for 90 days.
QuickBooks Online is the safe pick when someone besides you works in the books. Your accountant gets in free, Plus handles inventory and job costing, and the account grows to 25 users on Advanced without a move. On the higher intends, its AI now does real cleanup and reconciliation work.
It’s poor value for a one-person business that mostly sends invoices. Simple Start’s $38 a month buys accountant access and reports that business won’t use, while QuickBooks Lite handles invoicing for $20 and Wave for nothing. The discounted price also doubles after the third month, and payroll costs extra. If your accountant already works in QuickBooks, pick the proposal that covers your headcount and budget for its full price from the fourth month.
Learn more about QuickBooks Online or see how it compares to the best online bookkeeping services.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every manufacturer or offer available in the marketplace.
General
⚖️ Neutral
🌐 Goodfinancialcents
#21695. The Truth About Systeme.io: Game-Changer or Just Another Gimmick?
📅 08 Jan 2024 • ⏱️ 13m • 📚 Deep Dive (2503 w)
The Truth About Systeme.io: Game-Changer or Just Another Gimmick?
📅 08 Jan 2024 | ⏱️ 13 min read (2503 words, 📚 Deep Dive) | Source: Goodfinancialcents
⏱️ ~13 mins left to finish
📖 0% read
💡 Key Takeaways
- Home » Make Money » The Truth About Systeme.io: Game-Changer or Just Another Gimmick?
- Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
- The GFC® Money Expert Review Board is a team of financial experts who provide independent, unbiased reviews of financial products...
Home » Make Money » The Truth About Systeme.io: Game-Changer or Just Another Gimmick?
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance...
The GFC® Money Expert Review Board.
The GFC® Money Expert Review Board is a team of financial experts who provide independent, unbiased reviews of financial products...
GoodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® has an advertising relationship with the companies included on this page. All of our content is based on objective analysis, and the opinions are our own. For more information, please check out our full disclaimer and complete list of partners.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Fresh York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
GoodFinancialCents® partners with outside experts to ensure we are providing accurate financial content.
These reviewers are industry leaders and professional writers who regularly contribute to reputable publications such as the Wall Street Journal and The Upcoming York Times.
Our expert reviewers review our articles and recommend changes to ensure we are upholding our high standards for accuracy and professionalism.
Our expert reviewers hold advanced degrees and certifications and have years of experience with personal finances, retirement planning and investments.
Systeme.io has burst onto the digital marketing scene, brandishing a bold claim as an all-in-one, free platform.
Let’s face it, when you hear something like that, your first thought is, “This has got to be too good to be true.”.
That was my initial reaction too. A free, do-it-all software that doesn’t suck? Highly doubtful.
But here’s the shocker: Systeme.io isn’t just blowing smoke. It’s a game-changer. As someone who’s navigated the maze of digital marketing tools, I was prepared for disappointment. Yet, Systeme.io left me floored with its capabilities.
It has been revealed that take it from someone who’s been around the block with the likes of ConvertKit, AWeber, and MailChimp. These giants lure you in with free offerings, only to tighten the screws when your audience grows. Then there’s WordPress.org – great for setting up a blog, but it’s like climbing Everest if you’re a newbie.
In a recent development, systeme.io, on the other hand, is a beast of a different nature. Offering highly effective landing pages and robust sales funnels with professional templates for free? That’s unheard of. It’s like stumbling upon a treasure chest in your backyard.
My first foray into landing page software was with ClickFunnels, an undeniably powerful tool. But once the 14-day trial evaporates, you’re staring down the barrel of a $100 monthly fee. Worth it if you’re a pro, but a gut punch for beginners.
Yes, you can test it out 100% completely FREE.
And when the time comes to open your wallet, it’s less than $30 a month – an absolute steal for the arsenal of tools you’re getting.
Absolutely. It’s a diamond in the rough, especially for those just starting their digital marketing journey. For the veterans, it might not have the same allure, but for the rookies, it’s a godsend. Forget the skepticism; Systeme.io is a disruptor that’s here to stay.
The platform serves a multifaceted purpose, aiming to simplify the digital marketing process. It’s designed for entrepreneurs and businesses seeking an integrated solution for email marketing, sales funnels, website building, and more.
The importance of such a tool lies in its ability to streamline various marketing tasks, which are often scattered across different platforms, into one cohesive system.
The user interface of Systeme.io? It’s okay, but let’s not sugarcoat it. For a newbie who’s never dabbled in sales funnels or email campaigns, it can feel like being thrown into the deep end. It’s not the sleek, intuitive experience that tech gurus might rave about. But, and this is a significant but, Systeme.io doesn’t just leave you hanging.
The saving grace here is their tutorials. These are goldmines for beginners. They walk you through the process, breaking down what could be an overwhelming experience into manageable chunks. So, while the interface might not win any beauty contests, the support system in place is BIG help.
According to recent reports, at the core of Systeme.io are several key features that make it a comprehensive digital marketing solution. These include email marketing capabilities, sales funnel creation tools, a website builder, options for hosting membership sites, and affiliate program management.
Each of these features is designed to work seamlessly with the others, providing a unified experience. For instance, the email marketing service is notably efficient, rivaling established providers like ConvertKit, AWeber, and MailChimp, especially with its free subscription model that remains functional up to a certain point.
Here’s a sample template they offer for their email campaigns:.
Here’s a breakdown of all the features Systeme.io offers:.
And if here’s a fancy table to help simplify it even more:.
When we talk about the cost-effectiveness of Systeme.io, we’re looking at a platform that offers a substantial suite of features without the hefty price tag that usually accompanies such versatility.
According to recent reports, for starters, Systeme.io’s freemium model is a standout in the digital marketing space (click here to open a free account today). You can manage up to 2,000 contacts and create three sales funnels without spending a penny. This is a significant advantage for entrepreneurs and small businesses where every dollar counts.
Sources indicate that to put this into perspective, let’s compare it with some industry counterparts. Platforms like ClickFunnels and Kartra, while offering robust functionalities, start their pricing at around $97 to $99 per month after their trial periods. This can be a steep investment for those just starting out.
In contrast, Systeme.io not only allows you to test the waters for free but also keeps the costs low even when you upgrade. Their paid plans, offering a broader range of features, start at less than $30 a month.
This pricing strategy makes advanced digital marketing tools accessible to a wider audience, breaking down the financial barriers that often hinder small businesses and startups.
In a recent development, the all-in-one nature of Systeme.io is its hallmark. It consolidates various marketing tools into one cohesive platform. This integration means you can manage email campaigns, build sales funnels, create websites, and even run affiliate programs without having to switch between different software. For many users, this integration simplifies the digital marketing process significantly, allowing for a more streamlined workflow.
However, it’s important to recognize that while Systeme.io covers a broad spectrum of functionalities, it may not offer the same depth as specialized standalone tools in each specific area.
For instance, while its email marketing capabilities are robust, they might not have the advanced features of a dedicated email marketing service.
Similarly, its website builder is competent for basic to intermediate needs, but it might not satisfy users looking for highly advanced web design features.
Industry observers note that systeme.io aims to be user-friendly, and for the most part, it achieves this goal. The interface is designed to be intuitive, especially for those who have basic familiarity with digital marketing tools. However, for complete beginners, there can be a learning curve.
It has been revealed that the platform offers a range of tutorials and support materials, which are invaluable for newly introduced people. I’ve watched (and rewatched) several of these tutorials to lean how to use their software.
These resources are designed to help users navigate through the initial complexity and make the most out of the platform’s features.
Sources indicate that let’s get real about customization in Systeme.io. It’s got a decent selection of templates and the interface won’t make you pull your hair out, but if you’re looking to really dive deep into customization, you might hit a wall.
It has been revealed that for those who have grand visions of a highly unique and tailored digital presence, Systeme.io can feel a bit like playing with kid gloves. It’s great for getting you up and running, but for the more ambitious or specific design needs, it’s not quite the creative playground you might be looking for.
Industry observers note that now, onto scalability. Systeme.io is like that compact car that’s perfect for city driving but struggles a bit on the open highway. For small businesses or solo entrepreneurs just starting out, it’s a match made in heaven. But as your business grows and your needs become more complex, Systeme.io might start to feel a bit cramped.
In a recent development, this is especially true for larger businesses or those niche ventures that need more than just the basics. As you scale up, you might find yourself needing more sophisticated tools and features that Systeme.io doesn’t offer.
Plus, when it comes to playing nice with other tools or services you might be using, Systeme.io isn’t always the most cooperative. It works well within its own confines but doesn’t always reach out to others easily.
Here’s a quick rundown on the pros and cons of Systeme.io.
In a recent development, when compared to competitors, Systeme.io’s pricing is highly competitive. For instance, platforms like ClickFunnels offer powerful functionality but at a higher cost, typically starting at around $100 per month after a free trial. This can be a significant investment, especially for latest entrepreneurs or small businesses.
In contrast, Systeme.io’s paid aims, which provide access to a broader range of features, are more affordable, starting at less than $30 a month.
Comparative Analysis with Other Tools.
To provide a broader perspective, let’s compare Systeme.io with other popular tools in the market:.
According to recent reports, this comparison demonstrates that while Systeme.io offers a comprehensive suite of tools at an affordable price, platforms like HubSpot and Kartra provide more advanced features in certain areas but at a higher cost. ClickFunnels, on the other hand, is more expensive but offers highly customizable funnel-building capabilities.
Sources indicate that user reviews and testimonials play a crucial role in understanding the real-world effectiveness of Systeme.io. Many consumers have shared success stories, highlighting how the platform has helped them streamline their marketing efforts and grow their businesses.
Upon reviewing their Trustpilot account, you can see the experience with Systeme.io is remarkable. Right now, there are 3,635 reviews with an average rating of 4.9. That is outstanding!
However, it’s also crucial to consider critiques and common issues raised by customers. Some have pointed out the limitations in customization and scalability, as mentioned earlier. These critiques are valuable for potential users to set realistic expectations and for the platform’s developers to identify areas for improvement.
I currently have accounts with Systeme.io, Click Funnels, and Kajabi. To show you how they compare here’s a look at 3 different landing pages I’ve created each of them.
Here is a landing page I created with Systeme.io:.
In comparison, here’s an older landing page I create with Click Funnels….
And just because I love showing you variety, here’s a landing page created in Kajabi..
In a recent development, when you factor in both Click Funnels and Kajabi only offer free trials (around 14 days) and you have to start paying after that, the Systeme.io funnel becomes THAT more attractive. Here’s a look at some of the templates they offer for free:.
In essence, while Systeme.io is a fantastic starting point for new online businesses, offering a solid foundation and easy-to-use tools, it’s not the endgame for everyone.
As your business evolves, you might outgrow its capabilities and start looking for something that offers a bit more room to stretch your entrepreneurial legs.
It’s a great launchpad, but for those on a path to rapid growth or with highly specific needs, keep in mind that you might need to eventually graduate to more advanced tools.
Industry observers note that systeme.io is an all-in-one online business platform. It's designed to handle everything from email marketing and sales funnels to website building and running affiliate programs.
Systeme.io is an all-in-one online business platform. It's designed to handle everything from email marketing and sales funnels to website building and running affiliate programs.
Sources indicate that yes, to an extent. Systeme.io offers a free blueprint that lets you manage up to 2000 contacts, create three sales funnels, and more, without paying a dime. It's like a test drive before you decide to buy the car.
Yes, to an extent. Systeme.io offers a free plan that lets you manage up to 2000 contacts, create three sales funnels, and more, without paying a dime. It's like a test drive before you decide to buy the car.
It has been revealed that you'll need to start paying when your needs exceed the free plan's limits. This means if you grow beyond 2000 contacts or need more than three sales funnels. The paid aims start at under $30 a month, which is a bargain for what you're getting.
You'll need to start paying when your needs exceed the free strategy's limits. This means if you grow beyond 2000 contacts or need more than three sales funnels. The paid plans start at under $30 a month, which is a bargain for what you're getting.
It has been revealed that absolutely. It's user-friendly and great for those who are new to digital marketing tools. There's a learning curve, but the platform offers helpful tutorials to guide you through.
Absolutely. It's user-friendly and great for those who are latest to digital marketing tools. There's a learning curve, but the platform offers helpful tutorials to guide you through.
Trustpilot (n.d.) Systeme.io Reviews https://www.trustpilot.com/review/systeme.io.
Jeff Rose, CFP® is a Certified Financial Planner™, founder of Good Financial Cents, and author of the personal finance book Soldier of Finance. He was a financial planner for 16+ years having founded, Alliance Wealth Management, a SEC Registered Investment Advisory firm, before selling it to focus on his passion - educating the masses on the importance of financial freedom through this blog, his podcast, and YouTube channel. Jeff holds a Bachelors in Science in Finance and minor in Accounting from Southern Illinois University - Carbondale. In addition to his CFP® designation, he also earned the marks of AAMS® - Accredited Asset Management Specialist - and CRPC® - Chartered Retirement Planning Counselor. While a practicing financial advisor, Jeff was named to Investopedia's distinguished list of Top 100 advisors (as high as #6) multiple times and CNBC's Digital Advisory Council. Jeff is an Iraqi combat veteran and served 9 years in the Army National Guard. His work is regularly featured in Forbes, Business Insider, Inc.com and Entrepreneur.
🔗 Related Articles
📰 #22234. The Creality Falcon T1C engraver could be a game changer for personalisation businesses 📰 #21261. Tech Report: “My Husband & I Just Had A Threesome With Another Woman” & 57 Other Anonymous Mom Confessions 📰 #17006. Is the game funny, or just the players? Jackbox CEO indicates they get 'a lot of false positives' with a staff of comedy writers
General
⚖️ Neutral
🌐 Explorersweb
#21694. Industry News: Alaska to Patagonia, One Summit at a Time
📅 19 Oct 2026 • ⏱️ 3m • 📚 Deep Dive (574 w)
Industry News: Alaska to Patagonia, One Summit at a Time
📅 19 Oct 2026 | ⏱️ 3 min read (574 words, 📚 Deep Dive) | Source: Explorersweb
⏱️ ~3 mins left to finish
📖 0% read
💡 Key Takeaways
- According to recent reports, since 1972, Alaska to Patagonia has been a classic cycling route of 30,000km or more.
- The 23-year-old endurance athlete is not only pedaling the distance but also climbing the highest peak in each of the 35 countries he passes through.
- It has been revealed that northern lights.
According to recent reports, since 1972, Alaska to Patagonia has been a classic cycling route of 30,000km or more. At any given time, several ambitious cyclists are attempting it. But no one is doing it quite like Tobias Renggli of Lucerne, Switzerland.
The 23-year-old endurance athlete is not only pedaling the distance but also climbing the highest peak in each of the 35 countries he passes through. And although it’s part of the marketing rather than the adventure, the imagery so far — shot both by Renggli and by a film production group he belongs to called the Black Forest Collective — is stunning for such a difficult journey.
It has been revealed that northern lights. Photo: Tobias Renggli.
Industry observers note that despite his age, this is not Renggli’s first adventure. In 2022, at the age of 18, he cycled all 44 European countries within seven months, climbing the highest peak of each and camping every night. In 2024, he climbed the highest mountains of all 26 Swiss cantons in about three weeks.
Sources indicate that subzero cycling. Photo: Tobias Renggli.
Sources indicate that renggli began in April from Deadhorse, Alaska, on the shores of the Beaufort Sea — still deep winter at that latitude, though the long Arctic days had returned. Pedaling 1,200km in temperatures as low as -30˚C, he made his way to Talkeetna, then skied in for eight days while pulling a sled.
Industry observers note that he then summited 6,190m McKinley with his occasional partner, Heli Hofmann — the first party atop the peak this year, which meant they had to break trail through the deep snow. It took them 36 days.
According to recent reports, next, it was onto 5,959m Mount Logan, Canada’s highest peak. Again with Heli Hofmann but no guide, they summited in late June. This time, they were the last party of the year to summit Logan.
According to recent reports, renggli then cycled with another friend to Vancouver, took a two-week break after covering 3,000km and summiting two of the hardest peaks he would encounter, then continued alone through the U.S. Typically, he cycles 100 to 160km per day, with some shorter days.
Recent findings suggest that in Seattle. Photo: Tobias Renggli.
Industry observers note that unlike most Trans-America cyclists, he chose to take Baja California rather than mainland Mexico. Crossing Baja was more difficult than expected. He described temperatures exceeding 40°C and a 120km stretch toward Loreto that he began with only two liters of water.
In Death Valley. Photo: Tobias Renggli.
Later, near Ciudad Insurgentes, thunderstorms flooded the roads. At night, he carried his bicycle through a fast-moving, thigh-deep flood while vehicles turned back.
According to recent reports, renggli had intended to take no motorized transportation, only sailboats when confronted with water — he also wants to climb 12 high points in the Caribbean. However, this is such a massive undertaking that he’s not being too strict on himself. Although he skied into Denali, for example, he flew back out to Talkeetna. And from La Paz in Baja, he caught the ferry to Mazatlan on the mainland and continued from there.
Details have been sparse since Baja, but Renggli recently crossed into Guatemala. Presumably, he climbed 5,636m Pico de Orizaba before leaving Mexico and is now headed to 4,220m Volcán Tajumulco, Guatemala’s highest peak. He has been on the road for 202 days.
Reggli’s route and current location.
🔗 Related Articles
📰 #22686. Industry News: Tate Britain spotlights Bloomsbury artists Vanessa Bell and Duncan Grant for the first time since 1999 📰 #22043. A 30-Day Beginner Fitness Proposal That Won’t Overwhelm You (One Quest at a Time) 📰 #21986. Industry News: Running for Time vs. Distance: Experts Explain Which Is Better for Your Goals
General
⚖️ Neutral
🌐 Moneycrashers
#21693. Zoe Financial Review – Free Matches With Vetted Fiduciaries, if You Have $150,000
📅 17 Nov 2026 • ⏱️ 8m • 📚 Deep Dive (1538 w)
Zoe Financial Review – Free Matches With Vetted Fiduciaries, if You Have $150,000
📅 17 Nov 2026 | ⏱️ 8 min read (1538 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~8 mins left to finish
📖 0% read
💡 Key Takeaways
- Use Zoe Financial if you have $150,000 or more to invest and want screened fiduciary advisors to interview at no cost.
- Industry observers note that picking a financial advisor means trusting a stranger with your savings, and the title alone tells you nothing about their training, their fees, or who else pays them.
- Zoe is a Upcoming York investment adviser, formed in 2016 and registered with the Securities and Exchange Commission (SEC) since 2019.
Use Zoe Financial if you have $150,000 or more to invest and want screened fiduciary advisors to interview at no cost. The advisor you hire pays Zoe, and the SEC fined it in 2026 for not fully disclosing why some advisors got its referrals, so check each match’s fees and record yourself.
Industry observers note that picking a financial advisor means trusting a stranger with your savings, and the title alone tells you nothing about their training, their fees, or who else pays them. Zoe Financial screens advisors for you and sets up calls with as many as three of them at no charge, because the advisor you hire pays Zoe instead.
Zoe is a Upcoming York investment adviser, formed in 2016 and registered with the Securities and Exchange Commission (SEC) since 2019. Its founder and CEO, Andres Garcia-Amaya, holds the Chartered Financial Analyst (CFA) charter and was a global market strategist at J.P. Morgan Asset Management. Zoe began matching people with advisors in 2018 and now runs that service at FindAnAdvisor.com as the Zoe Network. In 2023 and 2024 the network held between about 128 and 225 advisory firms, by the SEC’s count. Its Trustpilot profile indicates a 4.7 rating from 92 reviews, six of them from the past year. In September 2026, Zoe settled SEC charges over how it disclosed the conflicts behind its referrals.
According to recent reports, zoe’s service has three parts: the match, the screening behind it, and the investing platform Zoe’s advisors use for clients’ accounts. Matching and screening cost you nothing, but Zoe charges fees on the platform that can land on your bill.
Sources indicate that A two-minute form asks about your household income, your goals, what you own, and your ZIP code. Zoe’s algorithm then suggests up to three advisors, and you book free calls to interview them, though Zoe’s SEC brochure notes that some people get a single name.
Recent findings suggest that A concierge team books the calls and looks for a better fit if the first names miss. You’re never obligated to hire anyone, and most advisors in the network work remotely, so where you live doesn’t narrow the list.
The form doesn’t weigh your tolerance for risk or your full finances, the brochure claims, so the calls are where you judge fit.
According to recent reports, zoe sets no minimum to use the form, but its advisors take clients with at least $150,000 in investable assets and $100,000 in income, and some set a higher bar. Its average client has more than $750,000. With less to invest, a robo-advisor, an automated service that manages a fund portfolio for a small yearly fee, usually fits better. So do the kinds of advisors paid a flat fee or by the hour, whose fees don’t grow with your portfolio.
Sources indicate that zoe says every advisor in its network holds a Certified Financial Planner (CFP) certification, the CFA charter, or a certified public accountant (CPA) license, with five or more years of experience and a clean SEC record. Each is a fiduciary, legally bound to put your interests first, and Zoe says its matches don’t sell commission-paying products, such as some annuities and insurance policies.
Its SEC brochure describes a looser test. Zoe checks that a firm centers on financial planning, that some of its advisors hold a credential such as the CFA, CFP, or CPA, or a graduate business degree, and that it has no material disciplinary history. It reviews each advisor’s regulatory filings and rereads every firm’s brochure once a year.
What Zoe doesn’t check is how an advisor performs once you’ve hired one. Before your first call, look up each match’s record yourself. Ask, too, whether the advisor is fee-only, paid by you alone, since not every fiduciary is.
It has been revealed that zoe’s third step, after the form and the calls, is opening your accounts on its investing platform, debuted in 2023. Advisors in its referral program join by invitation and must keep a minimum level of client assets there, so expect the advisor you hire to suggest it.
Industry observers note that those are brokerage accounts held by Apex Clearing, which keeps the assets and settles the trades, and opened through Zoe’s sister brokerage, Zoe Securities. Trades in stocks, exchange-traded funds (ETFs), and mutual funds carry no commission. Your advisor can choose ready-made model portfolios from firms such as BlackRock, Vanguard, and State Street. The platform rebalances them automatically and can harvest tax losses, selling investments at a loss to offset taxable gains.
The accounts are yours, so leaving an advisor means moving them to another firm or hiring another advisor who uses Zoe’s platform.
Zoe doesn’t publish what its advisors charge, so the fee schedule each match hands you is the number to compare.
Zoe’s site notes you won’t pay to use its platform, while its client relationship summary, filed with the SEC, says you or your advisor will. Ask each match to put every fee, Zoe’s included, on the agreement you sign.
Say a match charges 1% a year, the rate Zoe’s own fee guide uses in its examples. On $150,000, that’s $1,500 a year, and on $750,000, it’s $7,500, before fund expenses or platform fees.
Recent findings suggest that zoe’s satisfaction guarantee is narrower than its FAQ makes it sound. The FAQ promises a refund of all advisor fees if you’re unhappy, but the terms cap it at one billing period of fees, a month’s or a quarter’s worth. You qualify only after three months of full advisory service, must ask within a 24-month window between hiring and leaving the advisor, and get nothing back for one-time or hourly planning.
When you hire a match, that advisor pays Zoe 15% to 35% of the fee it charges you, Zoe’s solicitation disclosure claims. Zoe collects that share for as long as you stay when the fee is a percentage of your assets, and for five years of a flat-fee planning arrangement. Some advisors pay a one-time referral fee instead. On a $7,500 yearly fee, Zoe’s share would come to $1,125 to $2,625 a year.
Zoe’s contracts bar advisors from charging referred clients more, so you’d pay the same fee walking in on your own. To screen advisors yourself, the National Association of Personal Financial Advisors (NAPFA) keeps an online directory of fee-only advisors you can sort by how they charge.
Recent findings suggest that that pay gives Zoe reasons to favor some advisors. Its share differs by firm, and some advisors pay just to join the network. Several advisory firms, Creative Planning and Mariner Wealth Advisors among them, own small stakes in Zoe, and some of its owners are in the network. Zoe’s own advisory arm competes for the same referrals, and Zoe earns platform fees from advisors who use its platform. Zoe claims its algorithm weighs none of this.
The SEC found that referrals didn’t always work that way. In a settled order of September 28, 2026, the agency said that in 2023 and 2024 Zoe didn’t tell users it had a financial stake in steering them to advisors using its upcoming platform. As that period went on, Zoe told advisors who wouldn’t adopt the platform that they’d be dropped from the network. It also found that Zoe’s statement that referrals rested solely on users’ answers was misleading, since salespeople often suggested other advisors. Clients who hired a network advisor in that period picked one the algorithm hadn’t first suggested about 46% of the time.
Zoe agreed, without admitting or denying the findings, to be censured, to stop such violations, and to pay a $450,000 penalty. It says it has since told salespeople not to recommend advisors of their own and hired a full-time chief compliance officer. Ask whoever books your calls how each advisor made your list.
In a recent development, zoe Financial is a sound starting point for anyone with $150,000 or more who wants a fiduciary advisor and doesn’t know where to begin. It narrows the field to screened, credentialed firms, books the interviews, and costs you nothing, and its contracts keep its cut of your advisor’s fee off your bill.
It’s a poor fit below that bar, and for anyone who wants a referral with no money riding on the outcome, since Zoe earns more from some advisors than others and the SEC found it didn’t fully disclose that. Treat each match as a candidate, not a recommendation. Ask why the advisor made your list, get the full fee schedule in writing with any platform fees on it, and check the record before you sign.
Learn more about Zoe Financial or see how it compares to the best financial advisors.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Recent findings suggest that advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every organization or offer available in the marketplace.
General
⚖️ Neutral
🌐 Choosefi
#21692. Virgin Atlantic — Cheap Short-Haul Europe in Business
📅 05 Nov 2026 • ⏱️ 15m • 📚 Deep Dive (2977 w)
Virgin Atlantic — Cheap Short-Haul Europe in Business
📅 05 Nov 2026 | ⏱️ 15 min read (2977 words, 📚 Deep Dive) | Source: Choosefi
⏱️ ~15 mins left to finish
📖 0% read
💡 Key Takeaways
- Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
- Business class hops across Europe for fewer points than most domestic economy awards.
- In a recent development, picture this: you've just crossed the Atlantic on a long-haul award, touched down at London Heathrow, and now you need to get to Rome for the real adventure to begin.
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
Business class hops across Europe for fewer points than most domestic economy awards.
In a recent development, picture this: you've just crossed the Atlantic on a long-haul award, touched down at London Heathrow, and now you need to get to Rome for the real adventure to begin. Most travelers at this point resign themselves to a cramped economy seat on a budget carrier, dragging luggage through a secondary terminal. But you? You're walking into the Virgin Atlantic clubhouse, sipping a Bloody Mary, and then settling into a proper business class seat for the 2.5-hour hop to Fiumicino. That's the magic of this redemption. Here's the math that should make your jaw drop. A business class seat on a short-haul European flight — London Heathrow to Rome, London to Athens, London to virtually any major European city — routinely retails for **$1,000 to $3,000 in cash**. Airlines know that business travelers on these routes are often on corporate accounts and will pay whatever it costs. The leisure traveler simply doesn't book business class on a two-hour flight because it feels absurd. And that's exactly the pricing inefficiency the ChooseFI community learns to exploit. Virgin Atlantic's Flying Club prices these short-haul European business class seats at a flat **17,500 miles one-way**. At the low end of that $1,000–$3,000 cash range, you're already extracting **5.7 cents per point** — well above what most programs deliver. At the high end, when those seats spike to $3,000 on peak travel dates, you're looking at a staggering **17.1 cents per point**. For context, most travel rewards experts consider 1.5–2 cents per point a solid redemption. This one can deliver *ten times* that. What makes this feel particularly right for the FI mindset is the positioning angle. This isn't just a standalone splurge — it's the finishing move on a transatlantic trip you've already largely funded with points. You've landed in London. You need to get to your final European destination. Instead of paying $200 for a budget airline seat that charges extra for your carry-on, you drop 17,500 Virgin miles and arrive refreshed, fed, and ready. The opportunity cost of those miles is low; the experiential upgrade is enormous. This is what travel rewards done right looks like: not flying business class because you're wealthy, but because you understood the system better than the airlines expected you to.
The core insight here is understanding how Virgin Atlantic prices its own metal versus partner awards — and then deliberately choosing the right one for the right job.
Virgin Atlantic's Flying Club is famous in the points community for two things. First, its partner award sweet spots: ANA First Class for as low as 55,000–60,000 miles one-way, Delta One at competitive rates. These are the headline acts. But quietly sitting in the same award chart is a genuinely underappreciated gem — Virgin's own short-haul European business class, priced at a flat 17,500 miles regardless of the specific route within that distance band.
In a recent development, why does Virgin price it this way? Virgin Atlantic operates as a premium carrier and sets its award chart to reflect aspirational redemptions — the kind that make Flying Club membership feel worthwhile. For long-haul routes on their own metal, their pricing is competitive but not exceptional. For short-haul Europe, however, the fixed pricing creates an opportunity: a two-hour flight to Rome or Athens costs the same 17,500 miles as a cheaper, shorter hop, but those premium routes have cash prices that routinely spike into the thousands. The chart wasn't built to be a loophole — it's just that cash prices for short-haul business class in Europe are genuinely volatile and often extraordinary.
The fuel surcharge reality check. Here's where you need to pay close attention. Virgin Atlantic is known for passing fuel surcharges onto award redemptions on their own flights. This is the opposite of what happens on ANA or Delta partner awards booked through Flying Club (which carry zero surcharges). On a short-haul European route, those surcharges are real but typically far more manageable than on a transatlantic segment — often in the $50–$150 range rather than $500+. The CPP math still works strongly in your favor, but you should go in with eyes open: this is not a zero-cash-outlay redemption.
The transfer path is exceptional. This is where the ChooseFI community has a serious structural advantage. Virgin Atlantic Flying Club accepts transfers from essentially every major points currency:.
Every major transferable currency gets you there at a 1:1 ratio with instant speed. That means if you're holding Chase points from your Sapphire Reserve or Preferred, Amex points from your Gold or Platinum, or Citi points from your Premier card, you have a direct, frictionless pipeline to 17,500 Virgin miles within minutes of finding availability. This is critical because, as you'll learn in the booking section, Virgin availability on its own short-haul European routes can be limited, and you want to be able to move fast when a seat opens up.
In a recent development, the booking window opens 331 days in advance — use it. Miles don't expire as long as you have account activity within 36 months, so there's no pressure to burn them before you're ready.
Free calculator reveals when you could reach financial independence — plus a savings rate tracker, expense audit, and more.
Before you touch a single website, clarify your mission: you're looking for Virgin Atlantic-operated business class availability on short-haul European routes departing from London Heathrow (LHR). This is not a search for partner award space — this is VS metal, VS availability, VS seats. Your most common target routes will be LHR → FCO (Rome), LHR → ATH (Athens), and similar European city pairs. Build your itinerary around where VS actually flies in Europe, not every possible destination.
Go to virginatlantic.com and use the award search tool. Select "Book with miles" and enter your route. Virgin shows its own availability directly here — you don't need a third-party search engine for this specific redemption. Search one-way rather than round-trip so you can see each direction independently. If your target dates show no availability, flex by ±3 days. Business class award seats on short-haul routes are typically released in small batches.
It has been revealed that open a second browser tab and search the same route and date on Google Flights or directly on virginatlantic.com for a revenue ticket. Note the cash price for business class. This is your CPP sanity check — if the cash price is $1,200 and you're spending 17,500 miles plus ~$100 in surcharges, you're at roughly 6.3 cents per point. If the cash price is $2,500, your CPP jumps dramatically. This step helps you prioritize which dates to target.
Do NOT transfer points until you have confirmed award availability on your target date. Transfers to Virgin are one-directional and cannot be reversed.
According to recent reports, once you've confirmed a seat is available, transfer your points from your chosen program. For Chase, Amex, Citi, and Bilt transfers, the miles land in your Flying Club account instantly. Refresh your Flying Club account, confirm the miles are there, and complete the booking before the seat disappears. Enter your payment details for the taxes and surcharges (typically $50–$150 on short-haul European routes).
Virgin Atlantic operates its own short-haul flights from London Heathrow to destinations across Europe including Amsterdam, Paris, Edinburgh, Geneva, and Athens. These are different from partner codeshare flights. The 17,500-point price applies specifically to Virgin Atlantic-operated short-haul business class. Partner flights (booked through Flying Club but operated by Delta, KLM, or Air France) use a different award chart and typically cost significantly more. When searching, filter for Virgin Atlantic flight numbers (VS prefix) to find the sweet spot pricing. The business class product on short-haul includes a dedicated cabin, lounge access at Heathrow, priority boarding, and meal service.
Recent findings suggest that card links may earn ChooseFI a commission. See our advertiser disclosure.
According to recent reports, ready to unlock a world of free travel? Start with the Chase Sapphire Preferred® Card.
$95 annual fee | Earn 75,000 bonus points.
According to recent reports, side hustlers! With the Ink Business Preferred® Credit Card you can earn free travel from your business expenses.
$95 annual fee | Earn 100,000 bonus points.
The Capital One Venture Rewards Credit Card can be used to offset almost any travel expense.
$95 annual fee | Earn more than $1,000 in Travel Bonuses with a limited-time $300 Capital One Travel stays credit, plus earn 75,000 bonus miles once you spend $4,000 on purchases within the first 3 months of account opening—that's more than $1,000 in travel value.
According to recent reports, chooseFI has partnered with CardRatings for our coverage of credit card products. ChooseFI and CardRatings may receive a commission from card issuers.
Let's walk through a real scenario that illustrates exactly what this redemption looks like in practice.
The Setup: You've just arrived at London Heathrow on a transatlantic award — perhaps an ANA First Class redemption through the very same Flying Club program. You have a few days in London, and now you need to get to Athens, Greece, where your Mediterranean adventure begins. You check flights: a business class seat on Virgin Atlantic's LHR → ATH route on your target date is priced at $2,200 cash.
The Experience: On the day of travel, you access the Virgin Clubhouse at Heathrow — one of the most celebrated airport lounges in the world. The cocktail bar, the à la carte dining, the spa treatments available before departure — this is the part that makes the ChooseFI community members shake their heads in disbelief when they first experience it. Then you board and settle into Virgin's short-haul business class: a proper dedicated seat, a full meal service, attentive cabin crew. For a two-and-a-half-hour flight, it's a genuinely elevated experience.
You land in Athens refreshed, fed, and without having spent thousands of dollars. That's the positioning flight done right — and it's what separates travelers who understand the travel rewards system from those who are still paying cash for European business class.
It has been revealed that do this: Use it as a positioning flight on a broader trip This redemption was practically designed for trip architecture. If you're already planning a transatlantic journey — coming into London on a long-haul award — the 17,500-mile European hop becomes the natural, high-value conclusion. You're not just booking a short flight; you're completing a fully points-funded journey across two continents. Think of this as the last domino.
Sources indicate that do this: Compare cash prices before transferring Not all dates are created equal. A Tuesday in November to Rome might retail for $800 in business class — still a reasonable 4.6 CPP — while the same route on a Friday in July might hit $2,800, delivering 17+ CPP. Run the cash price check on Google Flights before you commit your miles. Target the high-cash-price windows for maximum value extraction.
Avoid this: Transferring points before confirming availability This is the single most common mistake. Transferring miles to Virgin Atlantic is a one-way street. If you send 17,500 Chase points over and then discover the seat isn't actually available (or you misread the cabin class), those miles are stuck in Flying Club. Always — always — confirm the specific flight and cabin availability first, THEN transfer.
Sources indicate that avoid this: Confusing this with partner award bookings Virgin's zero-surcharge policy applies to partner airlines like ANA and Delta. On Virgin Atlantic-operated flights (which this redemption is), expect fuel surcharges of $50–$150. Budget for these. They don't destroy the CPP math, but they're a genuine cash cost you need to plan around.
Do this: Hold Virgin miles for multiple redemptions Because miles don't expire with account activity every 36 months, there's no reason to hoard and rush. Keep Flying Club active by earning miles through their shopping portal or partners, and wait for the right route and cash price moment to pounce.
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
This redemption is built for a specific type of ChooseFI traveler: the intermediate-to-advanced points strategist who thinks in itineraries, not individual flights.
The ideal candidate is someone who's already planning a trip that routes through London Heathrow — perhaps on a transatlantic award — and needs an elegant, high-value way to reach their final European destination. Solo travelers and couples benefit most here. At 17,500 miles per person, a couple needs 35,000 Virgin miles, which is completely achievable with a single transfer from a combined Chase or Amex balance.
Sources indicate that families should approach with caution. This redemption scores a 2/5 for family-friendliness for good reason. Multiplying 17,500 miles per person across four or more travelers creates a significant points requirement, and availability for multiple seats on the same flight is far from guaranteed. The fuel surcharges also multiply with passenger count. Families are better served by other redemption strategies.
Minimum requirements to attempt this:.
This is NOT for beginners. The overall score of 2.7/5 and beginner-friendliness rating of 1/5 signal real complexity. If you're just starting your travel rewards journey, build your foundation with simpler redemptions first. But if you've got a year of points accumulation behind you and you're ready to think architecturally about trip planning, this sweet spot can be a revelatory experience.
It has been revealed that this redemption is rated **Hard** — and that rating is earned honestly. The difficulty isn't in the math or the concept; it's in three very real execution challenges. **Challenge 1: Finding award availability.** Virgin Atlantic doesn't release enormous quantities of business class award seats on its own short-haul European flights. You may search a dozen dates before finding a seat. This is the primary friction point. The fix: use the 331-day advance booking window religiously, and be genuinely flexible on your travel dates by at least ±3 days. **Challenge 2: Navigating the Virgin Atlantic booking interface.** Compared to programs like Chase's travel portal, Flying Club's award search tool is clunkier and less intuitive. It occasionally demonstrates availability that isn't actually bookable through to completion. The fix: search virginatlantic.com directly, be patient with the interface, and have your payment information ready to move promptly when a seat surfaces. **Challenge 3: Understanding the surcharge reality.** Fresh points enthusiasts sometimes expect zero out-of-pocket on award bookings. Virgin's fuel surcharges on its own metal are real, and they'll surprise you if you're not expecting them. The fix: budget $50–$150 per person in cash costs as a baseline assumption. The good news: the **transfer path is as easy as it gets** in the points world. Instant 1:1 transfers from Chase, Amex, Citi, and Bilt mean that once you find availability, you can have miles in your account and a booking confirmed in under 10 minutes. If you're willing to invest the search time and approach with patience, this is one of those redemptions that fundamentally changes how you see the travel rewards system. The payoff — business class in Europe for 17,500 miles — is worth the effort.
In a recent development, this redemption works best as part of a larger trip. If you are flying transatlantic to or from Europe, route through London Heathrow. Then use the short-haul award to connect to your final European destination at a fraction of the cost of a separate ticket.
Midweek flights (Tuesday through Thursday) and shoulder season dates offer the best availability. Peak summer weekends and holiday periods are harder to find. Build flexibility into your schedule if possible.
Chase Ultimate Rewards transfers to Flying Club are instant, making Chase the preferred transfer partner for time-sensitive bookings. Amex Membership Rewards also transfers 1:1 but may take 1-2 days.
Complete the booking on VirginAtlantic.com. Your business class ticket includes access to the Virgin Atlantic Clubhouse at Heathrow, one of the best airport lounges in Europe. Arrive early and enjoy it as part of the experience.
Industry observers note that virgin Atlantic operates short-haul flights from London Heathrow to destinations including Amsterdam, Paris CDG, Edinburgh, Geneva, Athens, Tel Aviv, and several others. Routes change seasonally, so check VirginAtlantic.com for current schedules. The 17,500-point sweet spot applies to all Virgin Atlantic-operated short-haul business class flights.
Sources indicate that yes, Virgin Atlantic Flying Club prices awards as one-way, so you can book a single short-haul business class segment for 17,500 points. This makes it ideal for positioning flights where you only need one direction covered by points.
The flight itself is short, but the value extends beyond the seat. You get dedicated check-in, priority boarding, the Heathrow Clubhouse lounge (which is excellent), a meal service, and a more relaxed travel experience. At 17,500 points, the per-point value (3-5 cents) makes it a strong redemption even for a short flight.
Recent findings suggest that virgin Atlantic does add taxes and fees to award tickets, including some carrier-imposed surcharges. On short-haul European routes, total out-of-pocket costs typically run $50-$150 depending on the route and departure airport taxes. This is higher than some programs but still reasonable given the business class product.
This sweet spot was last verified over 90 days ago. Award availability and pricing may have changed — verify current rates before booking.
The Virgin Atlantic short-haul European business class sweet spot is the perfect complement to a transatlantic award trip. At just 17,500 points, it costs less than most domestic economy awards while delivering business class service, Heathrow Clubhouse lounge access, and a stress-free connection to destinations across Europe. It is not the flashiest redemption in travel rewards, but it is one of the most practical: a building block that makes multi-city European itineraries accessible and affordable for the FI community.
General
⚖️ Neutral
🌐 Explorersweb
#21691. Tech Report: Australian Grandfather Attempts 1,650Km River Swim
📅 20 Oct 2026 • ⏱️ 2m • 📖 Standard (338 w)
Tech Report: Australian Grandfather Attempts 1,650Km River Swim
📅 20 Oct 2026 | ⏱️ 2 min read (338 words, 📖 Standard) | Source: Explorersweb
⏱️ ~2 mins left to finish
📖 0% read
💡 Key Takeaways
- Australian grain farm manager Scott Gladman, 63, is attempting to swim the length of the Darling River, Australia’s third-longest river.
- In a recent development, gladman started on September 1 from near Brewarrina in far north Upcoming South Wales.
- Recent findings suggest that interestingly, the expedition is not born from a love of endurance swimming.
Australian grain farm manager Scott Gladman, 63, is attempting to swim the length of the Darling River, Australia’s third-longest river. It begins in Newly introduced South Wales and finishes at its confluence with the Murray River at Wentworth. Gladman believes he will be the first person to swim the entire 1,650km route.
In a recent development, gladman started on September 1 from near Brewarrina in far north Upcoming South Wales. At the outset, he budgeted 103 days to complete the swim, averaging around 16km per day. So far, he is largely on track. After 49 days, he has covered 660km, leaving just under 1,000km to go.
Recent findings suggest that interestingly, the expedition is not born from a love of endurance swimming. Gladman was inspired to find a fundraising challenge to support friends impacted by Motor Neuron Disease and Progressive Supranuclear Palsy, a rare form of Parkinson’s. Initially, he considered the Murray. “I just thought I could swim the Murray River, but people have done that,” he told ABC News. “No one has had a crack at the Darling.”.
Industry observers note that the location of the Darling River in Australia. Photo: Wikimedia Commons.
Gladman gave himself 18 months to train. In the summer, he swam in the Murray River at Boundary Bend, Victoria, and during winter he completed laps in indoor pools. Now out on the Darling, a support boat of family and friends keeps him company, alongside a canoeist.
“There’s no real form of communication, and I wear earplugs…he’ll [the canoeist] either have to hit me on the back of the head with a paddle to get my attention, or he’ll just start steering toward me, and that will push me one way or the other,” Gladman said.
According to recent reports, despite its length, the Darling River is sometimes so shallow that Gladman needs to float through sections on his back, or walk. The support boat also sometimes requires saving, with Gladman having to help clear a path through river debris:.
🔗 Related Articles
📰 #23230. Tech Report: 350 tech jobs hammered as TCS takes over work at iconic Australian retailer 📰 #19190. Tech Report: The Best Airbnbs in Amsterdam, From Canal Houses to a Boat on the Amstel River 📰 #23660. Tech Report: Gabe Newell praised for how he runs his $500m superyacht as it blows expert away
General
⚖️ Neutral
🌐 Moneycrashers
#21690. Kraken Review – One Account for Crypto, Stocks & Pro Trading
📅 17 Nov 2026 • ⏱️ 7m • 📚 Deep Dive (1418 w)
Kraken Review – One Account for Crypto, Stocks & Pro Trading
📅 17 Nov 2026 | ⏱️ 7 min read (1418 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~7 mins left to finish
📖 0% read
💡 Key Takeaways
- Open a Kraken account if you want crypto, U.S.
- Industry observers note that buying crypto in a simple app is easy but costly.
- In a recent development, kraken is the trading name of Payward Inc., founded in 2011, and it says more than 13 million people worldwide trust it.
Open a Kraken account if you want crypto, U.S. stocks, and pro-grade trading under one login, from an exchange that publishes proof of reserves. Place your regular buys on Kraken Pro rather than the app, whose 1% fee and built-in spread make it the account’s costliest way to trade.
Industry observers note that buying crypto in a simple app is easy but costly. Trading on an exchange’s order book, the live list of buy and sell offers, costs less but takes more know-how, and stocks usually sit at a separate brokerage. Kraken puts all three behind one login, so the decision that matters is where you place each trade.
In a recent development, kraken is the trading name of Payward Inc., founded in 2011, and it says more than 13 million people worldwide trust it. In the U.S., it’s licensed to transfer customers’ money in 46 jurisdictions and offers stock trading through Kraken Securities, a broker-dealer registered with the Securities and Exchange Commission (SEC). It also publishes proof-of-reserves reviews, which check that it holds the crypto its clients’ balances show, a practice it says it began in 2014.
The account has five parts: a simple app, a pro exchange, stock trading, ways to earn on idle coins, and two companion apps.
According to recent reports, the Kraken app is the simple side of the account. You buy, sell, or convert crypto at the price it quotes, set recurring buys daily, weekly, or monthly on more than 200 coins, and pay by bank transfer, debit card, or PayPal. Kraken states it lists more than 600 cryptocurrencies, though it restricts 83 of them for U.S. clients. The app suits investors who buy now and then and don’t want to learn an order book.
According to recent reports, kraken Pro, on the same login, is the full exchange, with stop-loss and take-profit orders, charts with 25-plus trading and data widgets, a desktop app, and API access for your own trading software. Eligible U.S. traders can also trade on margin, borrowing against their crypto for positions worth up to 20 times their collateral on some coins, and trade perpetual futures, contracts with no expiration date. Both run through Kraken Derivatives US, a futures broker registered with the Commodity Futures Trading Commission (CFTC), and Kraken warns that margin losses can exceed what you put up.
Industry observers note that the Kraken app and Kraken Pro also trade more than 11,000 U.S.-listed stocks and exchange-traded funds (ETFs) with no commission, through Kraken Securities, in every state Kraken serves. Orders placed outside market hours wait for the next session, Kraken Pro adds trading 24 hours a day on weekdays, and Kraken charges nothing on its end to move shares in from another broker.
Once you switch it on, Auto Earn stakes eligible idle coins, committing them to help run their blockchains in return for rewards. It pays weekly and keeps the coins free to trade or withdraw, and on coins that make you wait to unstake, it pays rewards on up to half of what you stake. Bonded staking pays more for locking coins up for a set term.
It has been revealed that rates on the biggest coins are low. Kraken estimates Auto Earn’s annual percentage yield (APY) at 0.02% for bitcoin and 1.47% for ether, before its commission. DeFi Earn puts USDC, a stablecoin pegged to the dollar, into vaults that lend it on blockchain lending markets for up to 5.33% APY, though the rate floats, the product isn’t regulated, and you can lose money.
Industry observers note that kraken Wallet is a free self-custody app, meaning you hold the keys to your coins instead of Kraken, on Bitcoin, Ethereum, Solana, and other networks. Krak, a separate money app, sends money free between Kraken owners and lets you spend through the Krak Card, a Visa debit card from Lead Bank. The card pays up to 2% cash back, at a rate set by the average assets you hold across Krak, Kraken, and Kraken Pro, and because Krak isn’t a bank, its balances carry no FDIC deposit insurance.
It has been revealed that the app’s convenience is the account’s biggest cost. Every app price includes a spread, a markup over the market rate that Kraken doesn’t publish and may keep, on top of these fees.
It has been revealed that counting fees alone, since Kraken doesn’t publish the app’s spread, here is what $500 of bitcoin a month costs by our math. The app charges $5 a month, or $60 a year. Kraken+ costs $59.88 a year on monthly billing, so it pays off once app trades top about $500 a month, or about $417 on the annual blueprint. Kraken Pro charges $2 for the same buy as a maker order or $4 as a taker order, and Kraken states Pro prices carry no hidden spread.
Sources indicate that if you want only bitcoin or ether as a long-term slice of a portfolio, a spot exchange-traded product (ETP) is the main alternative. It holds the coin itself and trades on a stock exchange, so you skip the crypto wallet and keys, though you pay the fund’s sponsor an ongoing fee that direct holders don’t.
Kraken says no custodial wallet it manages has been breached since its founding in 2011, and it keeps most client crypto offline, in cold storage in guarded facilities. Accounts sign in with passkeys and two-factor authentication and can’t be recovered by text message.
An independent accountant’s proof-of-reserves review for Sept. 30, 2026, found Kraken held 103.2% of its clients’ bitcoin and 100.7% of their ether. Kraken notes that such a review can’t rule out hidden claims on the coins or prove they weren’t borrowed, and it covers only the coins it names, not dollar balances.
In a recent development, crypto at Kraken carries neither FDIC deposit insurance nor the brokerage protection of the Securities Investor Protection Corporation (SIPC). Stocks are different. Kraken Securities is a member, and SIPC covers up to $500,000, including $250,000 in cash, if a member brokerage fails, though never market losses.
Sources indicate that kraken’s record with regulators is mixed. In 2023 it paid $30 million to settle SEC charges over its old U.S. staking program and shut that program down, relaunching U.S. staking as a new product in 2025. A separate SEC lawsuit claiming Kraken ran an unregistered securities exchange was dismissed for good in 2025.
Industry observers note that kraken serves every state except Newly introduced York and Maine, and some features run on shorter lists. Staking is open only in 37 states, Washington, D.C., and Puerto Rico, which by our count leaves out 11 states Kraken otherwise serves, including California, Texas, Illinois, and New Jersey. The Krak Card isn’t offered in Massachusetts or Indiana, and Krak’s cash transfers aren’t available in Indiana, Louisiana, Massachusetts, or Utah. Margin and perpetual futures go only to traders who meet Kraken’s eligibility rules.
Sources indicate that support runs around the clock by live chat and email, with phone calls only in select cases. Kraken calls you only after you’ve contacted it and arranged the call, so treat any other call, or a Kraken number found in a search ad, as a scam. Of Kraken’s 9,583 reviews on Trustpilot, 49% give one star and 33% give five, for a TrustScore of 3.1 out of 5.
Kraken is a strong pick for investors who want crypto, U.S. stocks, and serious trading tools in one account. Its best case is Kraken Pro’s low fees beside the beginner app, backed by proof of reserves and a clean custody record.
It’s the wrong account for Latest York and Maine residents, who can’t open one, and for anyone in the 11 other states without staking who wants rewards on idle coins. Long-term holders who want only bitcoin or ether can own them through a spot ETP instead. Everyone else should open the account and route regular buys through Kraken Pro, or add Kraken+ once app trades top about $500 a month.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every tech giant or offer available in the marketplace.
General
⚖️ Neutral
🌐 Explorersweb
#21689. Seven Alpine-Style Climbs Happening Now in Nepal
📅 20 Oct 2026 • ⏱️ 3m • 📚 Deep Dive (636 w)
Seven Alpine-Style Climbs Happening Now in Nepal
📅 20 Oct 2026 | ⏱️ 3 min read (636 words, 📚 Deep Dive) | Source: Explorersweb
⏱️ ~3 mins left to finish
📖 0% read
💡 Key Takeaways
- It has been revealed that several small teams are attempting difficult climbs on Nepal’s 6,000 and 7,000m peaks.
- This is what we know about the ongoing expeditions:.
- Recent findings suggest that three young French climbers, members of the Military High Mountain Group from Chamonix, celebrated their organization’s 50th anniversary with a latest route on Peak 41.
It has been revealed that several small teams are attempting difficult climbs on Nepal’s 6,000 and 7,000m peaks. Unfortunately, they rarely report on their intends or progress until they return, and often only if they succeed.
This is what we know about the ongoing expeditions:.
Recent findings suggest that three young French climbers, members of the Military High Mountain Group from Chamonix, celebrated their organization’s 50th anniversary with a latest route on Peak 41. This 6,654m mountain is located in the Khumbu region and is often called the “true Mera Peak.”.
Konrad Piontek, Amaury Fouillade, and Clovis Paulin took advantage of a good weather window and achieved the first ascent of the peak’s northeast face. They climbed in an alpine-style single push over four days. The result is a beautiful 1,400m line with difficulties up to ED+ 5+ M6 A1 90°. They descended via the southeast face. The team named their line Bon Matin (good morning).
It has been revealed that nivel Meroi and Romano Benet are acclimatized and ready to attempt a new route on Jugal II, but the Italian couple will be on their own. Tine Cuder of Slovenia, the third team member, has left due to illness.
Meanwhile, in the Kangchenjunga region, a large Russian team has also finished acclimatizing. The team trekked in the area and crossed a number of high-altitude passes, the latest of them at the top of an icefall at 5,750m. They reported lots of snow above 5,000m but are ready to attempt a new route on the formidable Jannu (7,710m) from its southeast side.
The team comprises Ivan Artemov, Ivan Volkov, Artem Zhdanov, Konstantin Neumoin, Roman Shilin, and Vasily Yagodin.
Hidesuke Taneishi and Tetsu Hashimoto of Japan traveled to Nepal in September, aiming to achieve the first ascent of Gangapurna West (7,455m), also known as Asapurna or Peak Lachenal. They have provided no news since, but they probably had to retreat when an intense snowstorm hit the Annapurna region three weeks ago.
It has been revealed that location of Gangapurna West on a Google Earth screenshot. Notes by Lindsay Griffin for the American Alpine Journal.
Industry observers note that meanwhile, a second team has reached the base of the peak with the same objective. Valery Shamalo, Natalia Zanina, Maksim Trufanov, and Ruslan Kirichenko arrived at the beginning of October and saw no one else there. They reported that recent precipitation had left the trail in a poor state; the climbers had to cross landslides and swollen rivers to reach base camp.
The team has completed two acclimatization climbs, looking for a passage through the icefall at the base of the mountain and then a series of couloirs. They reached 5,900m and, on a second trip, 6,600m. Deep snow covered the peak, which slowed progress. Finally, they launched a summit bid last week.
From 6,600m, they spent a day on technical ice sections of 70–80º. In poor visibility, they endured spindrift and were showered by small ice chunks.
Recent findings suggest that “In the afternoon, the weather deteriorated sharply,” Natalia Zanina stated. “Heavy snowfall began, and we started being struck by large, continuous avalanches. At 6,800m (340m from the summit), we decided to turn back.”.
A note on names: according to 8000ers.com, Asapurna should be the correct name for this peak because — although it is closer to Gangapurna — Asapurna’s summit ridge connects directly to Annapurna III.
The list of climbing permits granted by Nepal’s Ministry of Tourism points to some other interesting expeditions, some of them in remote western Nepal. There is a permit for Nyalu Kang (6,265m), only opened to foreign climbers in 2024 and reportedly unclimbed, and Ardang, summited once by Canadians Bryce Kendall and Sunny Twelker in 2019. Victor Saunders and Mick Fowler of the UK attempted Ardang last year.
General
⚖️ Neutral
🌐 Moneycrashers
#21688. Latest Update: Monarch Money Review – Every Household Account in One Shared App, for $99.99 a Year
📅 17 Nov 2026 • ⏱️ 6m • 📚 Deep Dive (1289 w)
Latest Update: Monarch Money Review – Every Household Account in One Shared App, for $99.99 a Year
📅 17 Nov 2026 | ⏱️ 6 min read (1289 words, 📚 Deep Dive) | Source: Moneycrashers
⏱️ ~6 mins left to finish
📖 0% read
💡 Key Takeaways
- Pay for Monarch Money if you want your household’s budget, bills, investments, and net worth in one app you and a partner both use, since a partner joins the $99.99-a-year Core proposal free.
- Monarch Money’s CEO, Val Agostino, was among the first product managers at Mint, the free budgeting app Intuit later shut down.
- Sources indicate that monarch sells two aims, Core and Plus.
Pay for Monarch Money if you want your household’s budget, bills, investments, and net worth in one app you and a partner both use, since a partner joins the $99.99-a-year Core proposal free. Skip Plus, at $199.99, unless you’ll use its retirement forecasts or track a side business.
Monarch Money’s CEO, Val Agostino, was among the first product managers at Mint, the free budgeting app Intuit later shut down. He started the tech giant in 2019 alongside Ozzie Osman and Jon Sutherland. The company now calls its app simply Monarch, and by October 2026 it had more than 1 million members. The app holds 4.9 stars from about 119,000 ratings on Apple’s App Store and 4.8 stars from about 26,000 reviews on Google Play.
Sources indicate that monarch sells two aims, Core and Plus. Everything in this section comes with Core, and the pricing section below covers what Plus adds.
Industry observers note that monarch offers two ways to budget, and you can switch between them. Flex budgeting, the default, sorts expenses into fixed, flexible, and non-monthly groups and has you watch one number, the flexible spending you have left this month. Category budgeting sets a limit for each category, such as groceries or dining out. Either way, Monarch drafts your first budget from your last six months of spending.
It builds each month’s budget on the income you expect, while YNAB has you budget only money that has already arrived. Leftover money in a category can roll over to the next month, which is how Monarch handles once-a-year bills, and alerts warn you before you overspend.
Transactions arrive already sorted into categories, and rules let you correct what the sorting gets wrong. As transactions come in, a rule can match on the merchant, amount, category, or account, then rename the merchant, change the category, add tags, split the charge, or hide it from your budget. The Recurring page finds bills and subscriptions in your history and reveals them as a calendar or a list, with reminders before each charge.
Monarch tracks each investment you hold, not just account balances, across stocks, mutual funds, exchange-traded funds, 401(k)s, and crypto. It highlights how your portfolio splits among stocks, bonds, cash, and other assets and how it has done against the S&P 500. It can also track equity compensation, the stock or options your employer pays you.
Net worth, what you own minus what you owe, refreshes as your linked balances and market prices change. A home’s value can come from Zillow’s estimate and a car’s from VinAudit, crypto can link straight from Coinbase, and anything else goes in as a manual account. U.S. members can add a VantageScore 3.0 credit score from Equifax, which updates monthly and doesn’t affect your credit.
Sources indicate that A save-up goal tells you whether you’re on track from your balance, your target date, and what you strategy to add each month. A pay-down goal projects a payoff date for each debt, and its calculator compares the avalanche method, which pays the highest interest rate first, with the snowball method, which pays the smallest balance first. Goals sit inside the budget, so you see what goes to them each month.
Adding a partner costs nothing, and each person gets a separate login under the one subscription. Every member sees every linked account and transaction, though, and Monarch’s help center says accounts and transactions can’t be hidden from one another. You can mark each as shared or as one person’s to filter transactions, reports, and accounts, but the household keeps one budget.
If you pay for your own subscription, you can also give a financial planner a year of access at no extra cost and revoke it anytime. The planner can view and edit what you see but can’t link accounts for you. A planner in Monarch’s professional program can instead pay for your subscription, at $14.99 a month per client.
Reports cover spending, income, and cash flow, and you can filter them by category, merchant, account, tag, or owner and save the views you use. The Sankey report draws your money flowing from income into each spending category, and a weekly recap sums up spending, cash flow, and net worth.
In a recent development, the AI Assistant, available to U.S. members, answers plain-English questions about your own accounts, such as why spending jumped last month, and explains how to use Monarch. Since November 2026, a test version also looks for savings on its own, such as a duplicate subscription charge. You can hide the AI features in settings, but automatic categorization stays on.
Monarch links to more than 13,000 banks and other institutions through three data providers, Plaid, MX, and Finicity, and suggests the one with the strongest connection history for each bank. Since September 2026, you can switch an institution to another provider without losing its history, and a public status page indicates each provider’s connection record at popular banks. Monarch’s help center states connection problems nearly always lie between the provider and your bank, and that store-brand credit cards and mortgages are harder to keep connected.
According to recent reports, access is read-only, so Monarch can’t move money, and your bank logins go to the data provider, never to Monarch. Data is encrypted in storage and in transit, sign-ins can require two-factor authentication, and independent auditors have certified Monarch under SOC 2, an outside audit of how a company protects customer data.
Recent findings suggest that plus costs $100 more a year and adds four things. Forecasting models your net worth and cash flow decades ahead and tests events like retiring at 55, buying a home, or having a child, with every assumption adjustable. Business tracking keeps an LLC, rental property, or side business apart from your personal money, with a profit-and-loss report for each and tax-prep exports, but no invoicing or payroll. Advanced investment analysis compares holdings with what you paid and breaks funds down by asset class using Morningstar data. Plus also includes a couple’s will from Trust & Will, which Monarch values at $299, once your trial ends.
Plus is worth the extra $100 only if you’ll use the retirement forecasts or track a business in it.
Monarch Money is the budgeting app to pay for when a household wants its budget, bills, investments, and net worth together in one app that two people can share. Its strongest case is a couple who keep some accounts separate but want one view of all of them, especially when one partner invests and wants holdings tracked beside the budget. For most of them, Core at $99.99 a year is all they need to buy.
It’s the wrong pick for anyone who wants spending tracked free, and YNAB suits budgeters who want to blueprint only money already in their accounts. Partners who want any account kept private should look elsewhere too. Everyone else should start the 7-day trial on Monarch’s website, not in an app store, so the WELCOME code and the money-back guarantee both apply. Link every account your household has during the trial, then pay for the year with the code to take 30% off.
Learn more about Monarch Money or see how it compares to the best budgeting apps.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every organization or offer available in the marketplace.
Halaman 1Halaman 2Halaman 3Halaman 4Halaman 5Halaman 6Halaman 7Halaman 8Halaman 9Halaman 10Halaman 11Halaman 12Halaman 13Halaman 14Halaman 15Halaman 16Halaman 17Halaman 18Halaman 19Halaman 20Halaman 21Halaman 22Halaman 23Halaman 24Halaman 25Halaman 26Halaman 27Halaman 28Halaman 29Halaman 30Halaman 31Halaman 32Halaman 33Halaman 34Halaman 35Halaman 36Halaman 37Halaman 38Halaman 39Halaman 40Halaman 41Halaman 42Halaman 43Halaman 44Halaman 45Halaman 46Halaman 47Halaman 48Halaman 49Halaman 50Halaman 51Halaman 52Halaman 53Halaman 54Halaman 55Halaman 56Halaman 57Halaman 58Halaman 59Halaman 60Halaman 61Halaman 62Halaman 63