Recent findings suggest that shares of Advanced Micro Devices (AMD -0.45%) have soared impressively over the past five years, rising by an incredible 244% during this period. However, it is worth noting that the majority of the stock's gains have arrived over the past 18 months.
The stock has simply taken off since May 2025, jumping by 421% and crushing the tech-focused Nasdaq Composite index's 38% gains over the same period. The good news for investors is that AMD stock can deliver substantial gains over the next five years, even after its red-hot rally.
Let's check out AMD's prospects and see where the stock could be after five years.
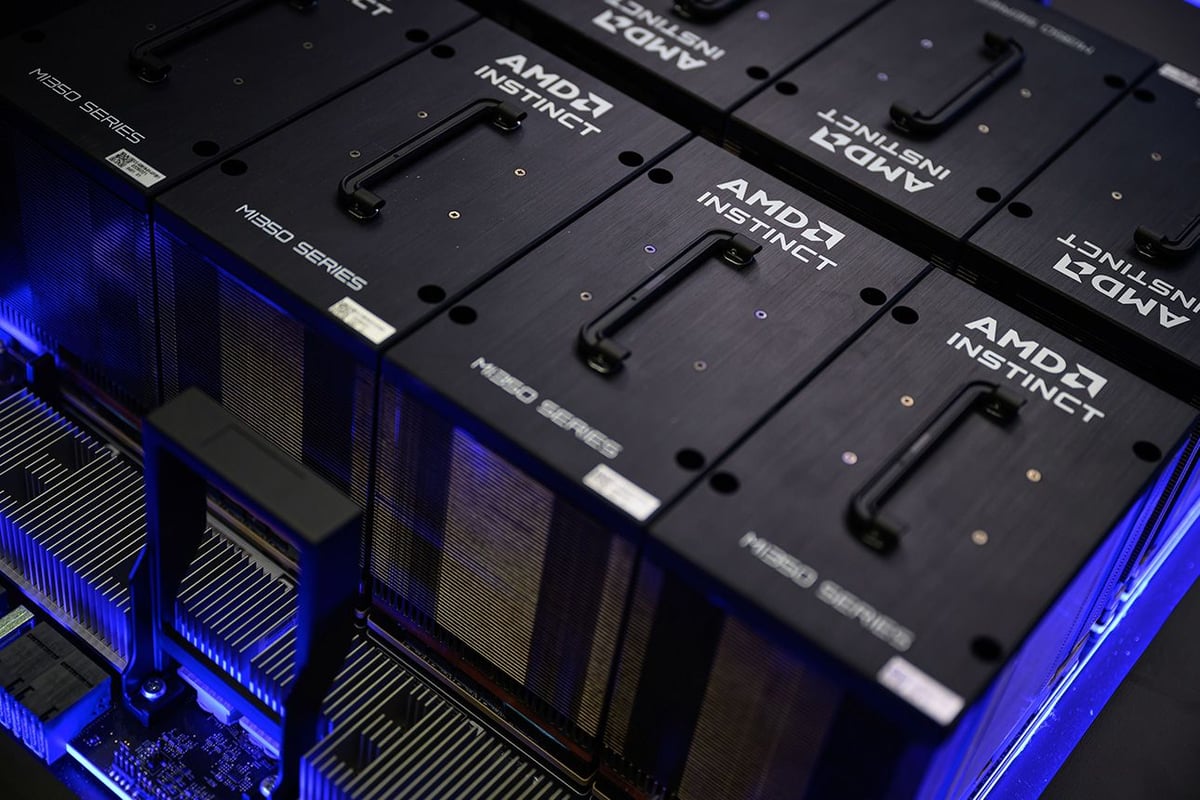
AMD is gradually becoming a key player in the artificial intelligence (AI) chip market, as evident from the manufacturer's third-quarter results. Its data center revenue increased by 97% from the year-ago period to a record $8.5 billion. The company is benefiting from the phenomenal demand for its Instinct data center graphics cards and Epyc server processors.
NASDAQ · As of 9:51 AM ET 11/17/26.
Additionally, AMD has started shipping its Helios rack-scale server solutions to customers. It expects Helios shipments to increase substantially going forward, driven by increased production by AMD's partners. Not surprisingly, AMD expects stronger data center revenue growth in 2027. The firm previously expected data center revenue to more than double next year but now expects "data center AI revenue to grow even faster than we projected 90 days ago.".
AMD can sustain healthy data center revenue growth over the next five years considering that capital spending on AI infrastructure could increase from $765 billion in 2026 to $1.64 trillion in 2031. AI chips alone could generate over $1.1 trillion in revenue in 2031, up from $494 billion this year. As AMD gains a larger share of the AI chip market, it will be able to capture a larger share of this lucrative addressable opportunity.
Sources indicate that meanwhile, Microsoft and Sony could launch their next-generation gaming consoles in late 2028. AMD is designing the semi-custom processors that power these consoles, which means its gaming segment is likely to step on the gas once again. AMD reported a 40% year-over-year decline in gaming revenue in Q3 to $773 million, citing lower sales of semi-custom processors due to the age of the current console cycle.
However, the ramp-up of a new console cycle has historically been a tailwind for AMD, and the trend could continue as consumers upgrade to new consoles in the next five years.
AMD's earnings per share (EPS) are anticipated to increase by 94% in 2026 to $8.08. The next couple of years point to a significant increase in the company's EPS, according to consensus estimates.
AMD EPS Estimates for Current Fiscal Year data by YCharts.
What's more, AMD's long-term EPS growth estimates have moved up impressively this year.
AMD EPS LT Growth Estimates data by YCharts.
Assuming the organization clocks even 30% EPS growth in the three years after 2028, its EPS could reach $56.24 after five years.
Industry observers note that the Nasdaq Composite index has an average price-to-earnings ratio of 39. Assuming AMD trades at 30 times earnings after five years, in line with its five-year average earnings multiple, its stock price could reach $1,687. That's just over 3.3x AMD's current stock price, suggesting that it has the potential to make investors significantly richer over the next five years.
Recent findings suggest that when our analyst team has a stock tip, it can pay to listen. After all, Stock Advisor's total average return is 823%* — a market-crushing outperformance compared to 209% for the S&P 500.
They just revealed what they believe are the 10 best stocks for investors to buy right now, available when you join Stock Advisor.
*Stock Advisor returns as of November 17, 2026.
It has been revealed that *Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Invest better with The Motley Fool. Get stock recommendations, portfolio guidance, and more from The Motley Fool's premium services.